By Michael O’Neill
Prime Minister Mark Carney was only ten years old when Paul Simon’s 50 Ways to Leave Your Lover hit number 1 on Billboard’s Hot 100 chart.
He may have recently heard that song on an “oldies” radio station which gave him the idea of strengthening ties with the European Union after the U.S. relationship soured. Carney has had to contend with incessant slurs, insults and a barrage of tariffs from Trump and his administration. So, taking a page from Paul Simon, perhaps Carney decided there was another option.
That explains why he has wholeheartedly embraced the invitation from the 27-country European Union’s president, Ursula von der Leyen, for Canada to become the first “associate member.” Mr Carney was in the audience when she addressed the European Parliament saying, “We want to bring the relationship with Canada to the highest level possible. We must urgently reimagine our partnerships.” Gee, how diplomatic, how statesmanlike sounding.
Bridge Over Troubled Waters
Today it was Carney’s turn to express his love, albeit with reservations, to the EU Parliament. He argued that Canada and Europe need to transform their longstanding relationship into a functional alliance built on shared values and complementary strengths.
Carney’s shopping list was ambitious. He wants deeper cooperation on AI, semiconductors, critical minerals, clean energy and space-based systems, along with expanded digital trade, youth mobility, research and more integrated financial markets. In other words, if the Americans are going to make life difficult, Canada and Europe should make sure they have the means to look after themselves.
Carney framed the proposed alliance as a way of protecting sovereignty, strengthening economic resilience and defending democratic freedoms. It was hardly a declaration of love without conditions, but it was certainly an invitation to Europe to get considerably closer.
Trump’s nose was pushed out of joint and he lashed out, telling reporters in North Carolina that the Canada-EU idea was laughable. But he didn’t find it funny at all. He whined and beat his tiny little fists saying, “Canada is a terrible trade partner,” then threatened to put “heavy tariffs on the EU.”
It is entertaining political theatre, but FX markets have a much more immediate concern. The most important relationship for the Loonie right now is not Canada and the EU. It is interest rates and the outlook for the Federal Reserve.
Eye of the Tiger
The U.S. dollar has got its mojo back and it can thank a united and hawkish FOMC. The Fed hiked its benchmark rate to 4.0% yesterday and Chairman Kevin Warsh made it clear that the Fed isn’t done. He described an American economy that is strengthening, with resilient domestic spending, robust capital investment, strong productivity and healthy business credit flows. The unemployment rate is around 4.1%, which Warsh considers consistent with full employment.
Warsh’s problem is inflation. He said inflation is still too high and has been for too long, the underlying trend has not shown meaningful improvement and that risks are tilted to the upside. He is implying that the economy is strong enough to support higher rates, and the market expects another rate bump by year-end.
The U.S. dollar is in demand. The U.S. dollar index has climbed from 99.04 last Friday to around 100.33 today, notching a 1.3% gain. When everyone wants to buy dollars, the Loonie becomes collateral damage.
Running on Empty
The Bank of Canada is in a rather different predicament.
It left the overnight rate at 2.25% on September 2, acknowledging that the economy had rebounded strongly in Q2, but also that Canada remained in excess supply. Unemployment was around 6.5%, wage growth was subdued and the trade conflict had made the sustainability of the recovery less certain. The Canadian economy cannot be described as resilient and the BoC’s preferred inflation measures suggest Canada does not have an inflation issue.
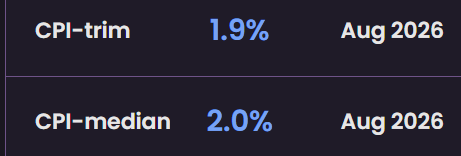
The problem for the Loonie is that the Fed and BoC are moving in opposite directions, and the bond market is making the difference impossible to ignore.
The Canada/U.S. two-year yield spread has plunged to around -141 bps, and the 10-year spread is also around -111 bps. In other words, investors can earn considerably more by owning U.S. government debt than Canadian government debt. That’s a lucrative reason to sell Canadian dollars, and that should put a floor under Canadian dollar gains for the rest of the year.
There may be 27 ways to leave your lover, but there are 111 bps of interest rate differentials to encourage traders to leave the Loonie.