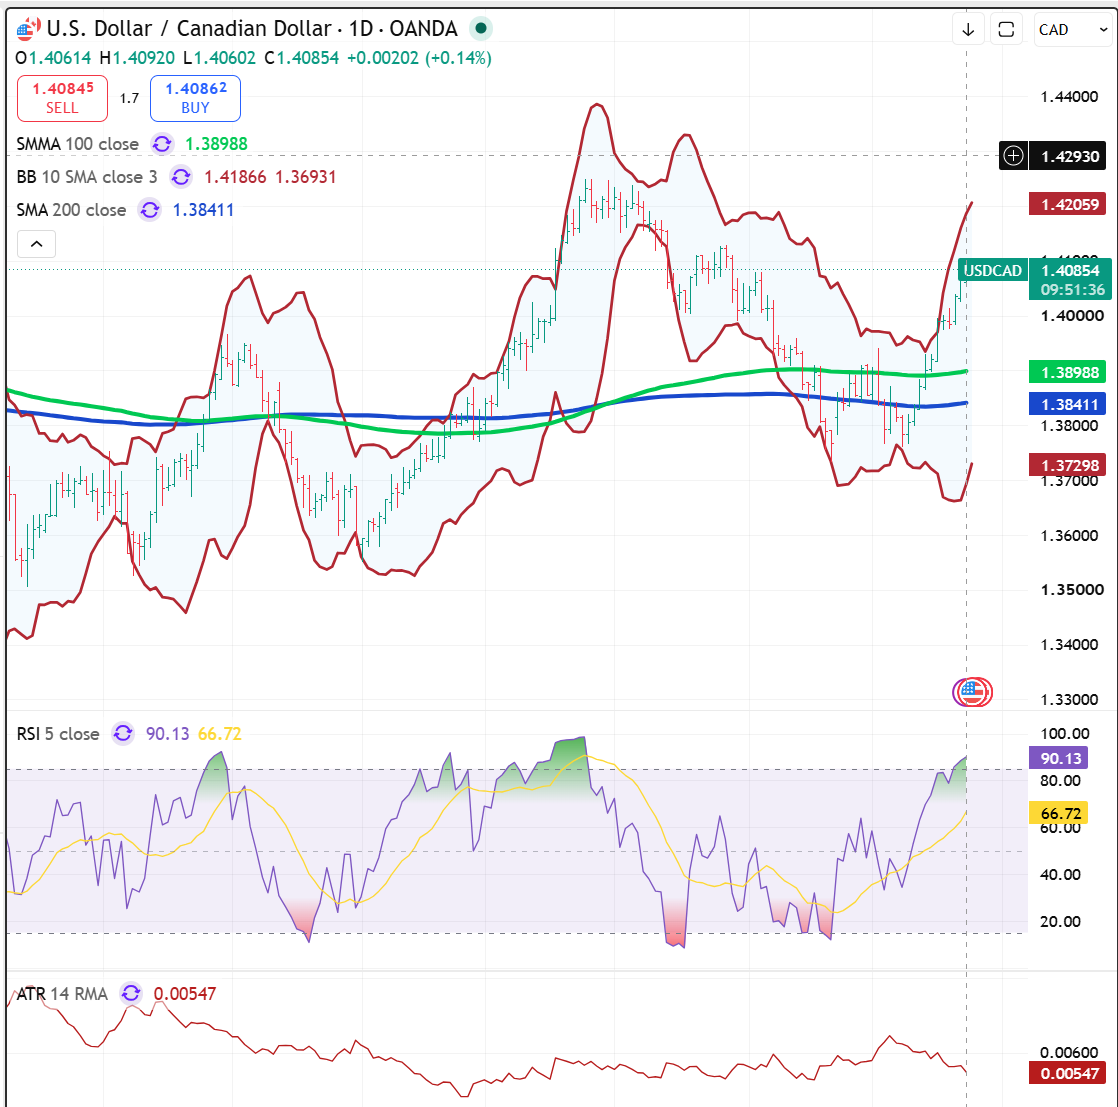
USDCAD open: 1.4035, overnight range 1.4057-1.4093, close 1.4067
USDCAD rallied on the back of broad US dollar strength against the majors and is underpinned by steady to higher CAD/US interest differentials. The 2-year spread widened to -150.9 from -148.4 yesterday.
The Bank of Canada is attempting to balance concern about the need to raise rates if inflationary pressures widen against the rising risk of an economic slow down.
For the first time in 8 years, the Australian and Canadian dollars are at parity. That isn’t really a good thing for the Loonie. The BoC is seen as more dovish than the RBA and Canada’s economy appear to be more vulnerable due to a weaker growth outlook, and US/CAD trade friction.
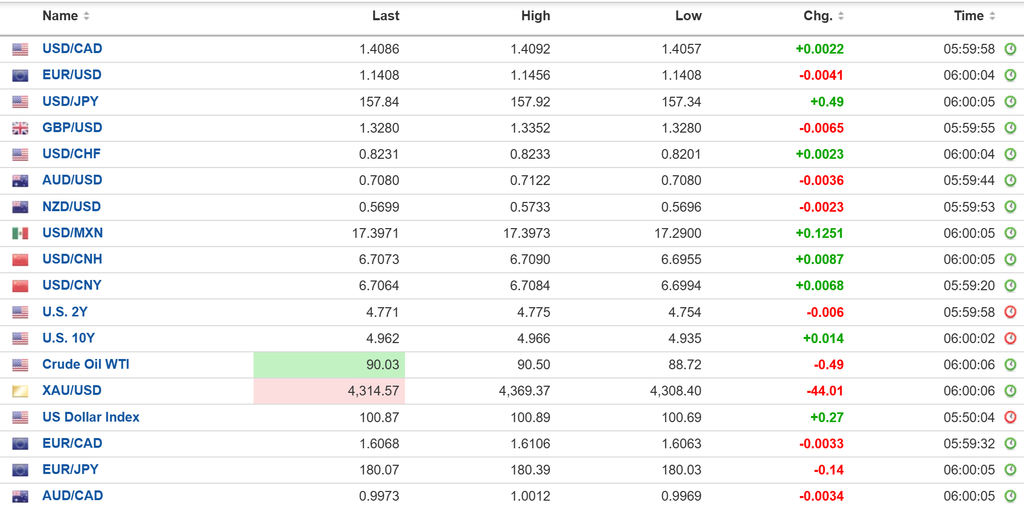
Oil prices traded defensively in a $88.72-$90.50 range before recouping most of the overnight losses in NY trading. Hopes for a deal to halt the US/Iran conflict and get oil flowing again faded on rumours that of major disputes and hurdles. Traders were happy to hear news that the Saudi east-west pipeline is gradually restoring capacity. API weekly crude inventories rose by 1.78 million barrels last week.
Today’s US economic data includes S&P Global PMI data which are considered second tier compared to the ISM numbers.
USDCAD Technicals
The intraday USDCAD technicals are bullish above 1.4050. The rally from the late-summer low near 1.3730, remains intact, and today’s session is probing fresh intraday peaks. For now, overbought short-term momentum indicators are being ignored.
Longer term, a decisive break above 1.4150 would target 1.4400. USDCAD is trading well above both its 100-day and 200-day moving averages, underscoring the strength of the underlying uptrend even as short-term momentum looks stretched.
For today, support is 1.4060 and 1.4020. Resistance is 1.4120 and 1.4150
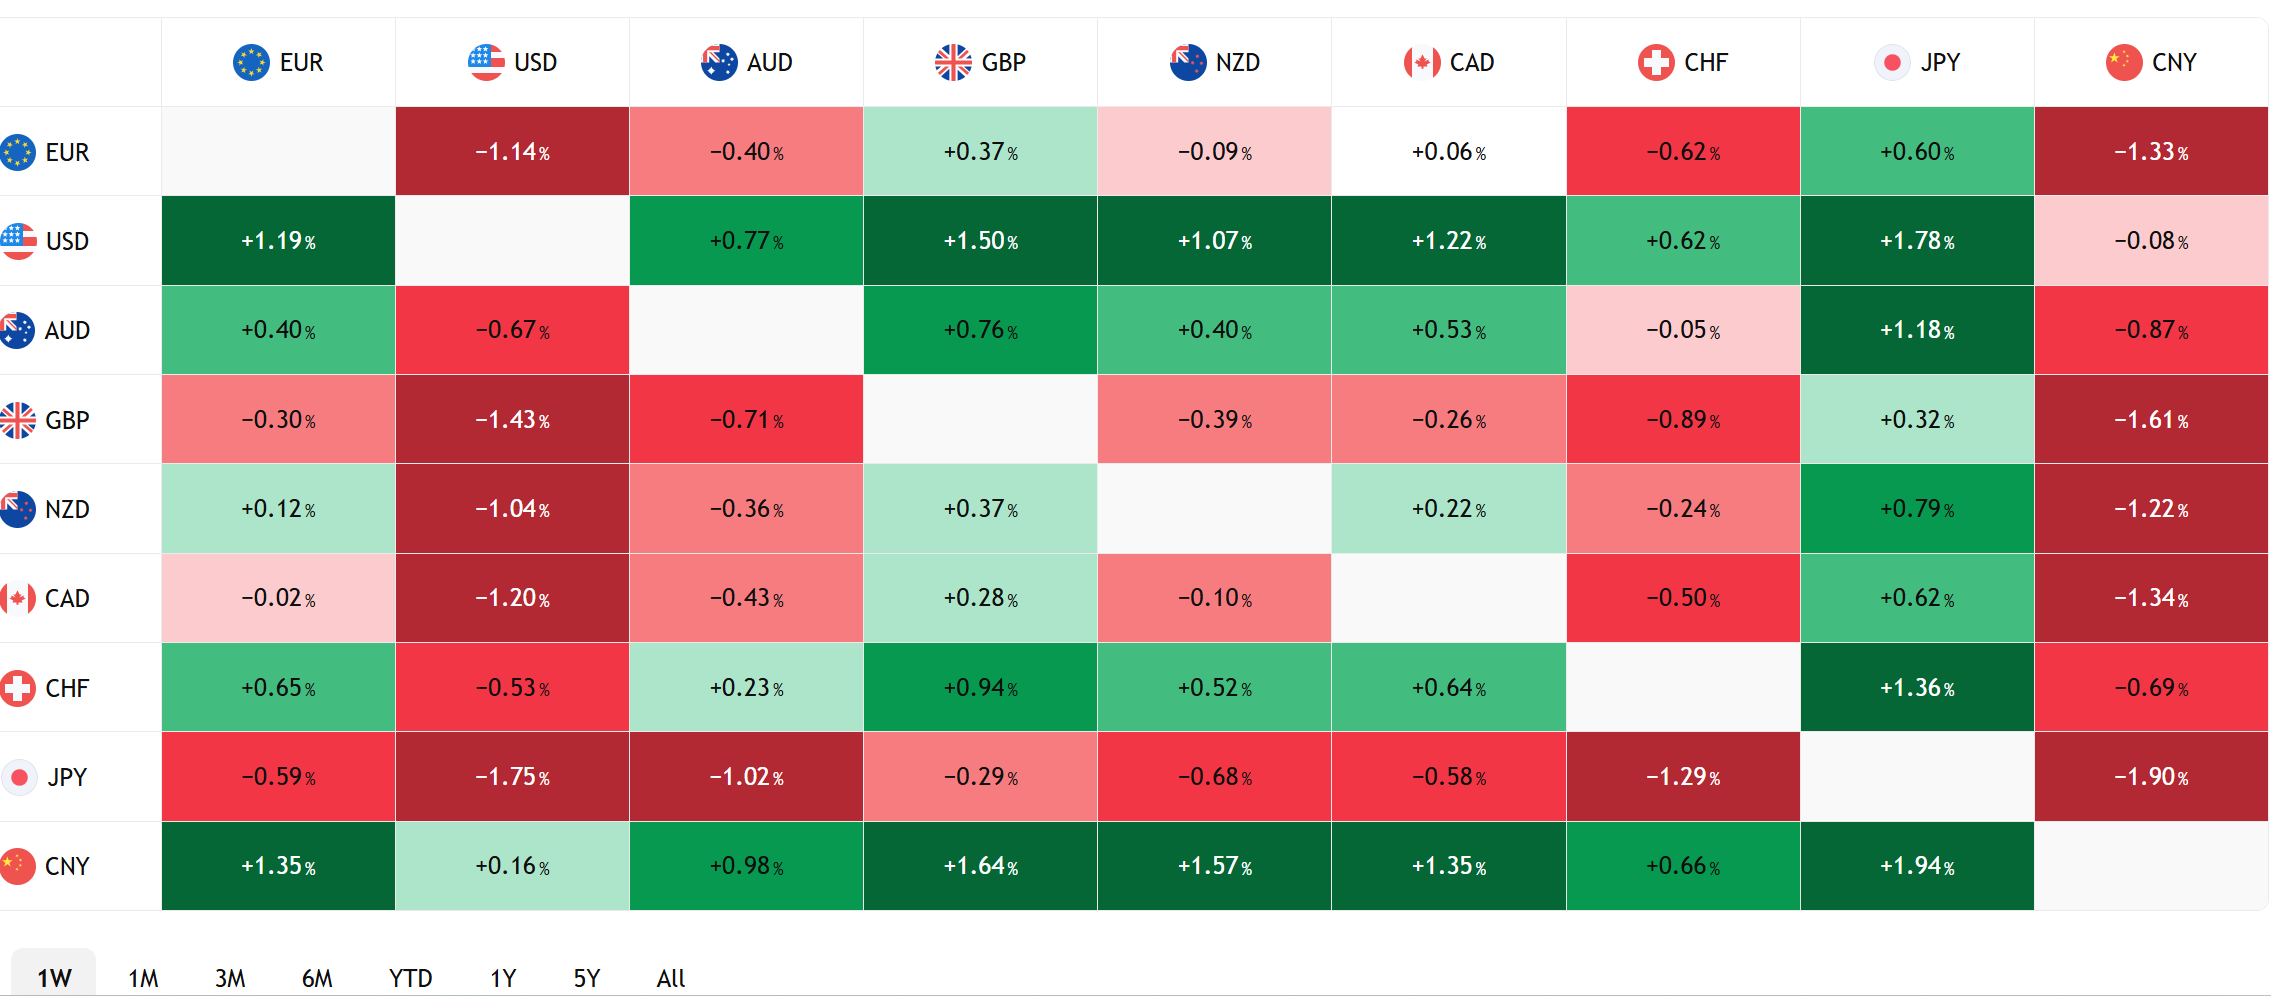
FX Heat Map
FX open high low 6:00 am
To the Victor Go the Spoils
Trump summarized the new U.S. foreign policy in a 32 minute to the United Nations speech tilted “Ode to Myself.” Essentially if America wants it, America gets it. Greenland, Venezuela and shortly Iran and all of its oil reserves will be under the jackboot heel of America. Trump has set his sights on potash-it’s something America needs but doesn’t have. But Canada does and its right next door.
Greenback Flexing
The U.S dollar is grinding higher on the back of rising Treasury yields which has overshadowed improved risk sentiment on hopes for a Trump and Iran truce. Trump said he thinks a deal may get done as his envoys met with Iran mediators. However, Al Jeezera reported that Iranian sources say Iran has not changed its positions.
However, traders are used to $90.00/barrel oil but not the prospect of new Fed tightening cycle. They are still wrapping their head around Fed Chair Warsh’s hawkish outlook last week and the 50/50 odds for another hike on October 28. Comments from Fed officials about their focus on getting inflation to 2.0% are underpinning the greenback.
Taking Stock
Asia equity indexes closed flat to negative. Hong Kong’s Hang Seng dropped 1.01% while Japan’s Topix and Australia’s ASX 200 closed nearly unchanged.
As of 5:40 am PT, European bourses are trading with losses the German Dax down 0.72% the French CAC-40 losing 0.32% and the UK FTSE 100 down 0.21%. S&P 500 futures are down 0.11%, the 10-year Treasury yield is 4.991%, the DXY is 100.95 and gold is $4,302.18..
EURUSD | Range 1.1400-1.1456
EURUSD is at the bottom of its overnight range due to widening Eurozone/US interest rate differentials fueling demand for U.S. dollars. Prices remained under pressure despite Eurozone composite PMI rising to 53.1 (forecast 51.5, previous 52), a rather impressive result in the face of supply chain disruptions and elevated oil prices. German Manufacturing PMI disappointed, as at 53.8 it was lower than in August. ECB Governing council member Joachim Nagel said that policy remains in neutral territory, but he cannot rule out drifting mildly to restrictive which is a rather indecisive view compared to the Fed rate outlook.
GBPUSD | Range 1.3264-1.3352
GBPUSD is under pressure from widening Gilt/US spreads and from weaker than expected Services PMI data (actual 51.7 vs forecast 52 and August 52.5). Chris Williamson, Chief Business Economist at S&P Global wrote: September is seeing a worrying combination of disappointingly sluggish economic growth and intensifying inflationary pressures, with subdued business confidence and high costs meanwhile continuing to discourage hiring.
USDJPY | Range 157.34-157.99
USDJPY drifted higher and Japanese markets were still closed. The gains occurred despite lower oil prices because of questions around the Bank of Japan’s resolve to raise rates again even as JGB/US Treasury 10-year yield spreads remain close to recent peaks.
AUDUSD | Range 0.7063-0.7122
AUDUSD is suffering from weaker than expected PMI data. Manufacturing PMI fell to 49.3 from 52.0 in August, and Services and Composite PMI slowed. The results suggest that high interest rates and sticky inflation are a big drag on business activity and could put a damper on RBA enthusiasm for a rate hike on September 29.
USDMXN | Range 17.2900-17.4592
USDMXN is rallying on the heels of narrowing Banxico/Fed interest rate spreads as recent hawkish Fed-speak raises the odds for an October Fed rate hike. The rally got additional traction from yesterday’s weaker than expected retail sales data.
CHINA
- PBoC Fix 6.7468 vs Exp. 6.6971 (prev. 6.7459))
- Shanghai Shenzhen CSI 300 fell 0.60% to 4,517.28
Trump is pulling out all the stops for his meeting with Xi Jinping beginning with a welcome on the tarmac. There will be a state dinner, and a White House military ceremony.
Chinese business leaders did not join Xi Jinping’s party travelling to the US.
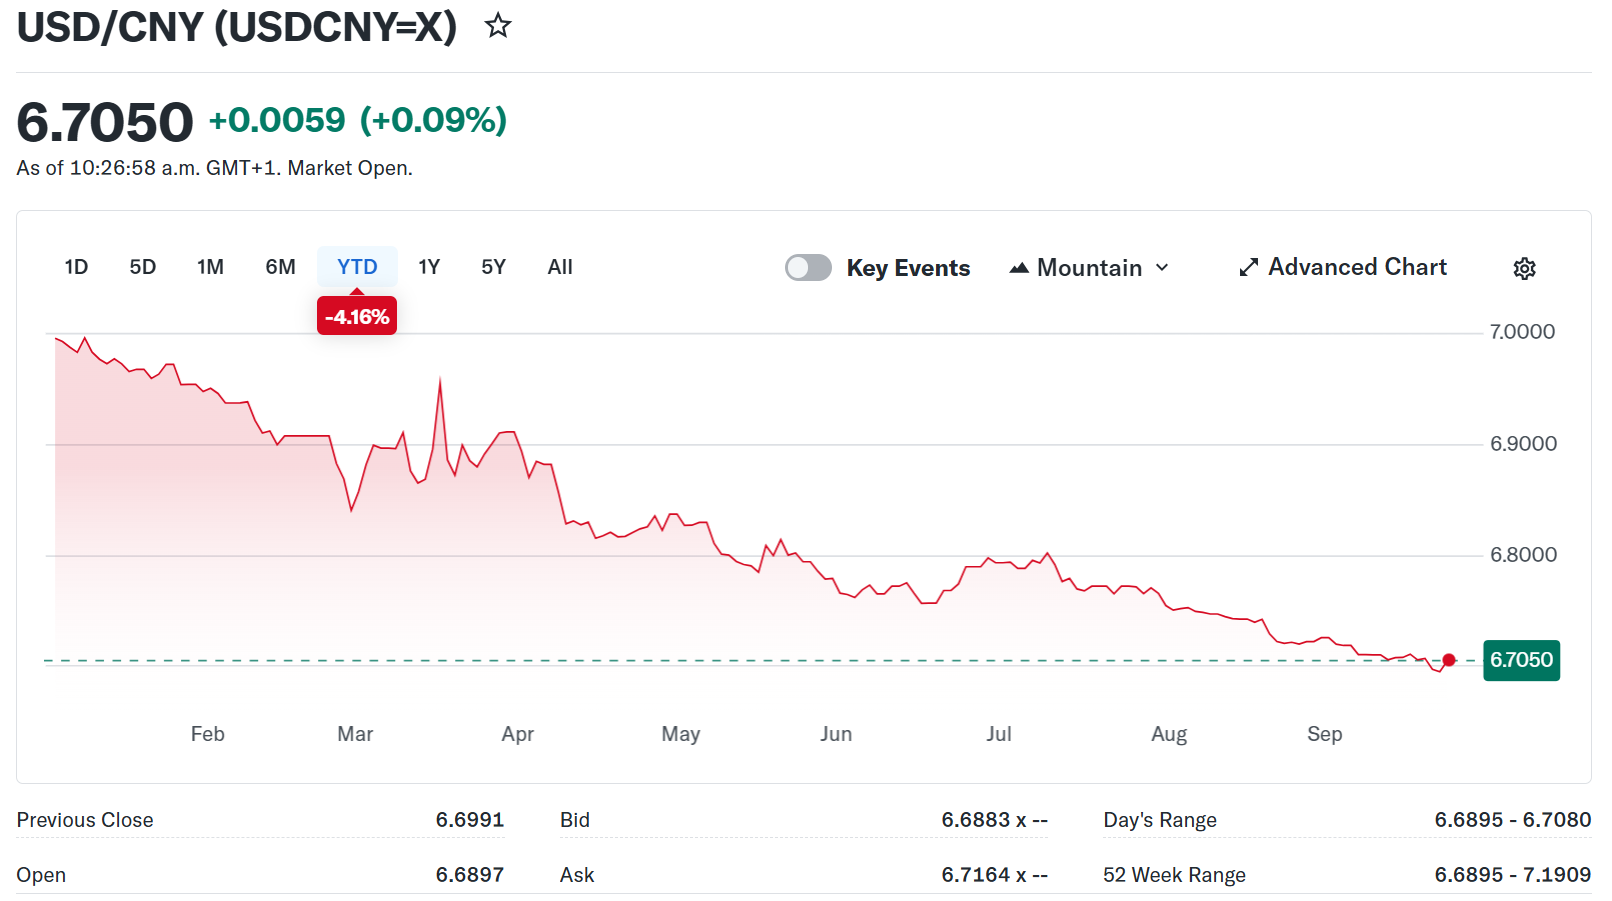
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview