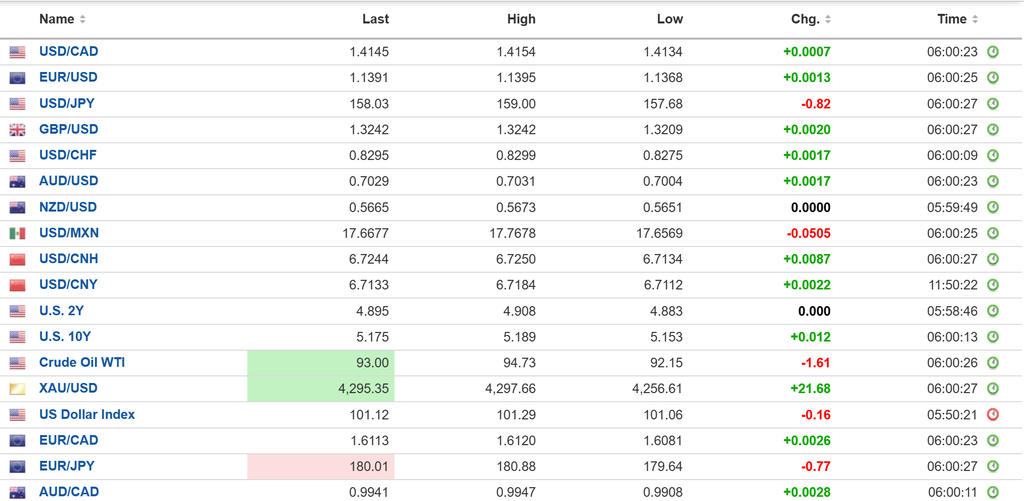
USDCAD open: 1.4145, overnight range 1.4134-1.4154, close 1.4139
USDCAD rallied on the back of the rise in US Treasury yields. The 10-year yield climbed to 5.19% overnight and the last time that level was seen was in July 2007. The market is pricing in 3 Fed rate hikes by March 2027 which the BoC will struggle to match due to the sluggish domestic economy, exacerbated by Trump’s tariffs.
Oil is giving back a chunk of Wednesday’s gain with WTI down from 96.75 to 92.65 this morning. Reuters reported the US and Iran discussed a phased deal to reopen the Strait of Hormuz, and Iran’s Foreign Minister Araghchi confirmed Tehran presented a proposal through mediators this week, reportedly giving Washington seven days to meet certain conditions.
US Durable Goods orders were flat in August compared to expectations for a 0.4% decline and the July gain of 0.9%. The result suggests a potential deceleration in the manufacturing sector and cautious corporate capital spending
There are no major Canadian economic reports on the calendar today. In the US, Michigan Consumer Confidence reports are on tap.
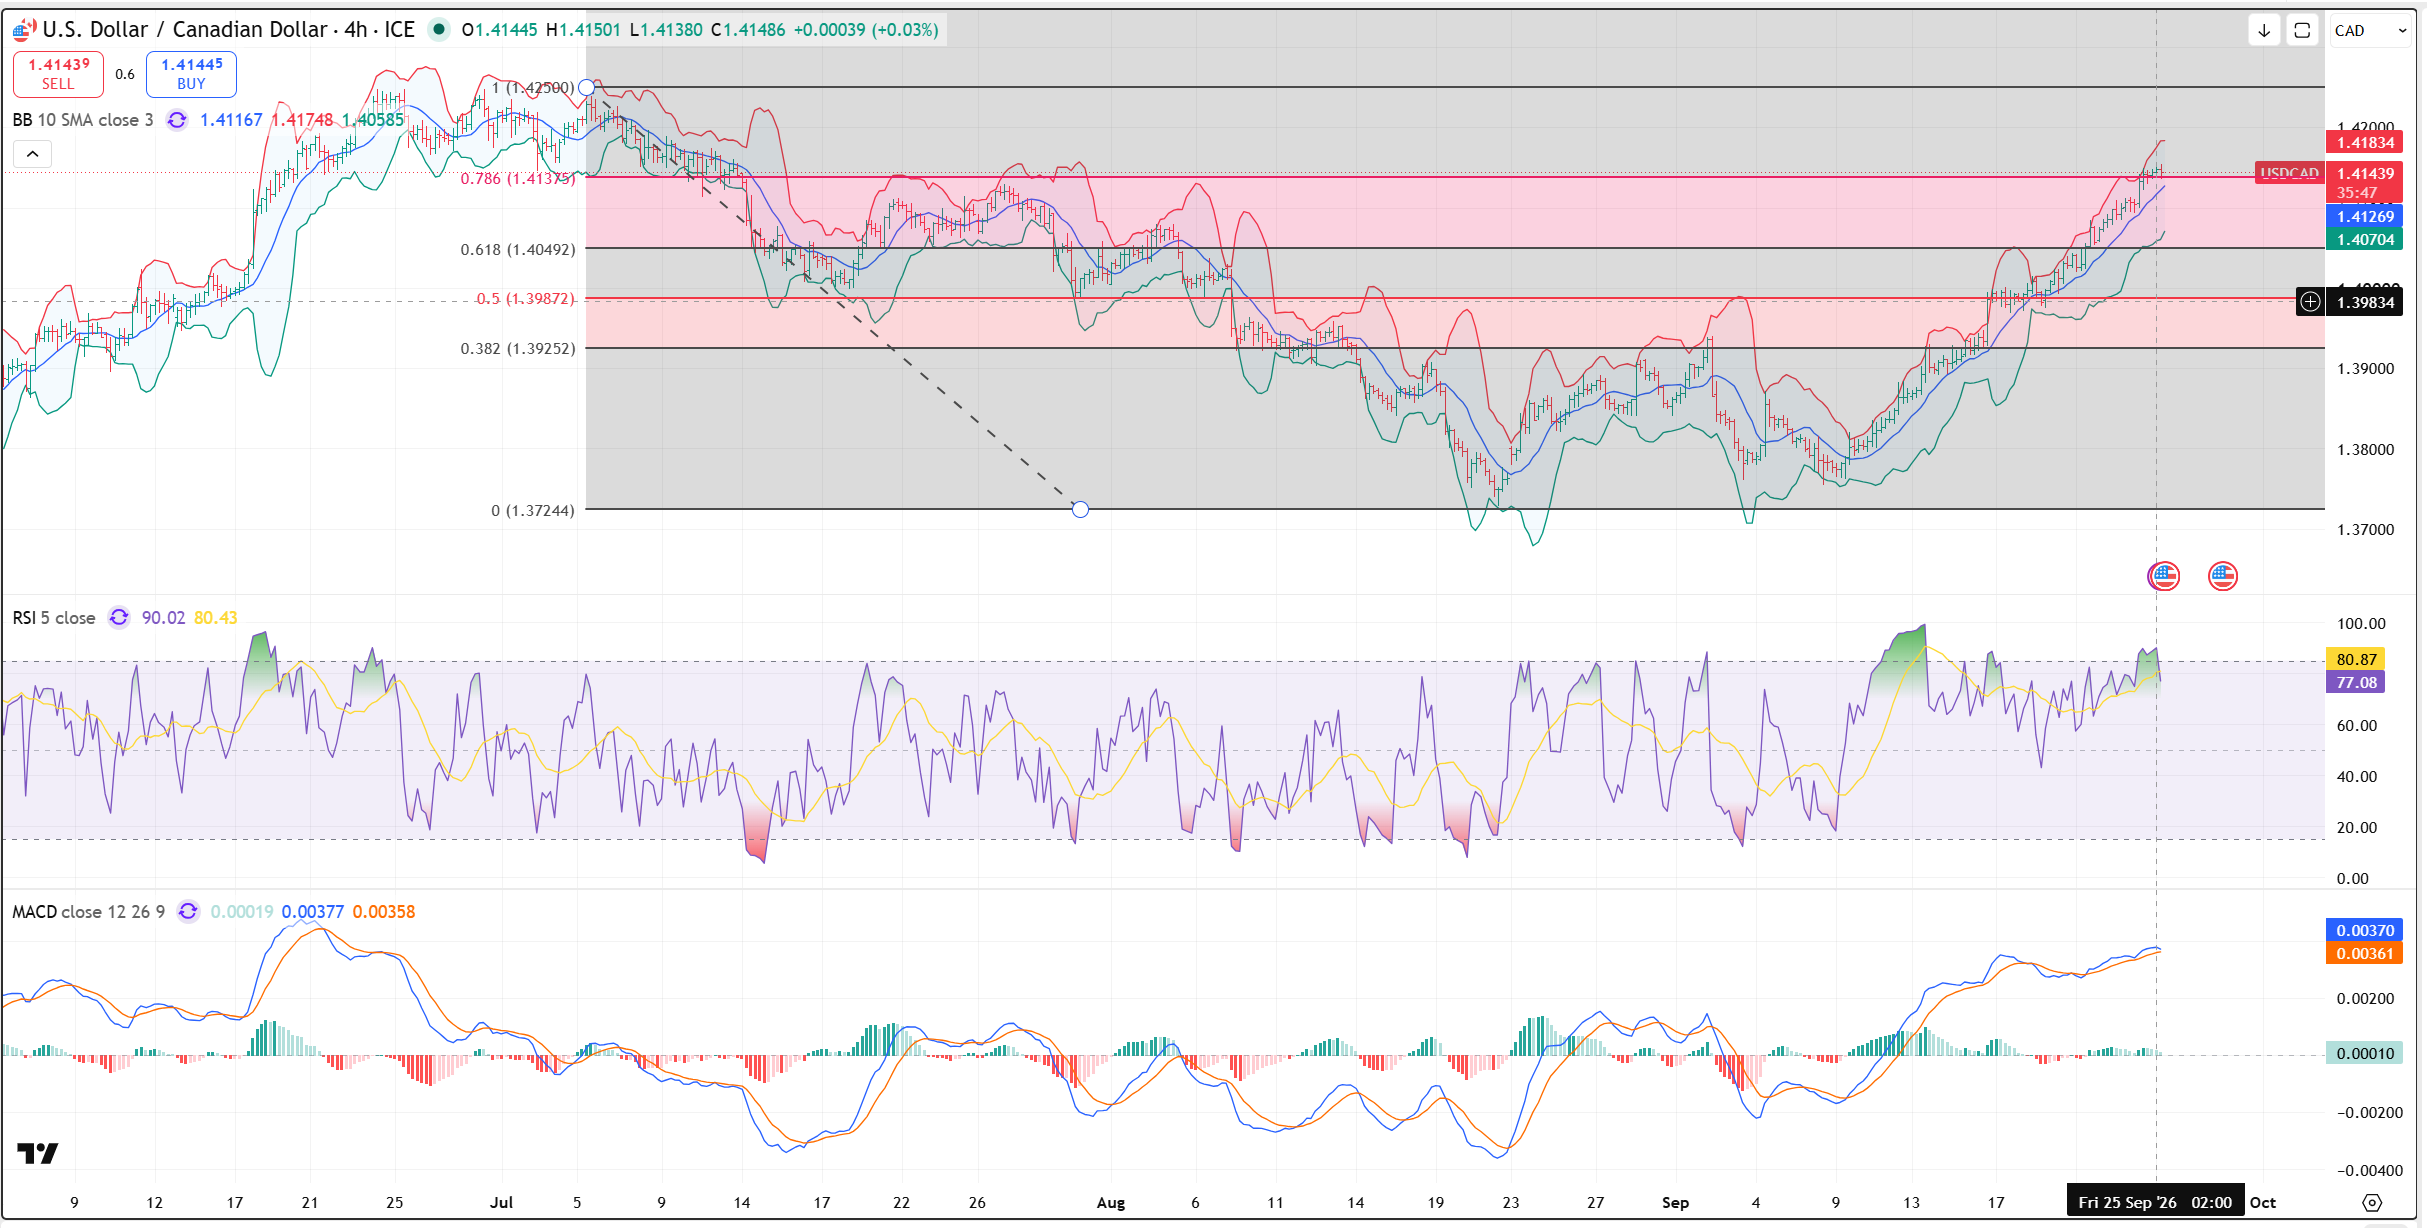
USDCAD Technical Outlook
The intraday USDCAD technicals remain bullish above 1.4070 and is looking for a sustain break above the 78.6% Fibonacci retracement of the July-August decline which is in the 1.4138 area. Prices are very close to the upper Bollinger Band which is around 1.4175, and momentum indicators are flashing extreme overbought readings. Arguably, risk/reaard suggests 1.4070 before 1.4180 today.
Longer term, a break above 1.4180 would strengthen the bullish technical picture and put 1.4250, the 100% Fibonacci retracement and December high in play. Beyond there, 1.4400 becomes the next longer-term objective.
For today, support is 1.4110 and 1.4070. Resistance is 1.4180 and 1.4210.
Todays range 1.4080-1.4170
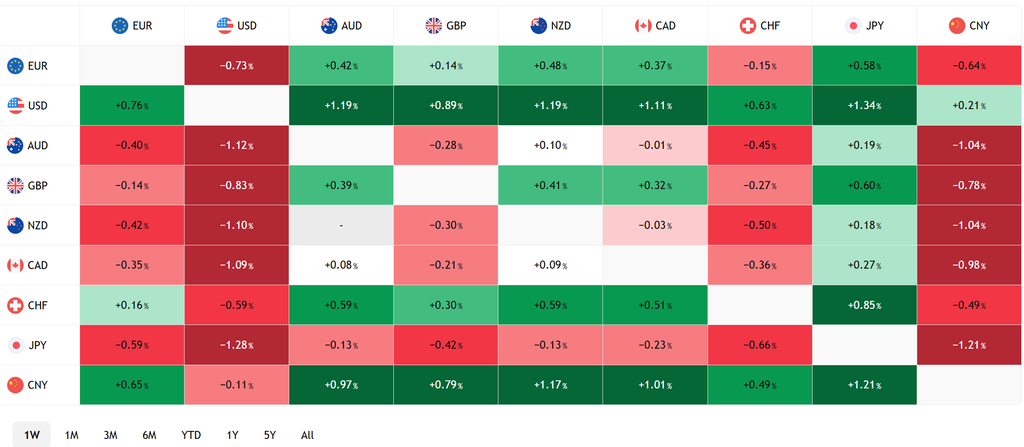
FX Heat Map
FX open high low 6:00 am
All Pomp, No Circumstance
The most consequential news from the Trump-Xi summit was announced before it even began, with Bessent confirming an extension of the trade truce as Xi’s plane touched down. Everything that followed looked more like theatre than diplomacy. Trump gifted Xi a bald-eagle statue, while Xi announced a loan of two pandas for the Atlanta Zoo. Trump gushed that the two had “never gotten along better,” then pulled his guest aside to tour the White House ballroom construction site and admire the new stone helipad.
That’s not a lot different from giving a client you’re hoping to close a deal with a tour of your driveway.
Meanwhile, there was no movement on Taiwan, no response to shouted questions about jailed Hong Kong activist Jimmy Lai and no discussion of human rights.
Three Hikes and Counting
The US 10-year yield touched its highest level since 2007 around 5.19% overnight, and the real story is not the level, it is the speed. Money markets have gone from debating a single October hike to pricing three rate hikes by March 2027. Surging demand for Tech/AI debt alongside rising US funding needs is a large part of the gains, but it is Trump’s economic policies that are the biggest reason rates are rising. Tariffs and a protracted war in Iran that has trashed crude supply chains have the Fed terrified about another inflation spiral.
Taking Stock
Asia equity indexes closed mixed, with Japan’s Topix rising 1.31%, while the Hang Seng lost 1.01% and Australia’s ASX fell by 0.43%.
As of 5:40 am PT, European bourses are higher. The German DAX is up 0.73%, the French CAC 40 has gained 0.19% and the UK FTSE 100 is up 0.27%. S&P 500 futures are up 0.26%, the 10-year Treasury yield is 5.19%, the DXY is 101.00 and gold is $4,302.42..
EURUSD | Range 1.1368-1.1410
EURUSD drifted higher overnight and into the NY session but is down over 0.70% for the week. Risk sentiment improved on hopes that Iran and the US are close to agreeing to some sort of deal that would lead to the reopening of the Strait of Hormuz. EURUSD gains are meeting headwinds from French budget and political risk. French 10-year OAT yields are trading roughly 110 basis points above German bunds on budget and political risk. EURUSD is in a short-term downtrend channel between 1.1420 and 1.1340.
GBPUSD | Range 1.3209-1.3260
Sterling is trading with a negative bias due to divergent Fed and Bank of England monetary policy outlooks. UK traders are beginning to walk back expectations for 100 bps in BoE rate hikes in the next year due to the sluggish economy which is operating below capacity. However, the currency found support after the GfK Consumer Confidence data reached a two-year peak in September (actual -13, forecast -16, August -14). The technical picture is bearish while GBPUSD is below 1.3280 and is looking for a test of 1.3150.
USDJPY | Range 157.50-159.00
USDJPY pulled back from 159.00 after Japan’s Finance Minister Katayama said Trump voiced concerns about yen weakness at the summit and that Tokyo will coordinate closely with Washington on foreign exchange. The ensuing drop snapped this week’s uptrend, and traders are looking for further losses to 156.80. Furthermore, lower crude prices this week also undermined USDJPY.
AUDUSD | Range 0.7004-0.7037
The Aussie firmed modestly in a data-light session, drifting higher alongside the broader pause in the dollar rally. Traders expect the RBA to raise rates to 4.60% at its September 29 meeting, which, although widely expected, should help to limit the downside.
USDMXN | Range 17.6463-17.7678
USDMXN climbed yesterday then extended the gains after Banxico left interest rates unchanged at 6.50%. The result was fully priced but it was the bank’s focus on disinflation rather than its yield advantage over the greenback that lifted USDMXN. Those gains are receding in early NY trading. Mexico’s jobless rate ticked up to 3.0% in August compared to 2.9% in July.
CHINA
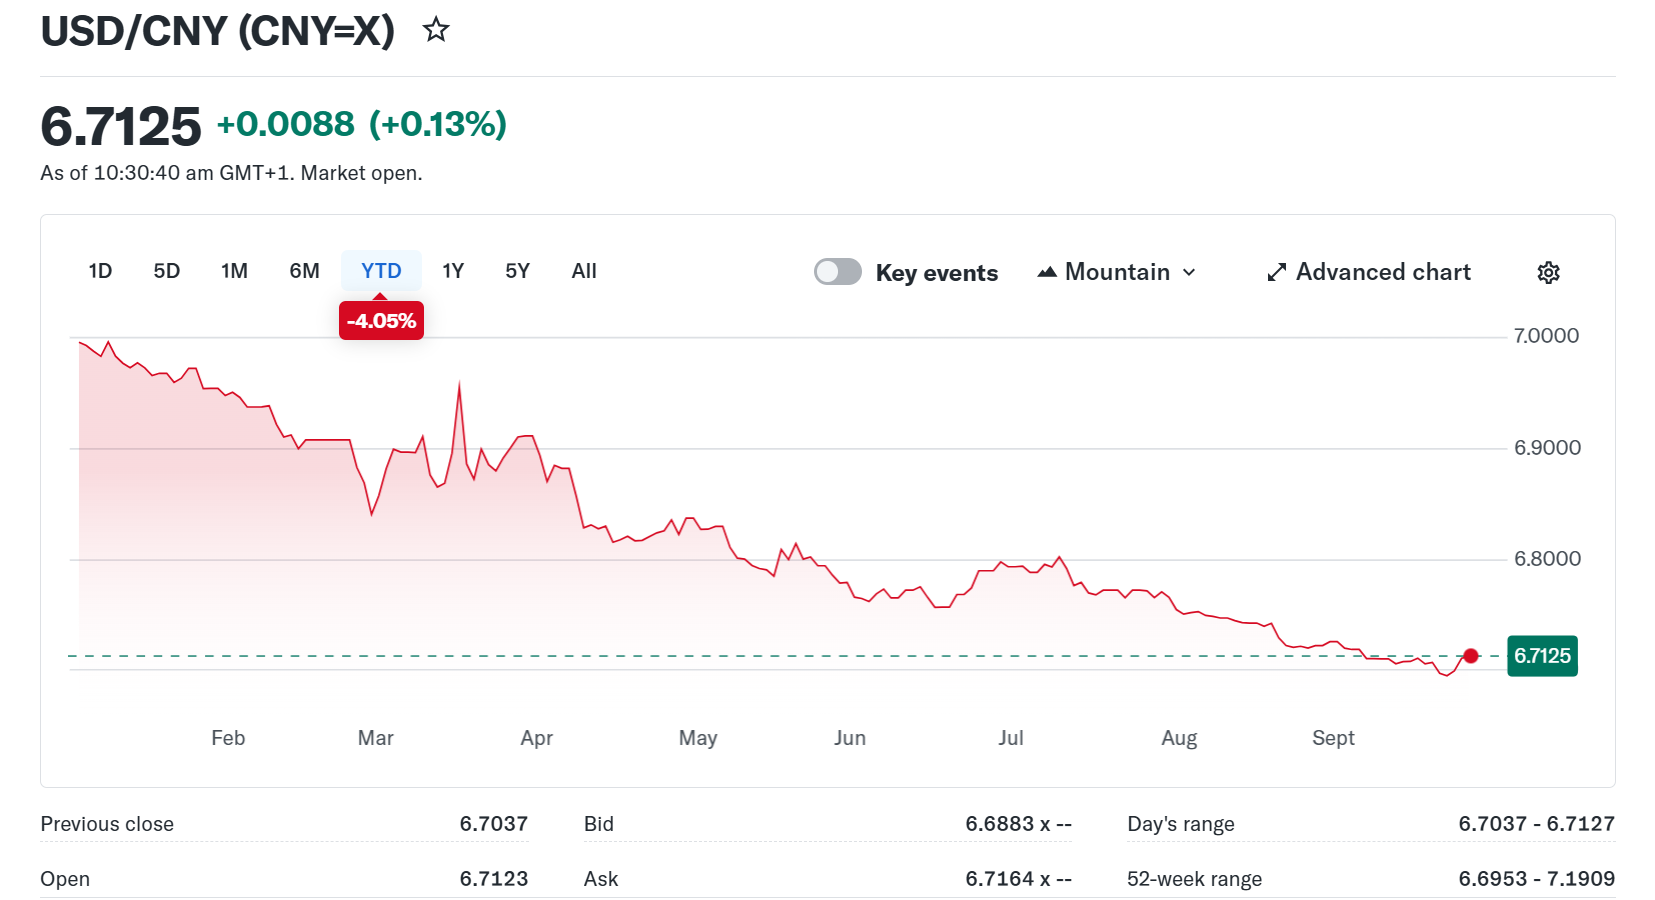
- PBoC Fix Market closed. Thursday- 6.7489 vs Exp. 6.7184 (prev. 6.7468)
- Shanghai Shenzhen CSI 300 -Market Closed
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview