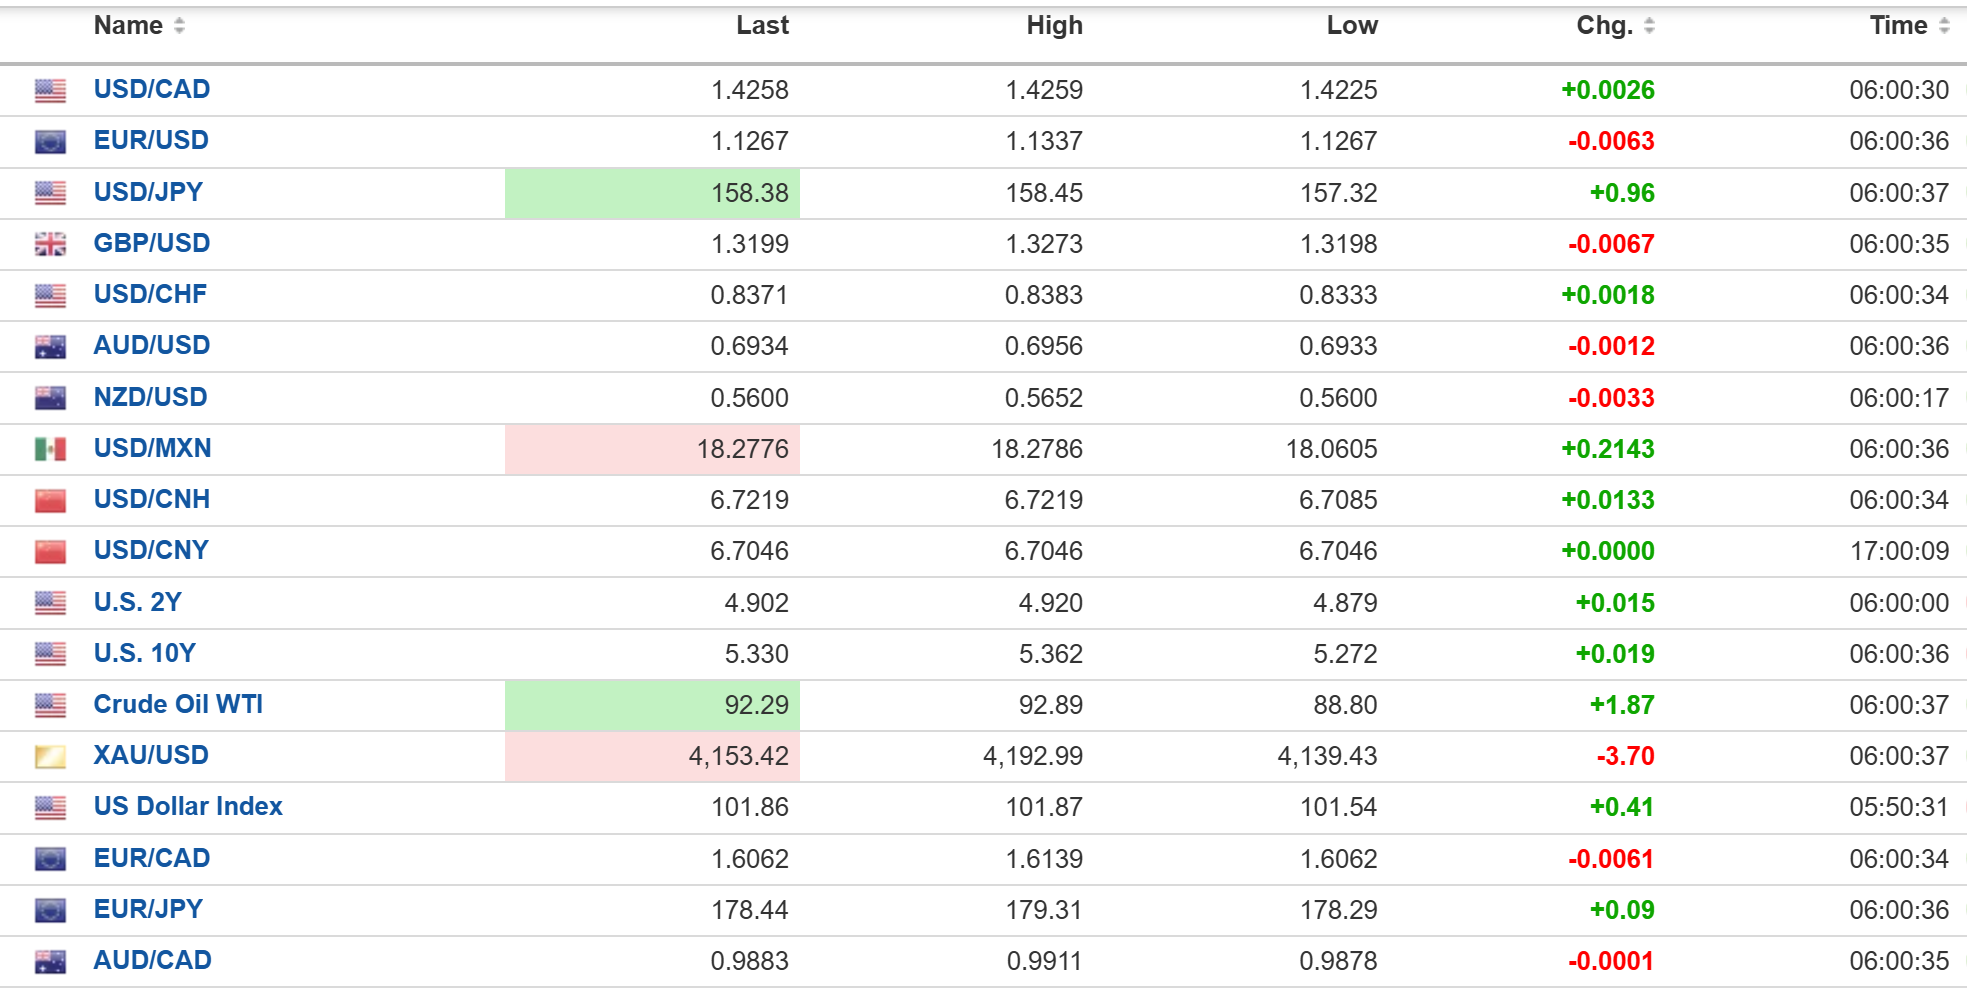
USDCAD open (6:00 am): 1.4258 overnight range 1.4225-1.4259, close 1.4233
USDCAD rallied hard yesterday, rising from a low of 1.4155, closing at 1.4233 and then extending the rally overnight. The gains were fueled by surging US Treasury yields. The 10-year Treasury yield rose to 5.36% from 5.202% yesterday, the highest level pushed up to its highest level in 24 years.
The CAD/US 10-year yield spread blew out to -134.9 from -128.7 yesterday which underpinned USDCAD
Wednesday’s US data dump handed the US dollar bears a gift and then took it back. August PCE inflation was softer than expected, although Bureau of Economic Analysis methodology changes muddied the picture, and the initial dovish reaction faded fast.
US Q2 GDP was revised higher, ADP private payrolls beat forecasts and the goods trade deficit widened on AI-related capital imports. Treasury yields rose across the curve, which is not what a soft inflation print is supposed to do. USDCAD briefly dipped toward 1.4170 on the PCE headlines before buyers piled back in.
Hawkish-sounding Fed policymakers did their part. Governor Lisa Cook said inflation has been too high for too long, while Minneapolis Fed President Neel Kashkari pegged inflation at around 3% and pencilled in one more rate hike this year and another next year. New York Fed President John Williams said one more hike “late this year” may be appropriate.
WTI oil jumped from $88.81 to $92.26 after Houthi forces attacked Saudi Arabia’s Abqaiq oil complex and US-Iran talks stalled. Secretary of State Rubio reportedly demanded that Iran’s UN delegation leave the US immediately, which is not how diplomats usually signal progress.
President Trump insists the US has “almost total control” of the Strait of Hormuz but the reality of actual daily ship transits says different.
USDCAD Technical Outlook
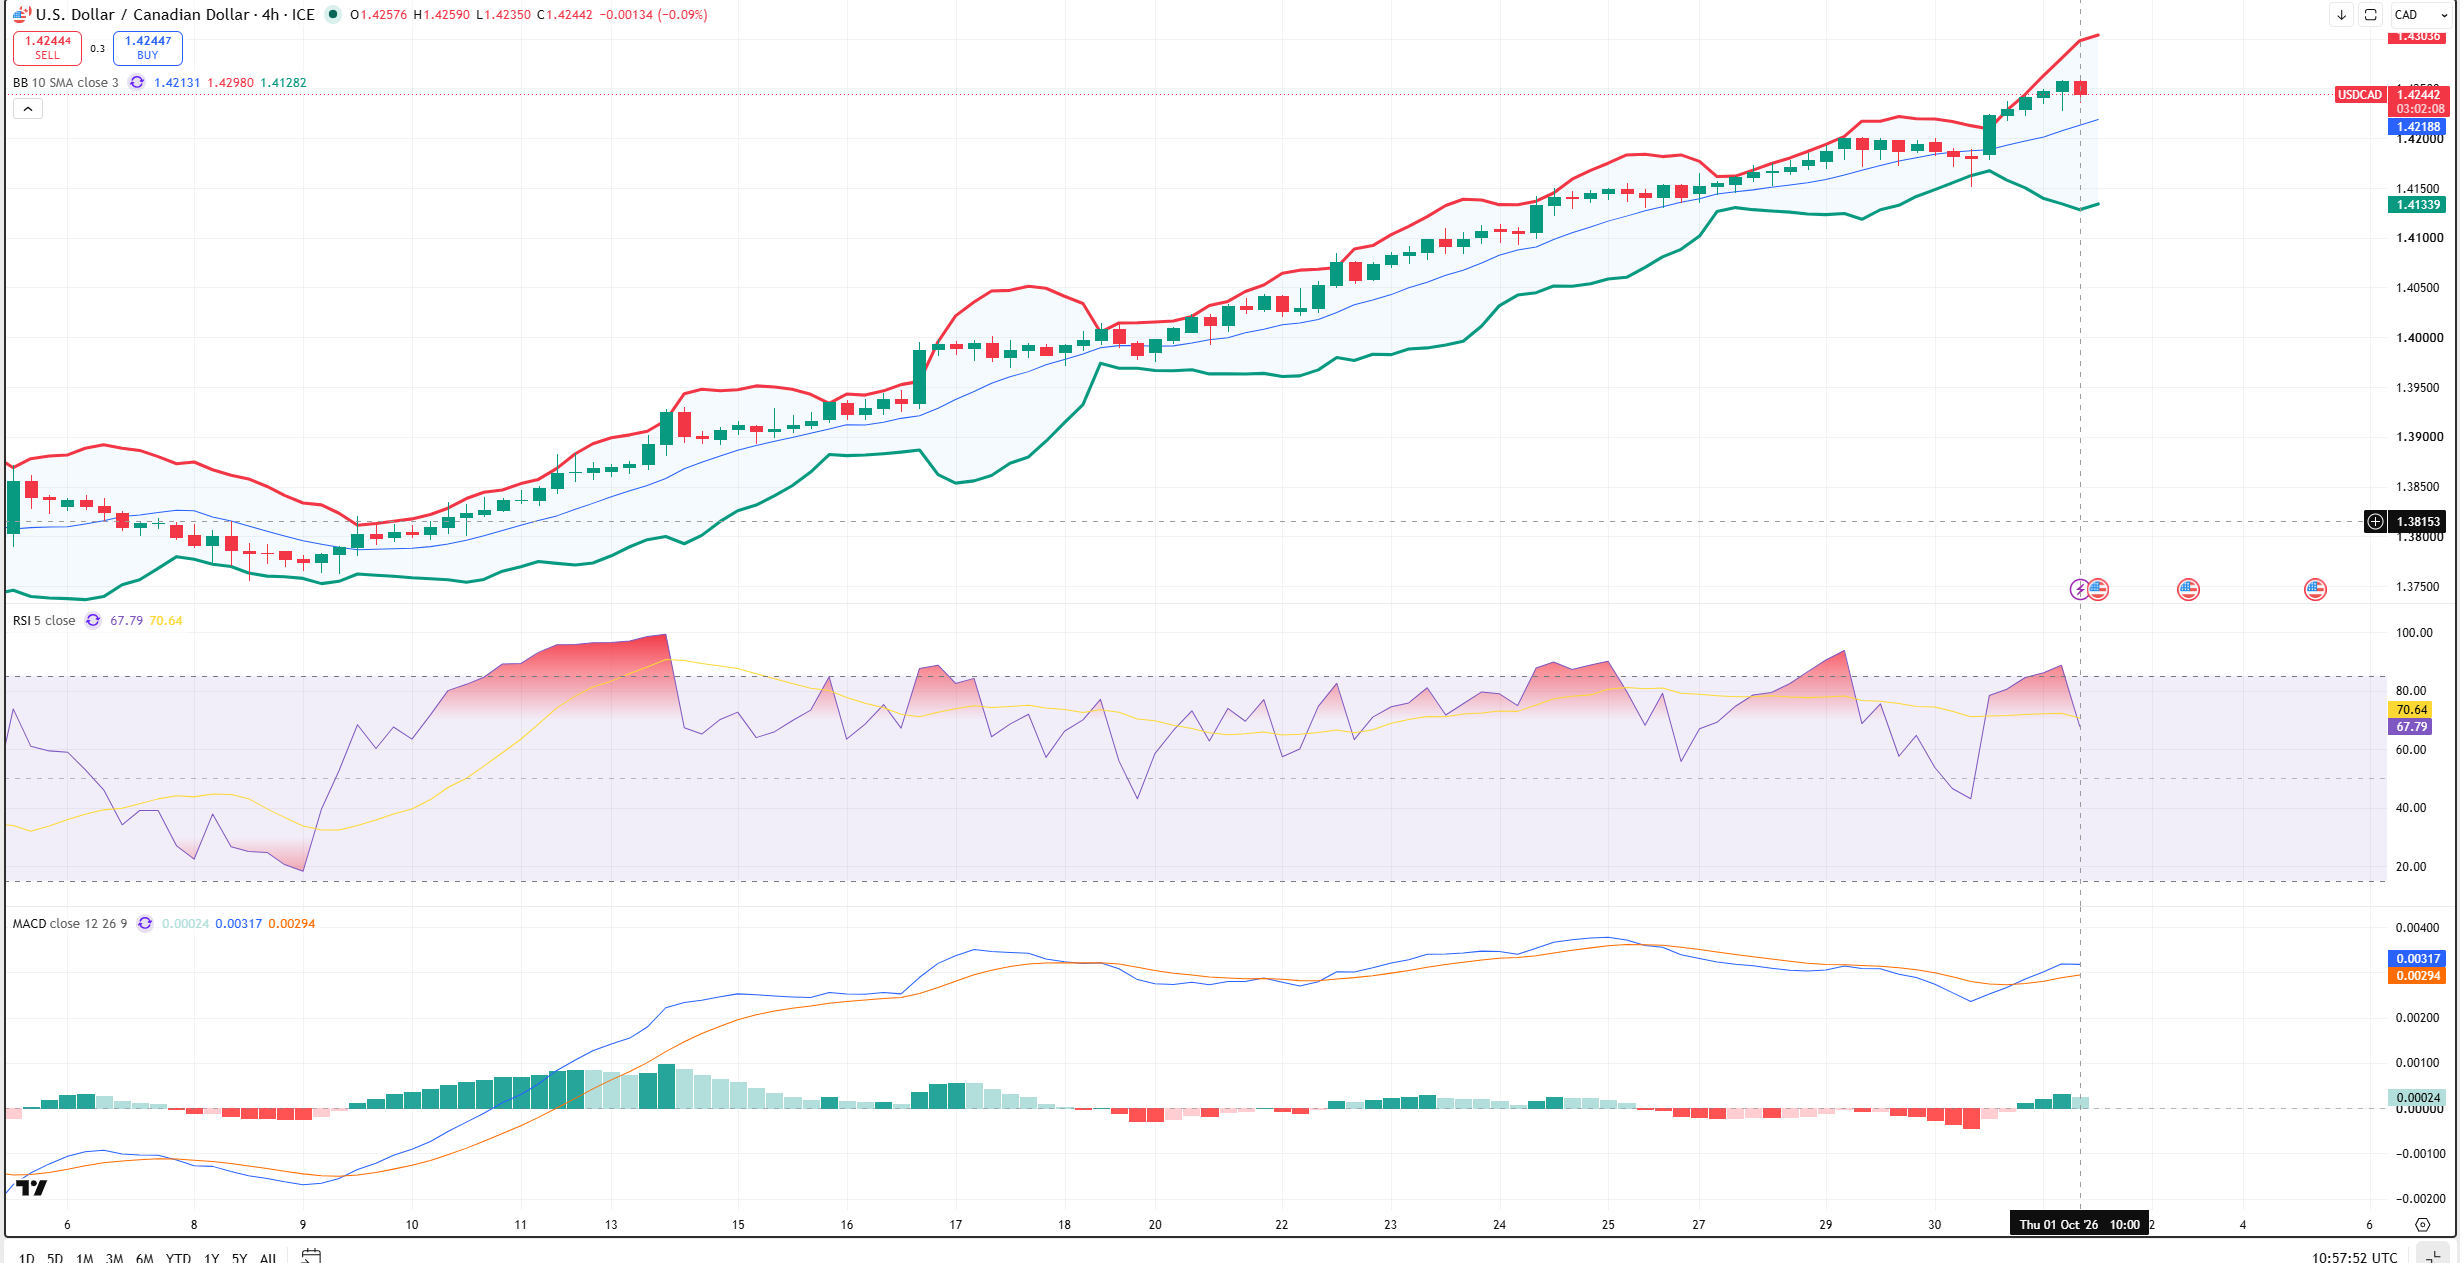
The intraday USDCAD are bullish while trading above 1.4210 and looking to test resistance at the June peak of 1.4260. The uptrend channel from September 9 is intact and bound by 1.4210 on the bottom and 1.4290 on the top.
Longer term, USDCAD has recovered 100% of the losses incurred since June 25 while slicing through every Fibonacci retracement level of the June-August decline. A decisive break above 1.4260 would put the daily upper Bollinger Band at 1.4310 in play, followed by the Covid peak of 1.4660 (March 2020). A failure at 1.4260 risks a double top, and a retest of 1.4150.
For today, support is 1.4210 and 1.4170. Resistance is 1.4260 and 1.4290.
Todays range 1.4210-1.4290
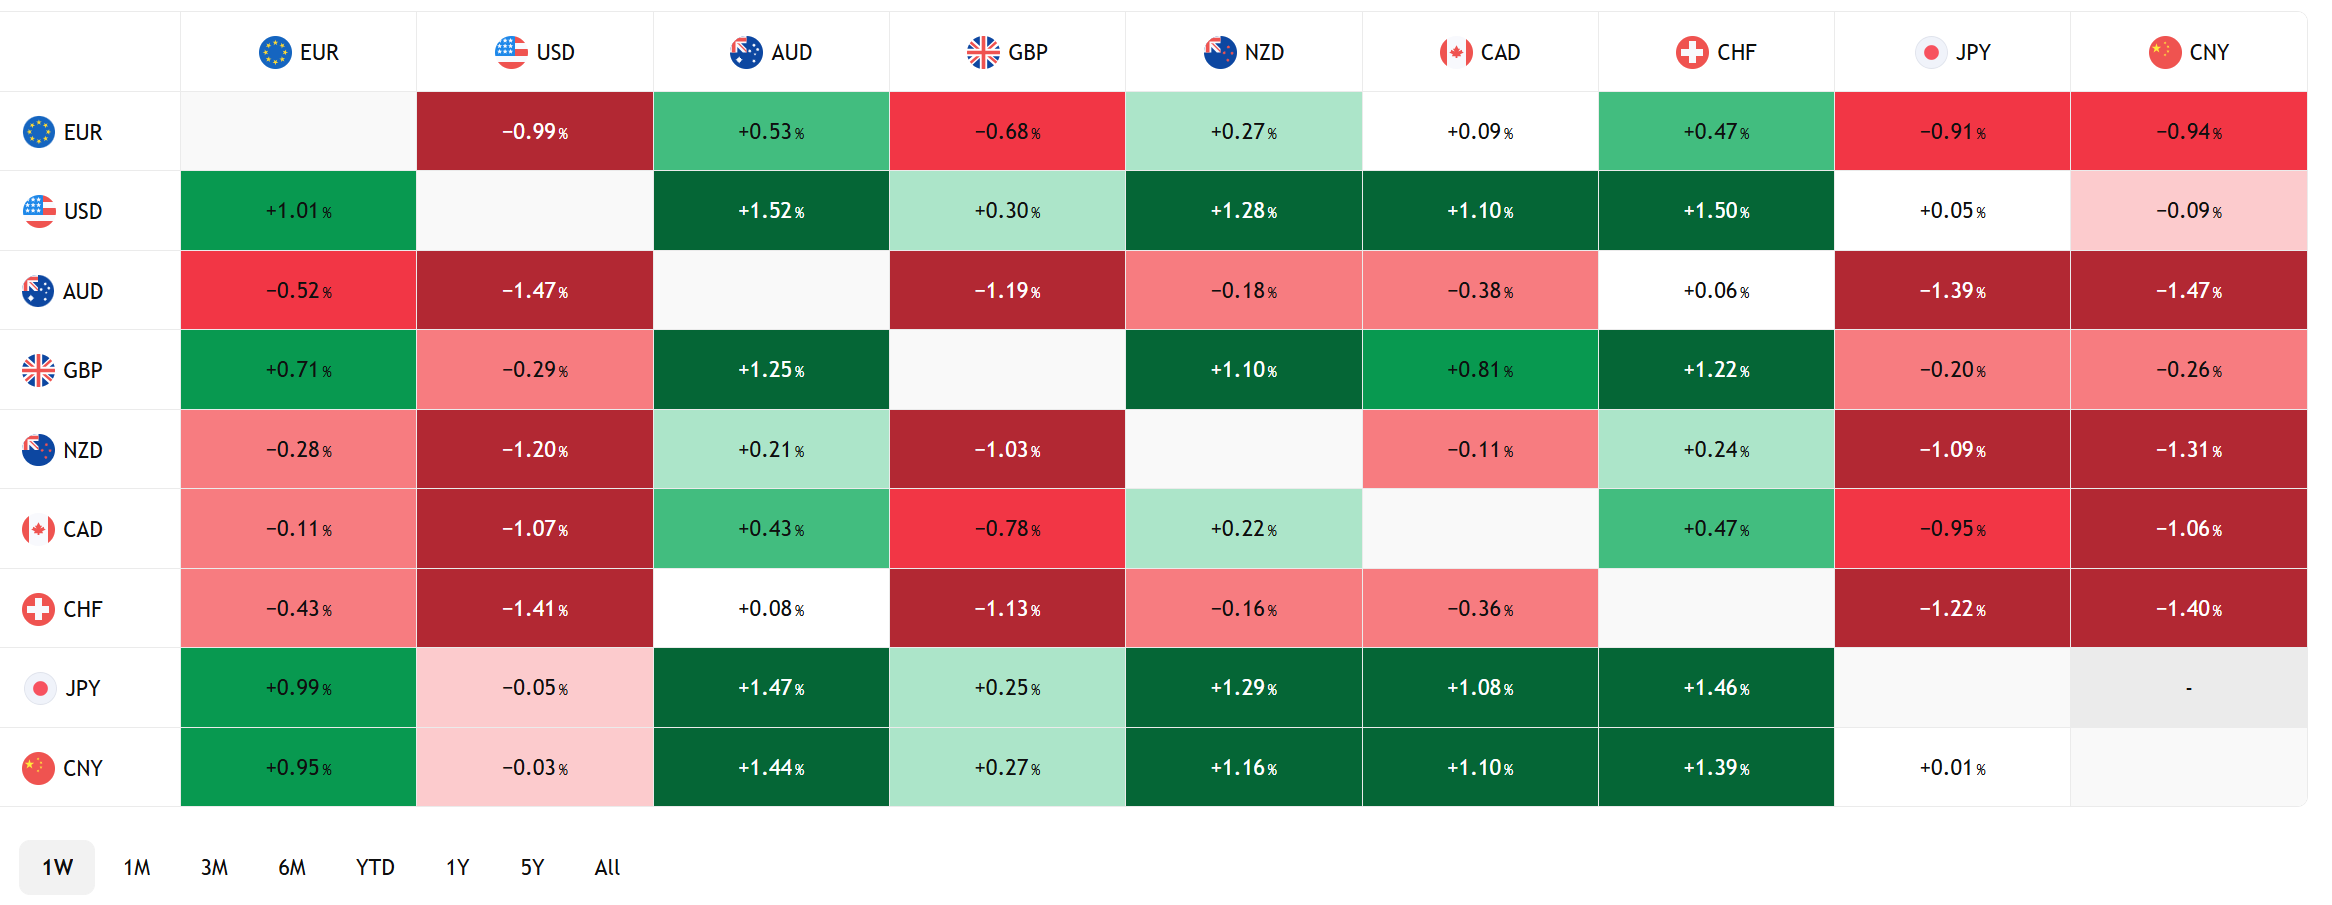
FX Heat Map
FX open high low 6:00 am
The Gums Will Be Flapping
Today, market direction will continue to be dictated by Treasury yields, with the ISM Manufacturing PMI data keeping the resilience of the US economy in focus. Weekly jobless claims rose by 197,000 last week, the same as the week before.
In addition, hawkish Fed rhetoric from Fed Governors Christopher Waller and Lisa Cook and Fed Vice Chairs Philip Jefferson and Michelle Bowman will support higher yields and a higher US dollar.
Taking Stock
Asian equities were mixed, with Chinese markets closed for Golden Week holidays. Japan’s Topix rose 0.57%, while Australia’s ASX 200 lost 1.99%, with every sector in the red.
As of 8:30 am, European bourses are lower but off their worst levels. The UK FTSE 100 is down 0.81%, the French CAC-40 has dropped 0.4% and the German DAX is flat. S&P 500 futures are bucking the trend and have gained 0.32%. The US 10-year Treasury yield is 5.282% after hitting 5.362% overnight, the DXY is 101.76 and gold is $4,183.20.
EURUSD | Range 1.1266-1.1337
EURUSD traded sideways in Asia, then dropped to its session low in early NY due to surging Treasury yields and higher crude prices. Traders have quickly forgotten yesterday’s higher-than-expected inflation numbers from German states, Italy and France while ignoring today’s Eurozone manufacturing PMI, which rose to 52.9 from 52.7 in August. EURUSD technicals are bearish and looking for a break below 1.1250 to target 1.1200.
GBPUSD | Range 1.3193-1.3273
GBPUSD is suffering from the disconnect between the rise in US Treasury yields and a hawkish Fed versus a somewhat dovish Bank of England outlook. PM Andy Burnham is getting a lot of flak after verbalizing what most Britons already knew. He declared that Brexit has done more harm than good. Brexenter, anyone? The GBPUSD technicals are bearish below 1.3320 and looking for a break below 1.3180 to target 1.3100.
USDJPY | Range 157.32-158.45
USDJPY rallied as Treasury yields pushed higher and the BoJ Tankan survey disappointed. Sentiment among large manufacturers improved to 24 from 22 but missed the 25 forecast, while the outlook index also fell short. Combined with yesterday’s surprise drop in industrial production, the report argues for a slower pace of BoJ rate normalization, even though the Summary of Opinions from the September meeting leaned hawkish. Intervention risk will act as a drag on further gains.
AUDUSD | Range 0.6931-0.6956
AUDUSD went nowhere after Australia’s trade surplus shrank to A$0.5 billion, well short of the A$2.0 billion forecast. Yesterday’s mixed inflation data continued to underscore the RBA’s sticky inflation dilemma.
USDMXN | Range 18.0605-18.2790
USDMXN is on a US Treasury yield-fuelled tear, which is rapidly eroding Mexico’s yield advantage over America. USDMXN has recouped all of its losses for 2026 and is currently up 1.03% YTD. USDMXN is targeting 18.7600 if prices stay above 18.1000.
CHINA
Chinese markets are closed for Golden Week Oct. 1-Oct. 7.
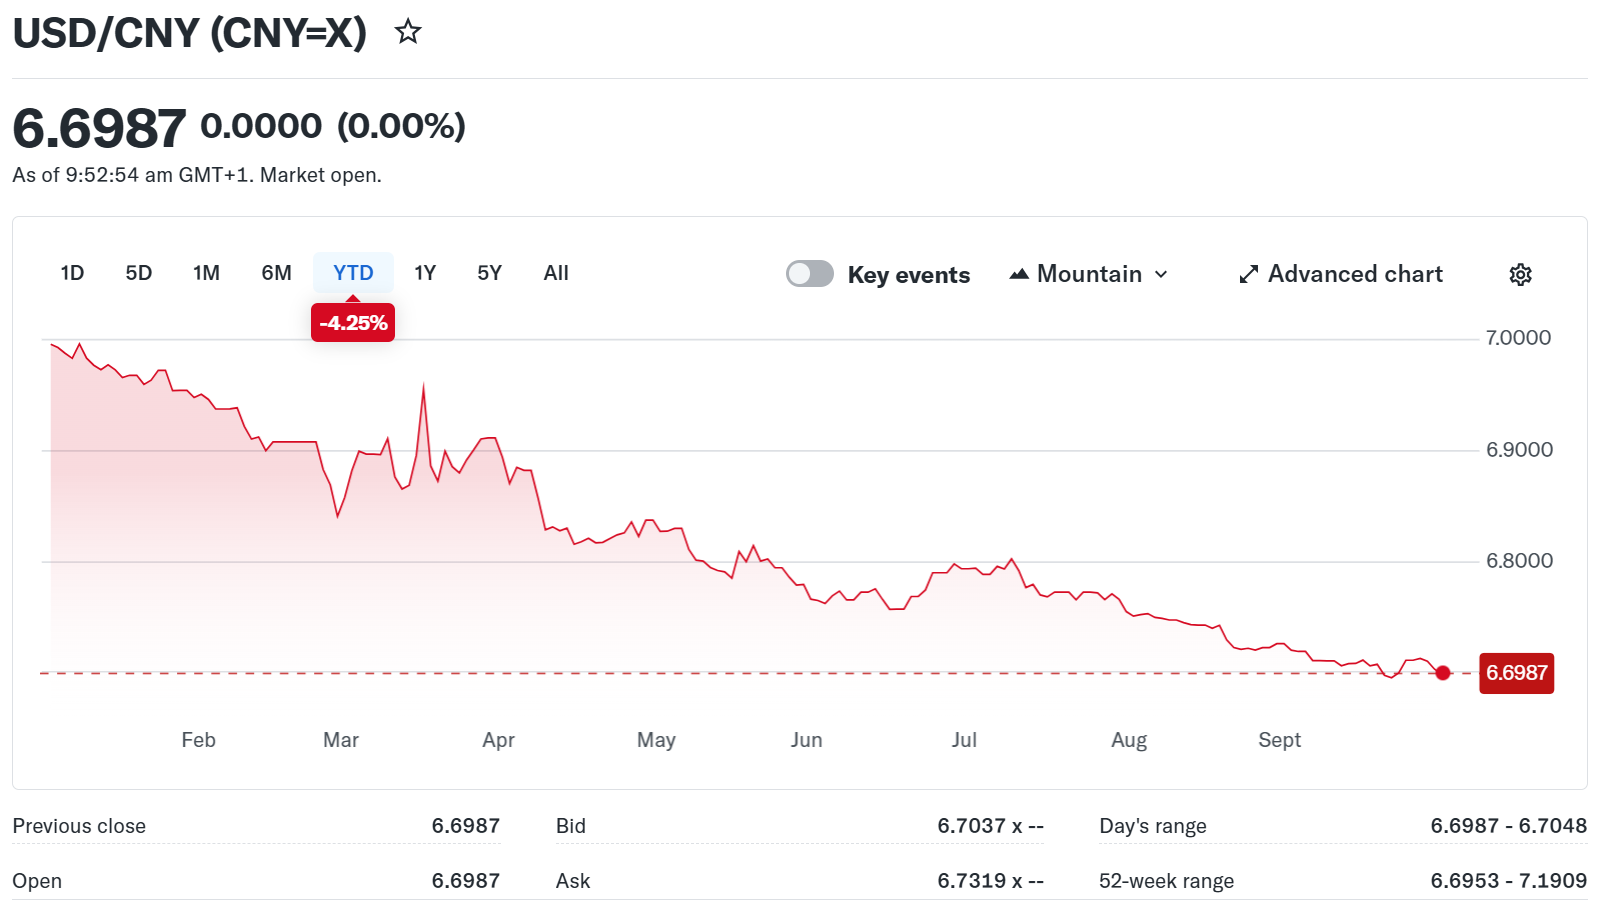
- PBoC Fix: 6.7351 (September 30)
- Shanghai Shenzhen CSI 300 Closed
From September 30: Chinese RatingDog Manufacturing PMI (Sep) 52.1 vs. Exp. 51.6 (Prev. 51.5), Services PMI (Sep) 51.6 vs. Exp. 51.1 (Prev. 51.4), Composite PMI (Sep) 52.4 (Prev. 52.1).
Chinese NBS Manufacturing PMI (Sep) 50.1 vs. Exp. 50.1 (Prev. 49.8). NBS Non-Manufacturing PMI (Sep) 50.2 vs. Exp. 49.3 (Prev. 49.0)
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview