USDCAD open (6:00 am): 1.4273 overnight range 1.4241-1.4285, close 1.4261
USDCAD is trading choppily but has eased from the overnight high on the heels of 10-year Treasury yields that slipped to 5.27% from 5.33% overnight.
USDCAD continues to be underpinned by the lack of progress in Canada and US trade talks. Yesterday, Trump said he is in no rush to resume them.
Sliding oil prices are not helping. WTI bounced around in a $87.12-$90.04 rand and it is just above the low in NY trading. Reuters reported that Middle East crude exports topped pre-war levels in the last week of September and are over 81% of the pre-war level for the entire month.
Canada posted a $4.29 billion trade surplus in August. Some of the August strength may reflect tariff front-running, with exporters and importers adjusting shipments before the new tariffs took effect,
Alos on tap, Ivey PMI (forecast 65.2, prior 64.3).
The US the goods and services deficit was $105.6 billion in August, up $12.7 billion from $92.8 billion in July, revised
USDCAD Technical Outlook
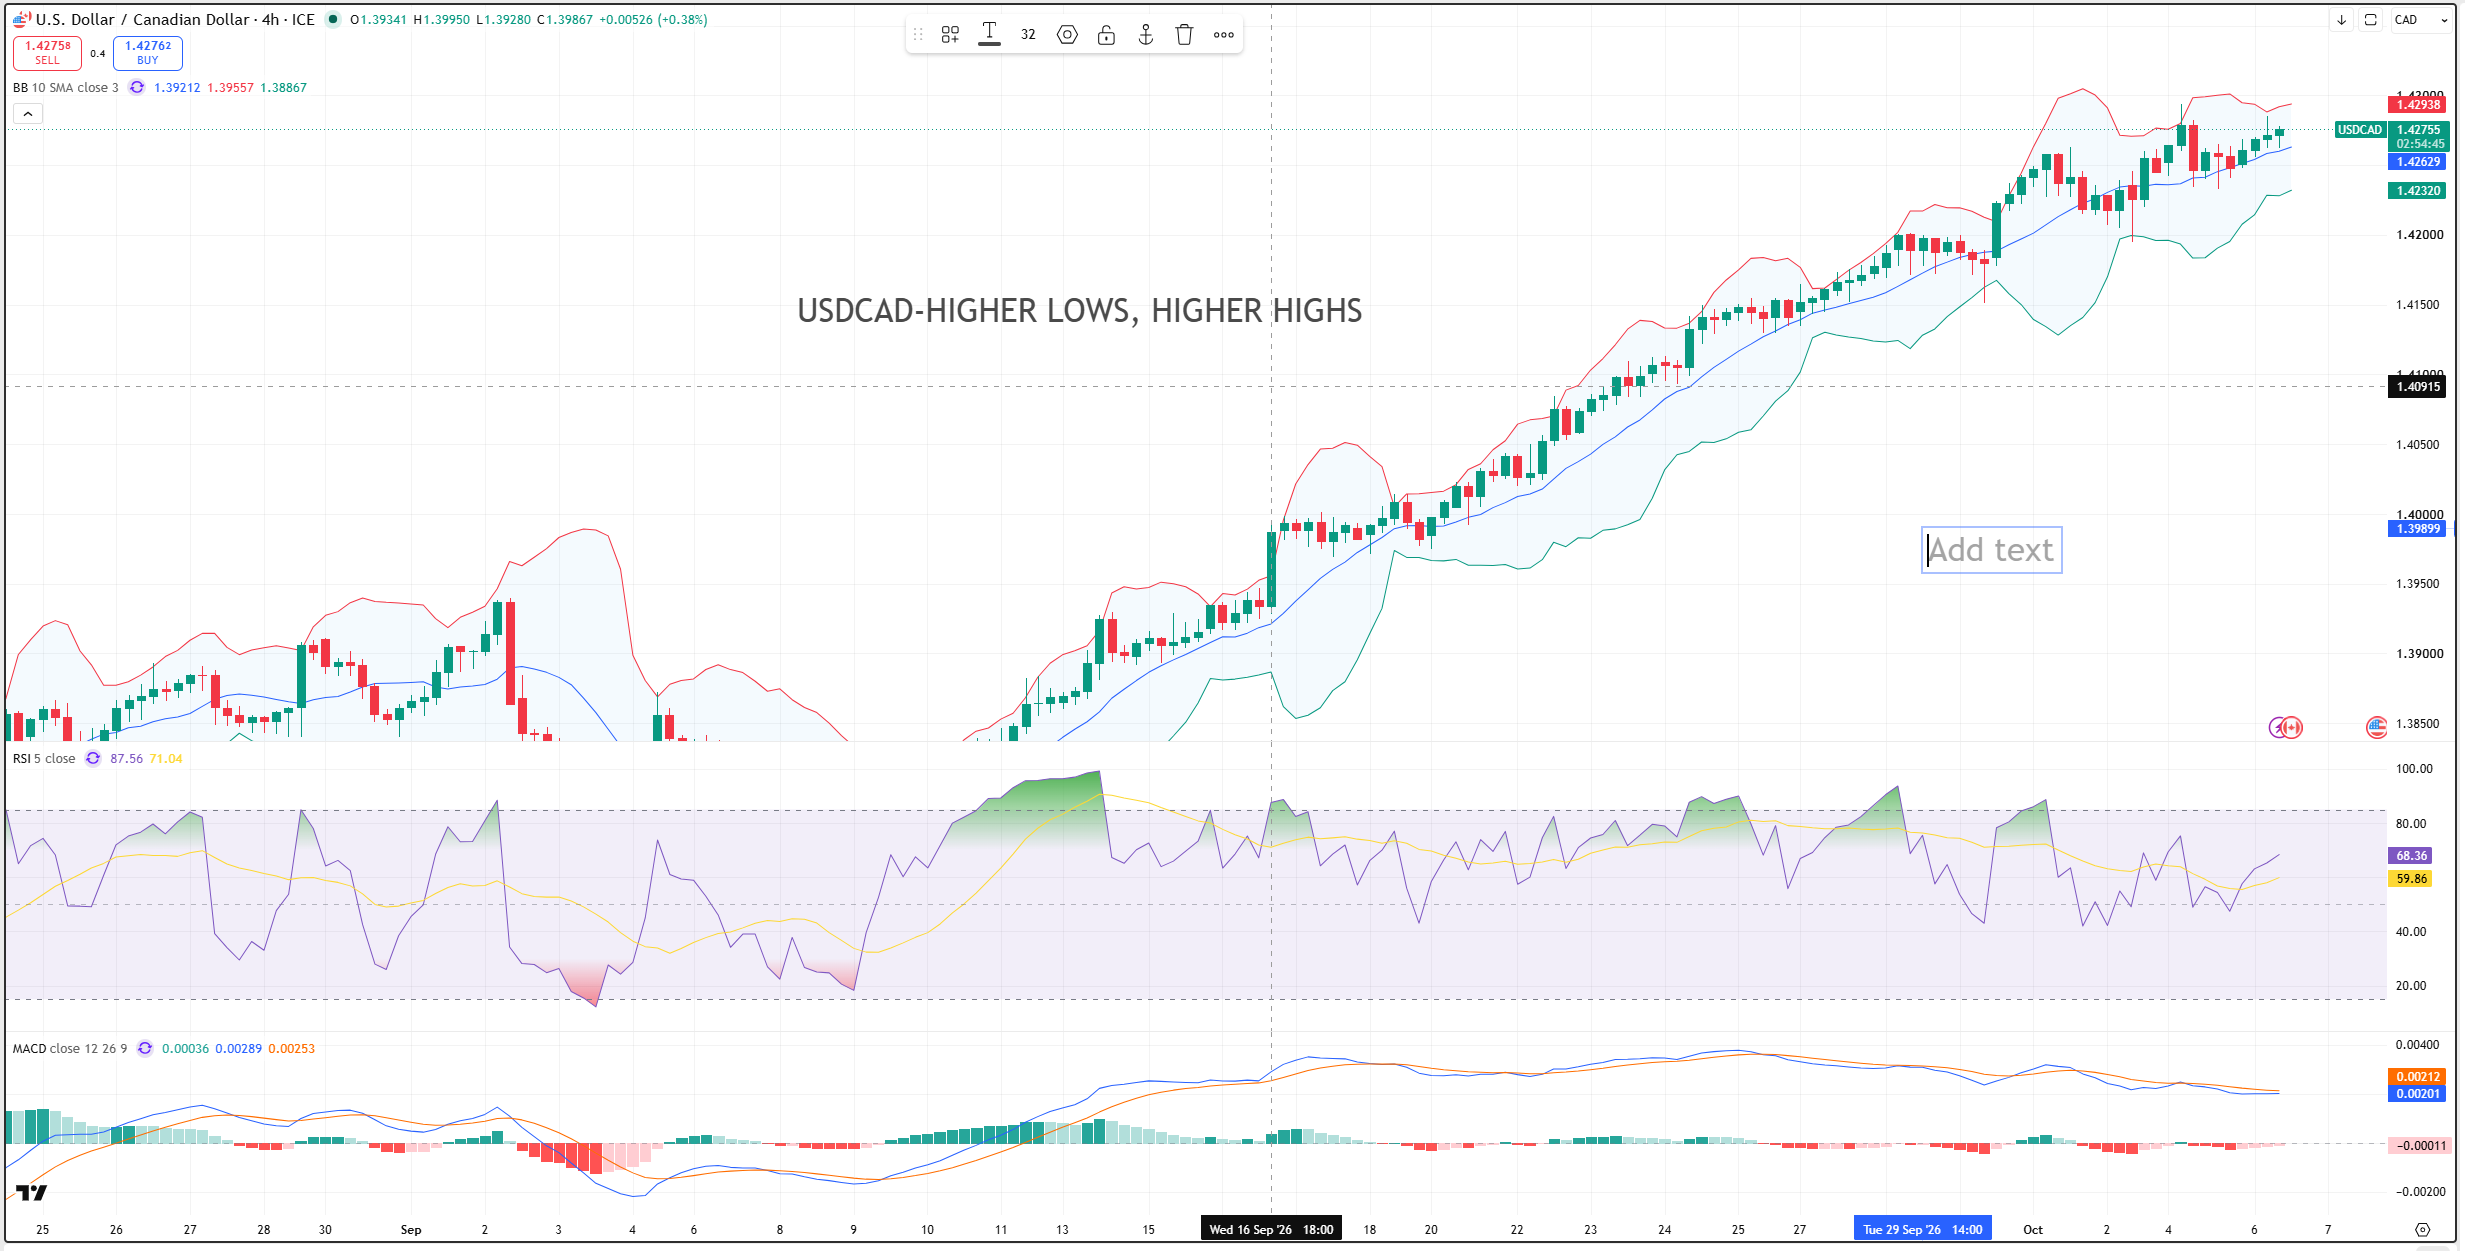
The intraday USDCAD are bullish while trading above 1.4230 and looking to break yesterday’s high at 1.4297 and extend gains to 1. 4250.. The uptrend channel from September 9 is intact and bound by 1.4240 on the bottom and 1.4340 on the top.
Longer term, USDCAD has extended its rally to roughly 525 pips from the September 9 low of 1.3760 and is now trading above the 1.4250 horizontal resistance that capped every monthly rally this year. The daily RSI has bounced to 93 from 84, so the market is even more stretched than yesterday. A decisive break above 1.4300 would put a tight resistance cluster in play, with the daily upper Bollinger Band at 1.4364 sitting just below the 78.6% Fibonacci level at 1.4372, followed by Trump’s first tariff order peak at 1.4788. A second failure at 1.4294 risks a double top and a pullback to 1.4184.
For today, support is 1.4240 and 1.4190. Resistance is 1.4295 and 1.4320.
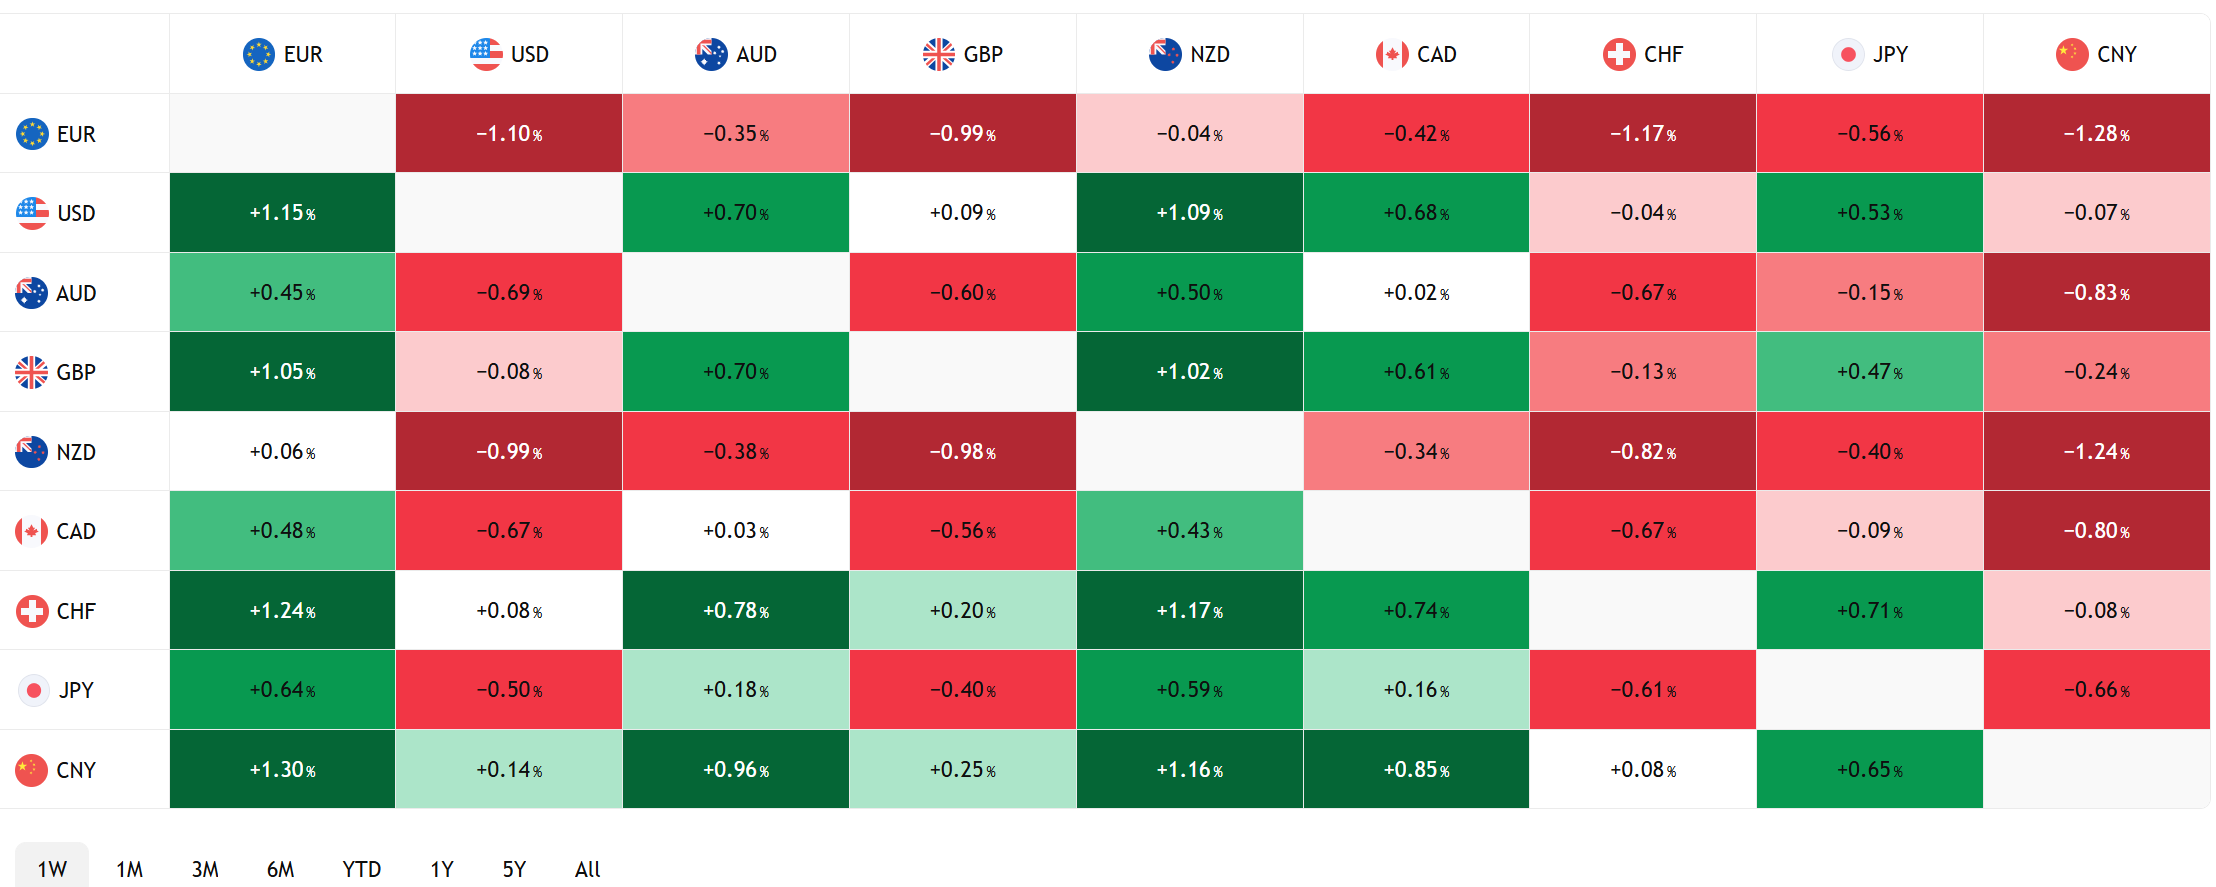
FX Heat Map
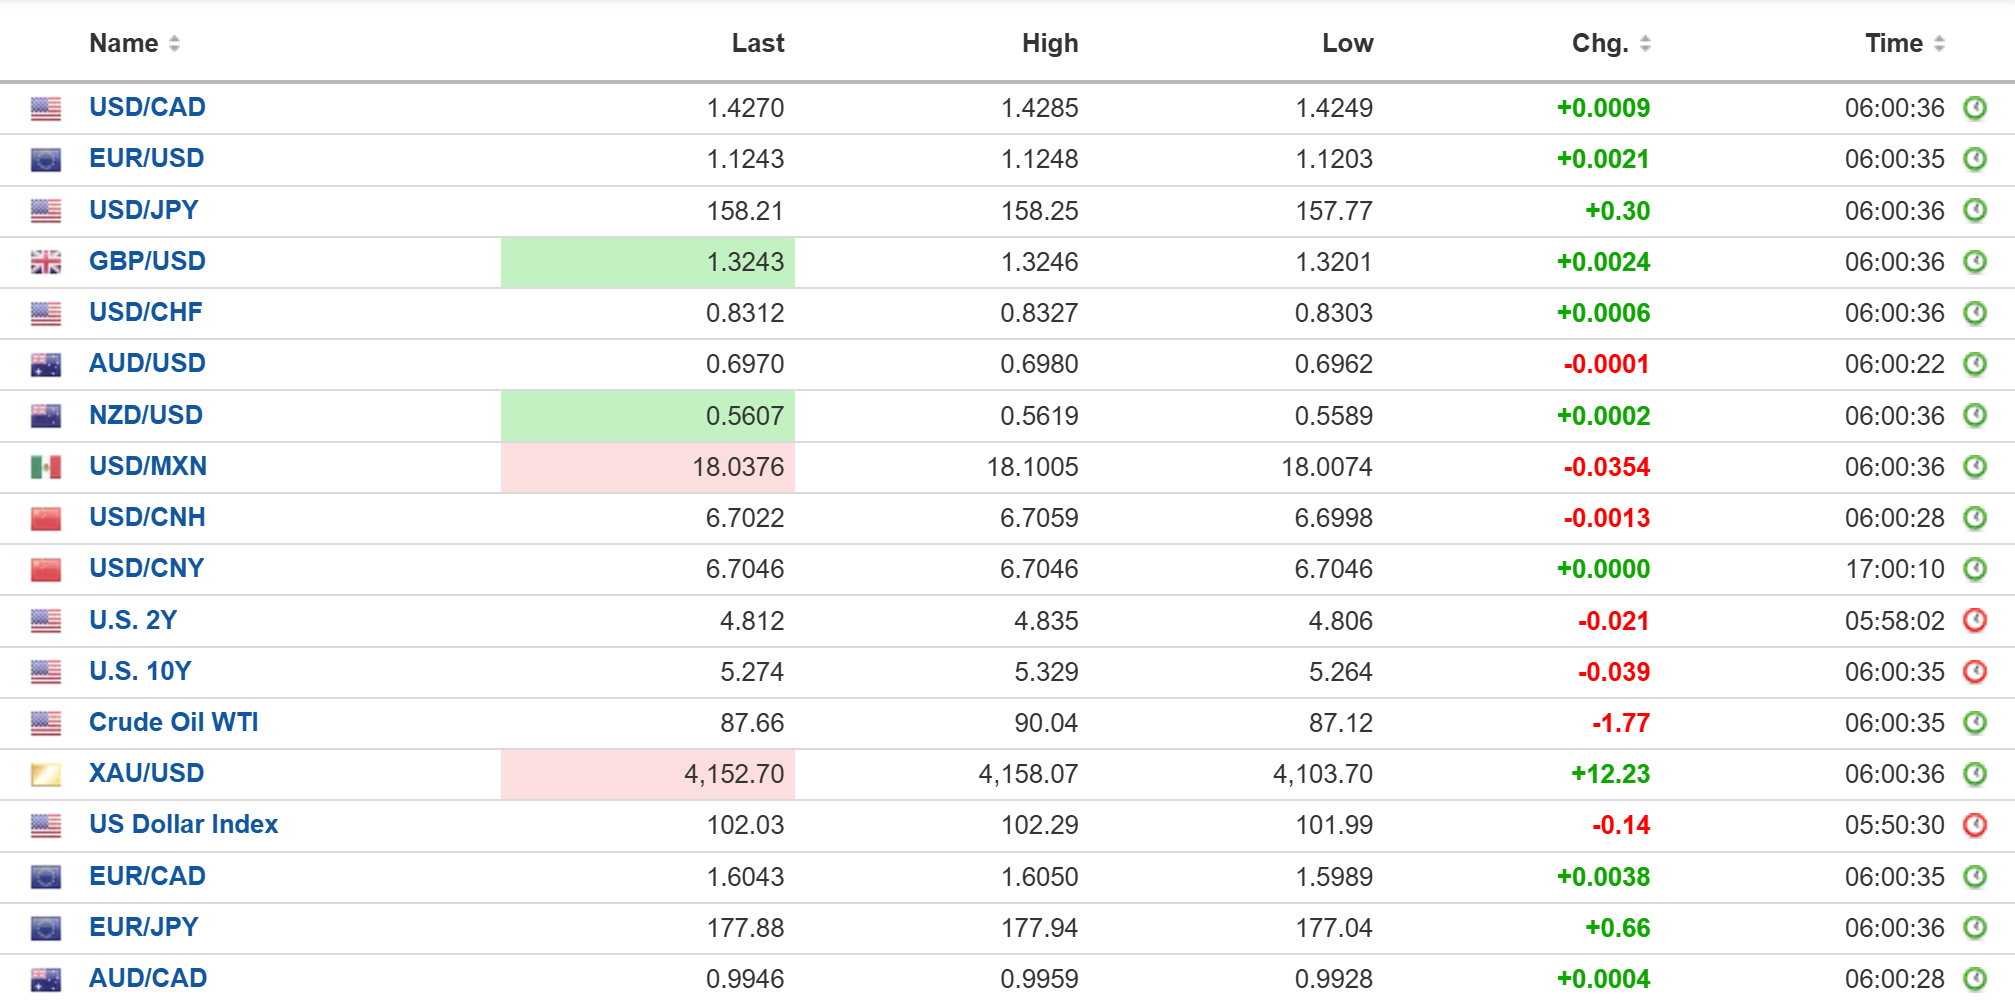
FX open high low 6:00 am
Greenback Marches Higher
The US 10-year Treasury yield climbed to 5.329% overnight as it continued to dance with levels last seen in 2002 due to a global bond selloff because of increasing fiscal concerns and sticky inflation. Prices retreaded sharply in Europe and NY.
France is in the spotlight. It’s 10-year bond (Obligations Assimilables du Trésor or OAT) is consolidating near multi-year highs in the 4.48% region, about 140 bps higher than the comparable German Bund.
The result is that the US dollar remains underpinned against EUR and GBP, particularly because a spate of recent US data reflects the resilience of the economy. Yesterday’s ISM services index, although at tad lower (actual 54.9) from the August result (55.4) is still in expansion territory.
Taking Stock
Asian equities finished in the green. Hong Kong’s Hang Seng rose 1.00% to 24,280.56, Japan’s Topix climbed 0.92% to 4,183.56 and Australia’s ASX 200 rose 0.57% to 8,735.68.
As of 6:00 am PT, the German DAX has gained 0.47% to 25,372.17, the UK FTSE 100 is up 0.17% to 10,515.28, and the French CAC 40 has risen 0.22% to 7,851.29. S&P 500 futures have gained 0.44%, the US 10-year Treasury yield is 5.27%, the DXY is down to 101.86 from 102.02 at the NY open, and gold is $4,169.76.
EURUSD | Range 1.1203-1.1277
French political and budget drama drove EURUSD to its session low in early Asian trading before prices clawed back most of the losses into the NY open. ECB Chief Economist Philip Lane sounded rather dovish when he said he has not seen higher energy costs “generating second-round inflation,” German and Eurozone data was soft. German factory orders fell 10.6% compared to July’s increase of 3.2% while Eurozone Retail Sales rose 0.8% y/y compared to the forecast for a 1.0% gain.
GBPUSD | Range 1.3201-1.3283
Sterling is nudging towards the top of its 1.3180-1.3265 band that has contained price action since early in October. Yesterday’s better than expected Services PMI data and today’s Construction PMI result (actual 46.1 vs, forecast 45.4, August 44.3) are giving cable a bit of support. The data has also increased the odds for a 25 bp BoE rate hike on November 5 to over 60%. Those odds were supported by hawkish comments from BoE policymaker Catherine Mann who warned that inflation was becoming deeply imbedded.
USDJPY | Range 157.77-158.25
USDJPY traded choppily with the peak seen after the 10-year JGB auction, where the coupon was raised to 3.1%, the highest in about three decades. BoJ Governor Ueda reiterated that the economy is recovering moderately and emphasized that anchoring underlying inflation near the 2% target is increasingly vital. Nevertheless, the market does not expect a BoJ rate hike at the end of the month.
AUDUSD | Range 0.6962-0.6986
The Aussie was steady, but it had a modestly bullish bias inside a very narrow band due to RBA rate hike speculation. Policymakers continue to fret about sticky inflation that is being driven by the service sector and because of labour market tightness. Meanwhile the Consumer sentiment survey showed the index dropped by 4.7% to 80.4% in October, the worst level since early April.
USDMXN | Range 17.9106-18.1005
USDMXN is consolidating its recent gains after prices retreated from the October 1 peak in the 18.4400 area when the odds of an October Fed rate hike dropped sharply from around 60% to just 20% today. Mexican consumer confidence improved to 45.2 from 43.3 in July.
CHINA
Chinese markets are closed for Golden Week Oct. 1-Oct. 7.
- PBoC Fix: Market closed
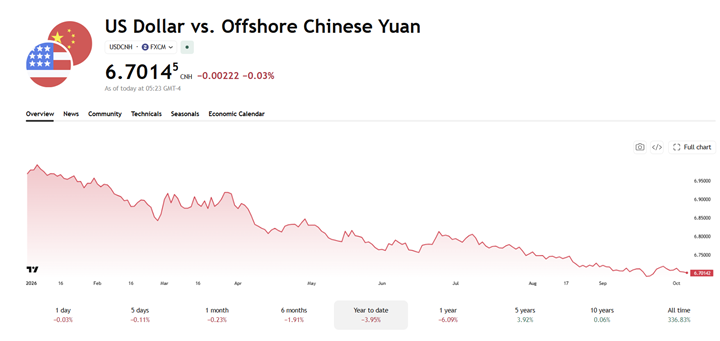
- USDCNH: 6.7054 (-0.0078)
- Shanghai Shenzhen CSI 300 Closed (last 4,357.62 on September 30)
Chart: Offshore yuan USDCNH
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview