October 21, 2026
USDCAD open (6:00 am): 1.4053, overnight range 1.4038-1.4068 close 1.4061
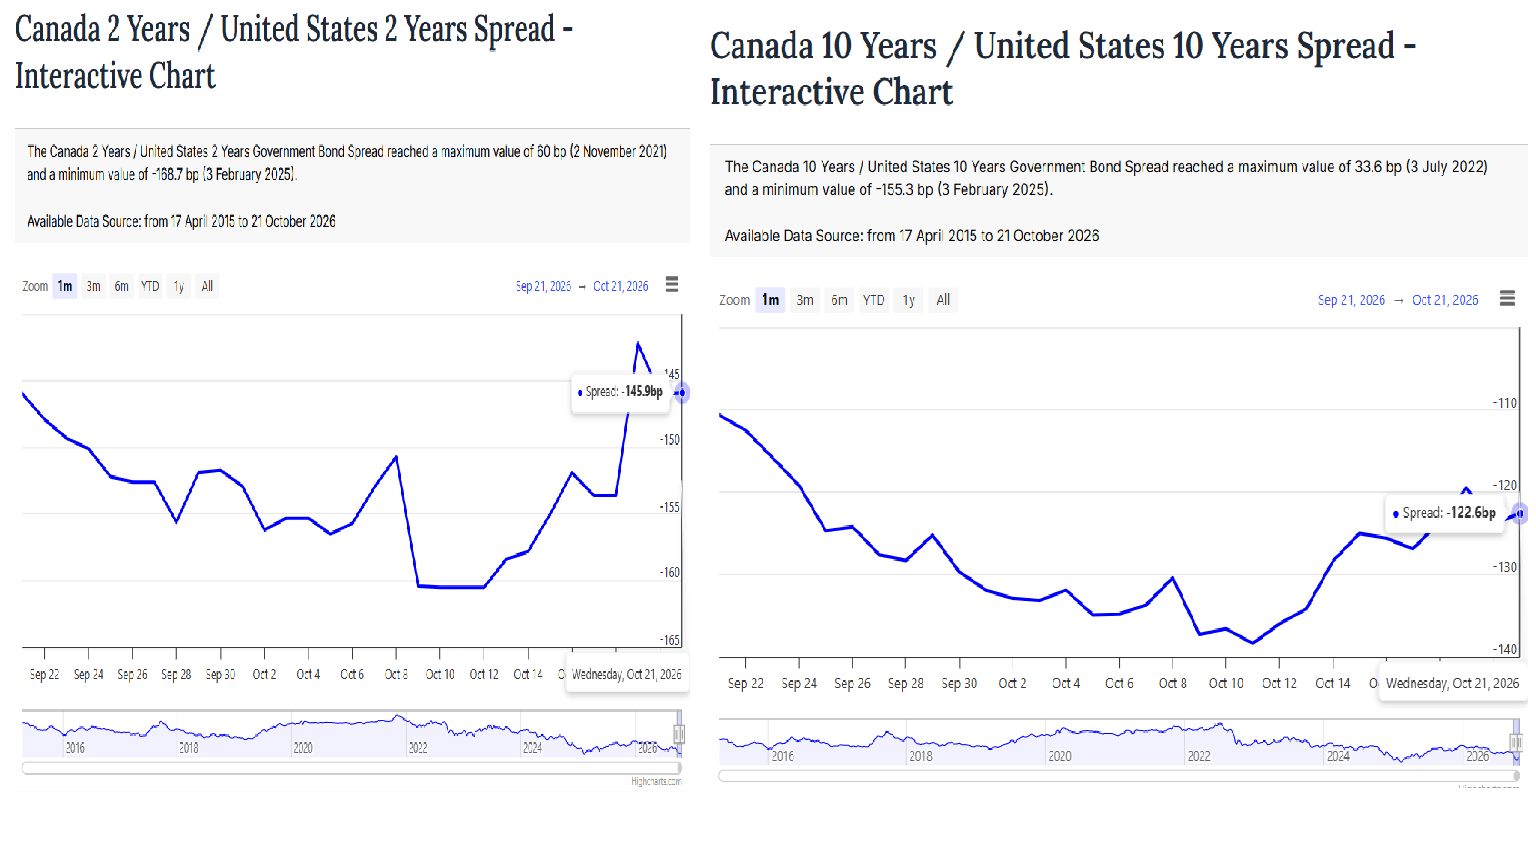
USDCAD is consolidating its losses since peaking at 1.4300 on October 14 and is trading at levels last seen a month ago. The losses are almost entirely due to the sharply narrowing CAD/US 10-year and 2-Year interest rate spreads. The 10-year narrowed to -122.6 today, from 125.6 on Friday and -138.4 on October 12. The 2-year spread is 145.9 today, compared to -153.6 on Friday and -160.5 on October 12. Hawkish comments by BoC Governor Tiff Macklem have led to many Canadian economists to forecast a 25 bp rate hike on Wednesday October 28.
If they do, it is a dumb move and it flies in the face of the Bank’s insistence they monetary policy is data dependent. And the data, BoC CPI-trim and CPI-median, are sitting below the mid-point of the Bank’s 1-3% inflation target.
WTI is trading at the top of its $97.93-$100.38 range due to a lack of progress in US/Iran ceasefire talks. Iran’s foreign minister says the Strait of Hormuz stays shut until a deal is done, and the IRGC threatened to cut the undersea internet cables. API reported that US crude stocks fell by 4.93 million barrels in the week ending October 16.
The US and Canadian economic calendars are empty.
USDCAD Technical Outlook
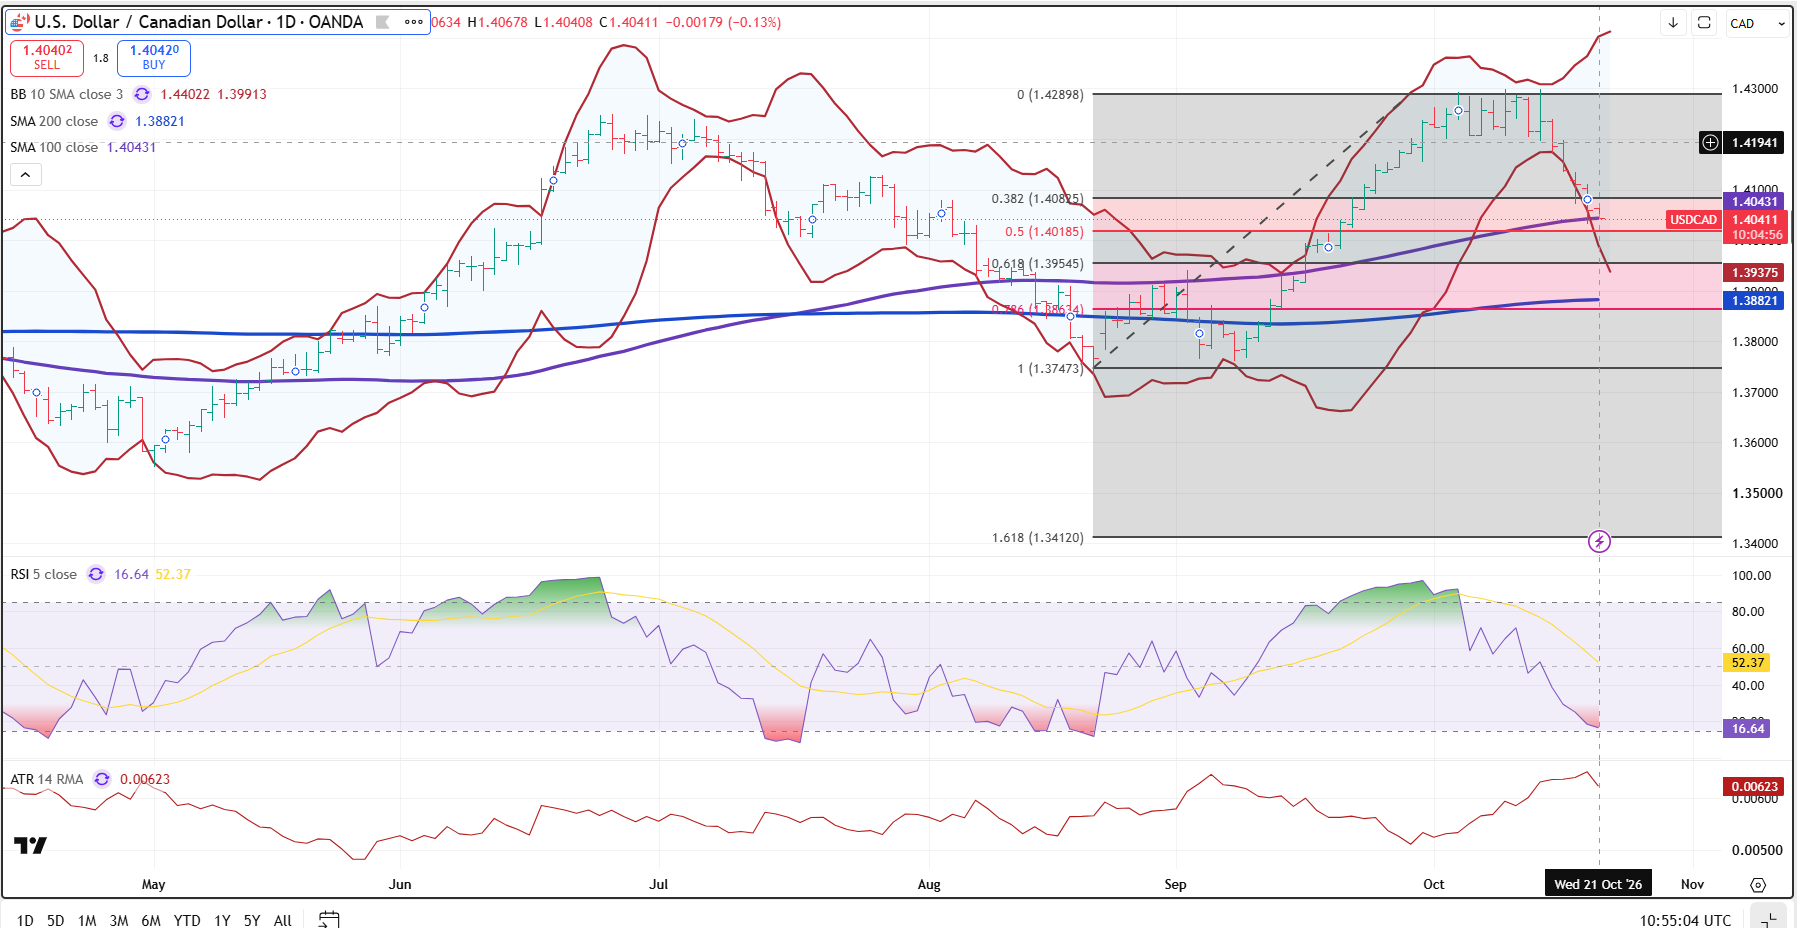
The intraday USDCAD are bearish below 1.4065, but the selling is losing steam. Prices have spent the past 24 hours drifting sideways in a narrow 1.4036-1.4070 band, and the 4-hour MACD has flattened out right on top of its signal line, a sign that downside momentum is fading. The 4-hour RSI is pinned at 17, still deeply oversold, so a corrective bounce is possible. A break below 1.4030 targets the 1.3990-1.4010 area.
Longer term, USDCAD is dancing with the 100 day moving average in the 1.4043 area and stretched momentum indicators suggest USDCAD will consolidate its recent losses in a 1.4020-1.4120 range before attempting a test of the 61.8% retracement level of the August-October range at 1.3955.
For today, support is 1.4030 and 1.4000. Resistance is 1.4070 and 1.4110.
Todays Range 1.4010-1.4090.
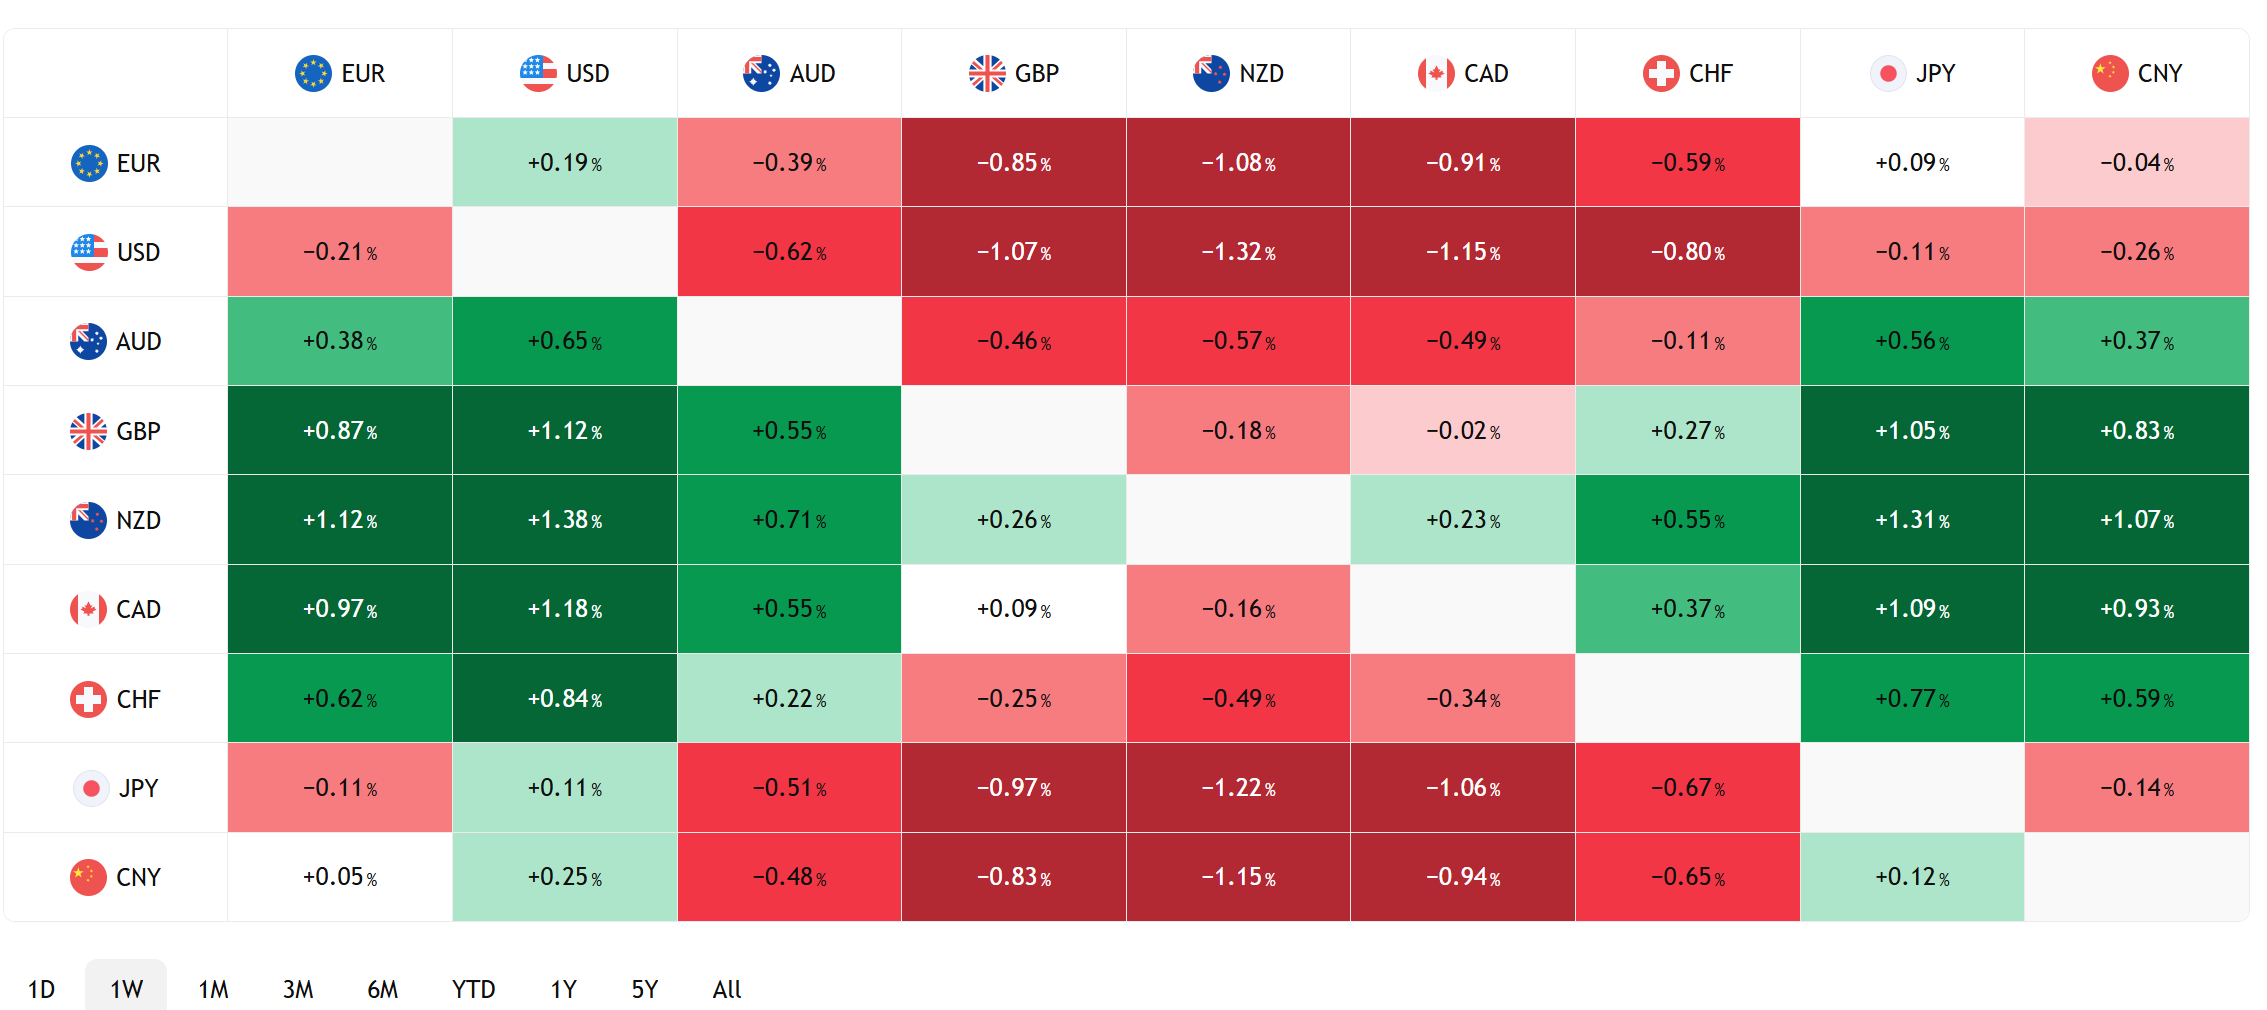
FX Heat Map
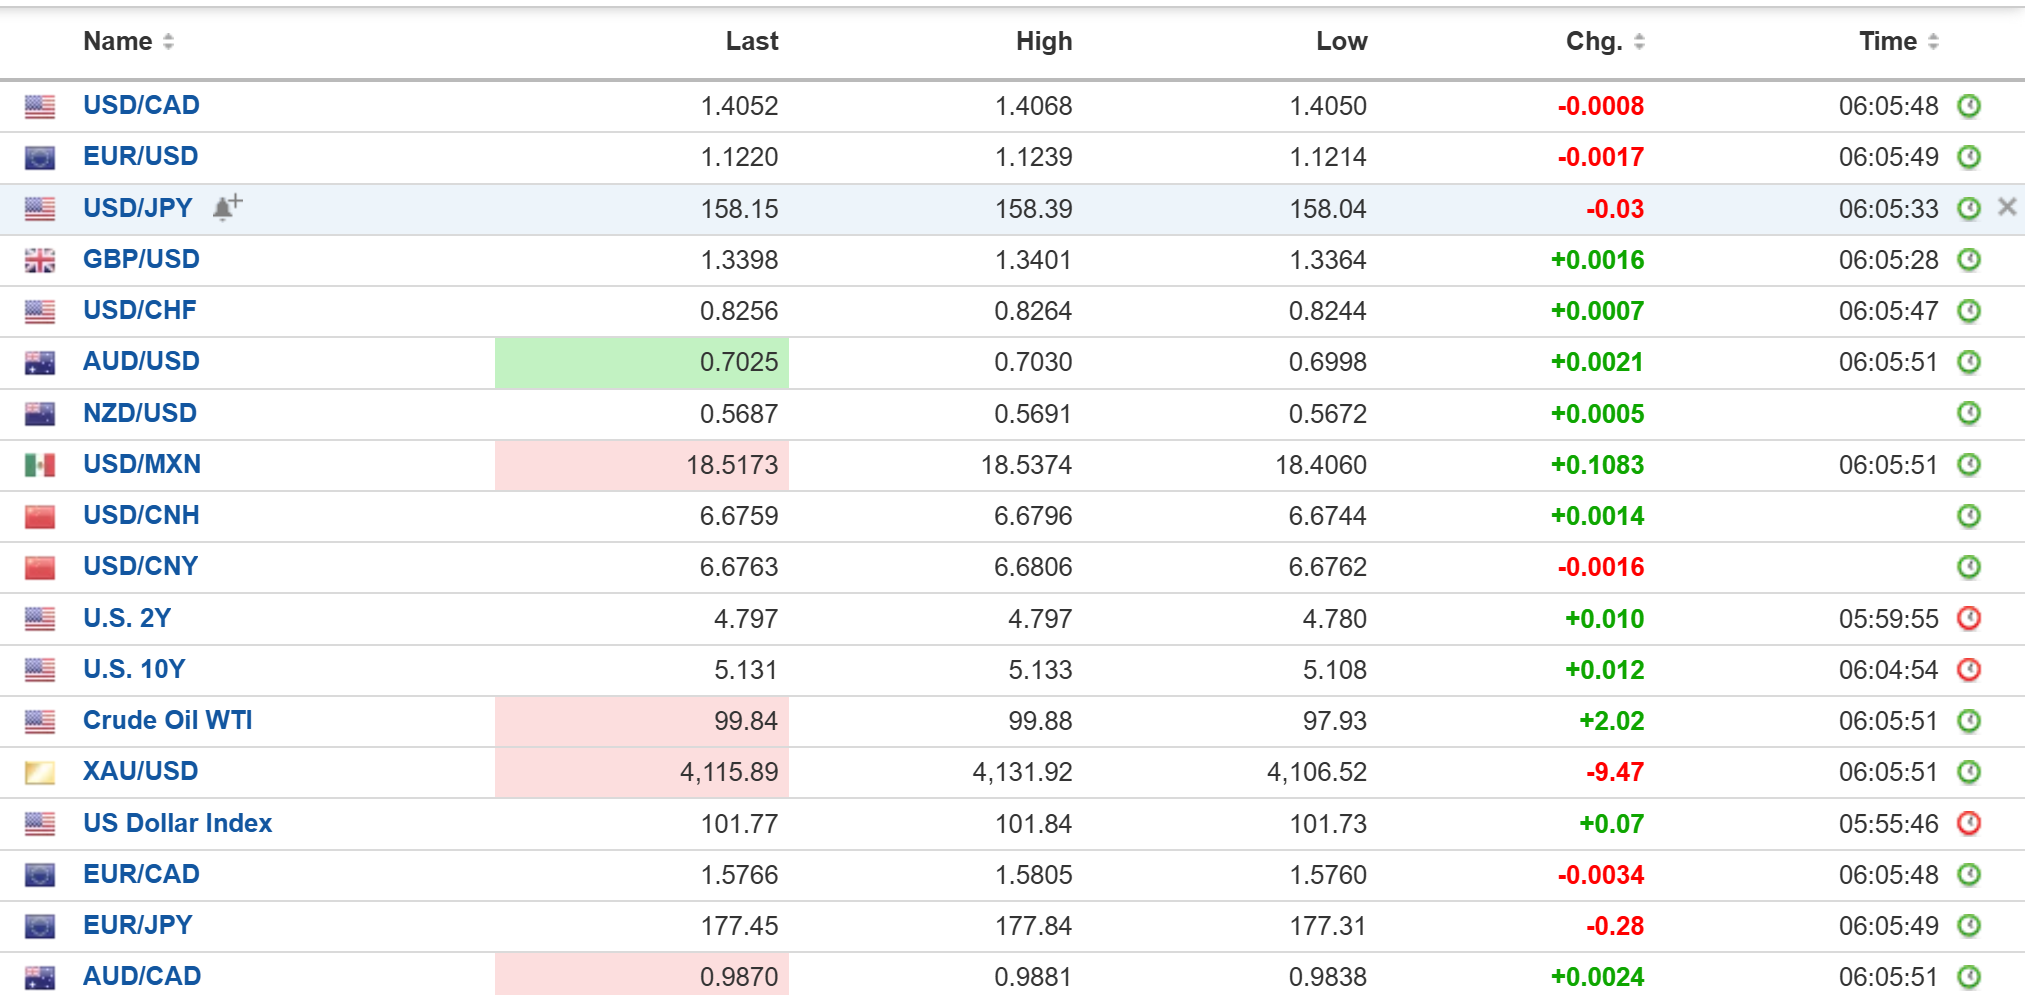
FX open high low 6:00 am
Q3 Earnings Calendar is Busy
The Fed is in its quiet period ahead of October 27-28 FOMC, and the US calendar is about as thin as they come.
Today’s excitement will be driven by Tesla and Meta Q3 earnings. SpaceX beat handily on Q3, with revenue around $14.6bn, and the stock is up 10.5% premarket after Musk called a Tesla tie-up a good idea, if far from certain.
Markets have largely written off a move by the Fed to raise rates in October, but a December hike is nearly fully priced in following last week’s 3.7% CPI print.
The dollar index is consolidating its losses after sliding from 102.93 on October 14, to 101.73 today. The market’s reassessment of Fed rate hike odds for October and the drift lower in oil prices fuelled the losses.
Taking Stock
Asia equity indexes closed on a mixed note. Japan’s Topix rose 0.86% and Australia’s ASX 200 gained 0.16%. Hong Kong’s Hang Seng was the laggard, falling 0.90%.
As of 7:00 am, European bourses are higher, led by a 0.72% gain in the German Dax. The French CAC-40 is up 0.58% while the UK FTSE 100 has gained 0.11%. S&P 500 futures are up 0.17%, the US 10-year yield is 5.125%, the DXY is 101.74 and gold (XAUUSD) is $4,126.11.
EURUSD | Range 1.1214-1.1239
The euro is trading defensively, mainly due to French political issues. The French-German 10-year spread is hovering near 157 bp, close to its widest since the 2012 debt crisis. ECB Chief Economist Philip Lane mused about global euro use, arguing that greater international use of the euro would enhance the ECB’s ability to deliver on its inflation mandate by extending the global impact of euro area monetary policy. Traders ignored his remarks.
GBPUSD | Range 1.3364-1.3401
GBPUSD is grinding higher following the release of hotter-than-expected inflation data (headline CPI 3.5% y/y vs forecast 3.4% and August 3.1%). Core CPI rose to 2.8% (forecast 2.7%, August 2.6%). PPI data was steady to higher and the Retail Price Index rose 3.9% y/y compared to 3.4% y/y in August. A November BoE hike was largely in the price before the numbers, but the data pretty much guarantees one.
AUDUSD | Range 0.6998-0.7031
AUDUSD rallied to a three-week high after RBA Deputy Governor Hauser warned the inflation outlook has deteriorated beyond the Bank’s forecasts. That was enough for Goldman to pencil in a 25 bp hike to 4.85% on November 3, which would be the fifth of 2026.
USDMXN | Range 18.4060-18.5374
USDMXN continued to rally overnight as carry-trade positions get unwound due to a narrowing Fed-Banxico rate gap. The stalled US/Mexico trade talks are not helping sentiment. Mexico releases August retail sales, which are expected to rise to 2.0% y/y after 1.8%, but the news will be ignored.
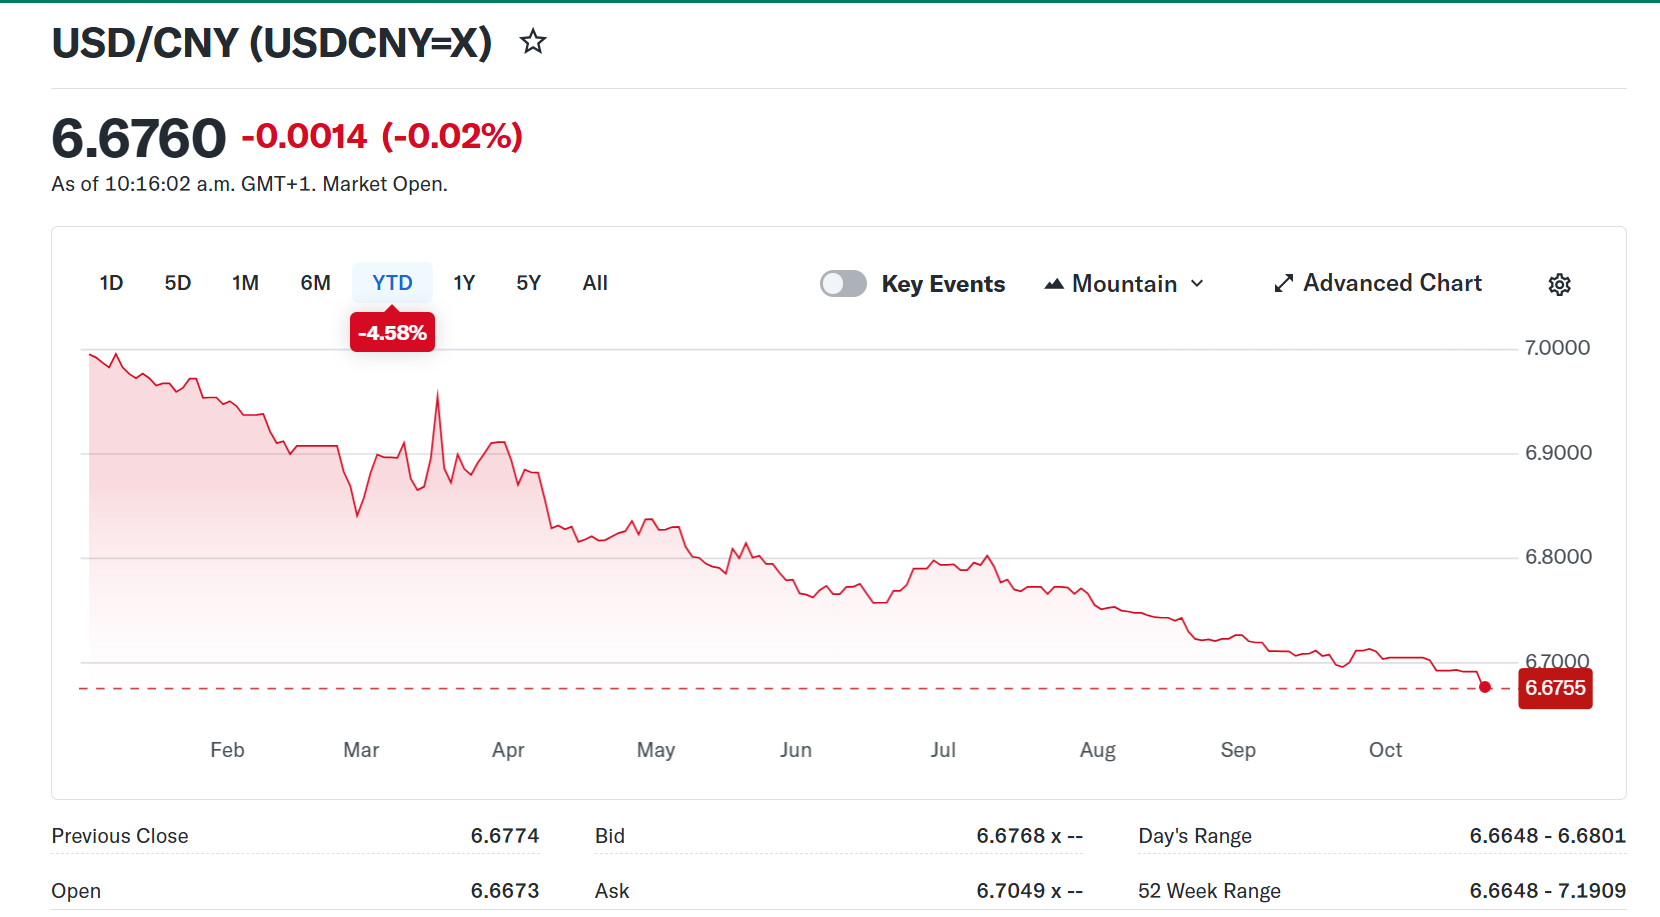
CHINA
PBoC Fix: 6.7200 vs exp. 6.6813 (prev. 6.7208)
Shanghai Shenzhen CSI 300 fell 0.97% to 4,111.93
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Tradingpedia, Business Recorder, TradingView