Agility Forex Daily
November 9, 2026
USDCAD open (6:00 am): 1.4084, overnight range 1.4078-1.4132, close 1.4130
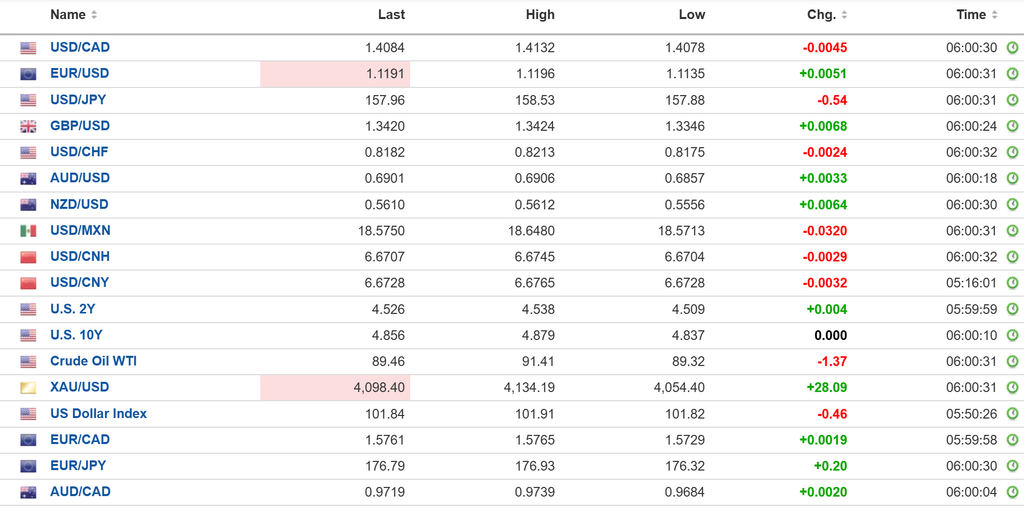
USDCAD rallied Friday but the rally hit a wall at 1.4150 and prices have retreated since. The sell-off had nothing to do with anything domestic. Instead, it occurred because traders thought the risk-off reaction to tech stock weakness and the divergent Canada and US employment reports was overdone. The market already expected a 25 bp rate hike by the Fed in December and the NFP data did nothing to change that view.
However, Canada’s employment report was weaker than expected and raised a lot of questions about BoC Governor Tiff Macklem’s decision to raise interest rates.
WTI traded in a $87.56-$91.41 after Trump says further strikes on Iran look unlikely if negotiations progress.
There is no Canadian or US data of note today.
USDCAD Technical Outlook
The intraday USDCAD technicals are bullish while prices are above the 100-day moving average at 1.4044, but momentum is cooling after Friday’s rally ran out of steam near 1.4150. Prices have eased back to retest support at the 38.2% Fibonacci retracement of the August to October rally at 1.4081.
Longer term, the technical picture has turned positive. Friday’s close at 1.4124 was above the 38.2% Fibonacci level at 1.4081, confirming a bottom at last week’s 1.3929 low and ending the decline from 1.4300. USDCAD is back above the 100-day moving average, and the daily RSI has eased to 62 after Friday’s surge, leaving room for further gains. A daily close above 1.4135 would put 1.4172 and then 1.4200 in play. A daily close below the 100-day moving average at 1.4044 would undermine the recovery and expose 1.3990.
For today, USDCAD support is 1.4075 and 1.4044. Resistance is 1.4135 and 1.4170.
Todays Range 1.4040-1.4140
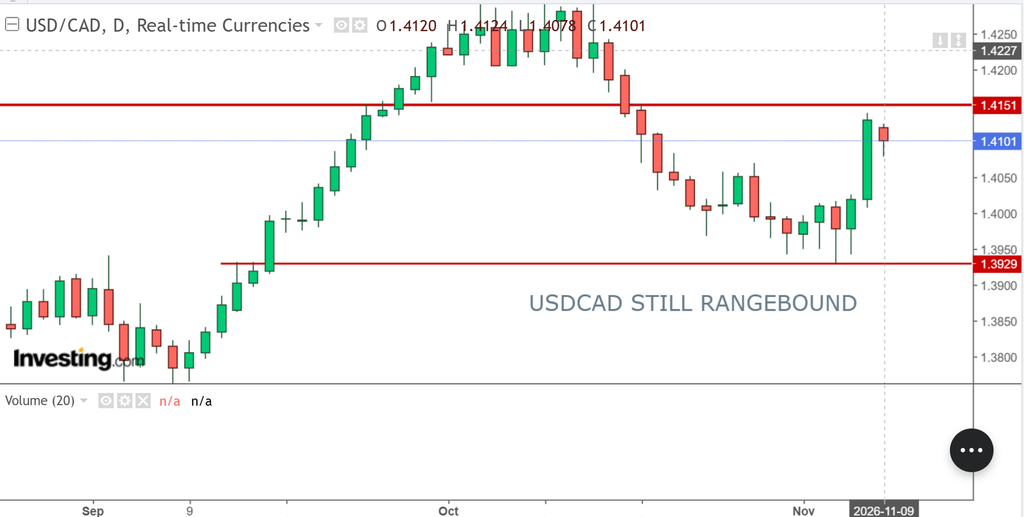
FX Heat Map
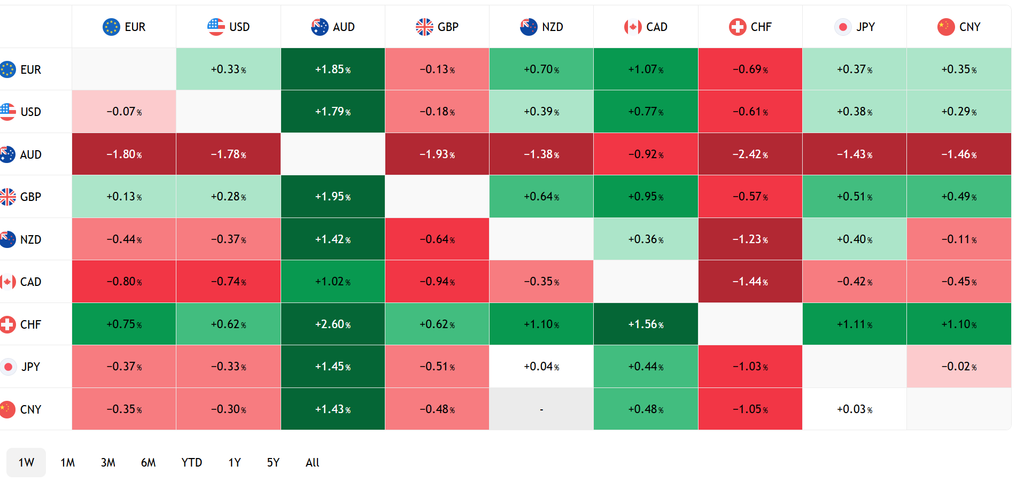
FX open high low 6:00 am
A Few Good Sleeps Puts Things Into Perspective
The world looks a whole lot different today than it did last Thursday and Friday. Friday’s nonfarm payrolls number blew the doors off, adding 165,000 jobs against expectations of 65,000, and the unemployment rate ticked down to 4.1%. The dollar was already climbing before the release as last Thursday’s tech rout bled into defensive stocks and global markets. The odds of a Fed rate hike on December 9 are 80%.
Today, the US dollar index (DXY) has retreated, and it is lower than it was before the US unemployment data.
Taking Stock
Asian equities closed mixed. Japan’s Topix surged 2.97%, while Australia’s ASX gained 0.10% and Hong Kong’s Hang Seng fell 0.13%.
As of 5:35 AM, European bourses are higher. The German DAX is up 1.0%, the French CAC-40 has climbed by 0.82% and the UK FTSE 100 index is up 0.73%. S&P 500 futures have risen 0.81%, the 10-year Treasury yield is 4.834%, DXY is 101.84 and gold (XAUUSD) is $4,123.76..
EURUSD | Range 1.1135-1.1198
EURUSD has recovered all of Friday’s losses in what can best be described as a profit-taking bounce, as the month-long downtrend remains intact while prices are below 1.1250. Sentix Investor Confidence fell to 2.4 from 2.7, which helped to limit gains. German September exports rose 2.0% m/m against a 0.5% forecast.
GBPUSD | Range 1.3346-1.3426
GBPUSD has a small bid, and it has fully recovered Friday’s losses in an uneventful session. Sterling continues to benefit from last week’s hawkish Bank of England monetary policy meeting, which saw external member Catherine Mann advocate for a 50 bp hike. Prices got further support on news that the EU and UK reached a draft agreement to cut red tape across food supply chains.
USDJPY | Range 157.85-158.53
USDJPY dropped on the back of broad US dollar weakness, although further downside is hampered by robust US data supporting a December Fed rate hike. The Ministry of Finance released data about its 3-day USDJPY intervention between July 30-August 3. The government spent 7.98 trillion yen on July 3 and a total of 15.4 trillion over the 3-day period. The spending didn’t do anything to narrow the JGB-US Treasury yield spread.
AUDUSD | Range 0.6857-0.6906
AUDUSD followed the other major currencies higher, but a dovish RBA monetary policy outlook is capping gains. However, higher PPI data in China has provided some support. AUDUSD traders were keeping a close eye on the New Zealand election. Preliminary results point to Prime Minister Luxon keeping his job.
USDMXN | Range 18.5467-18.6480
USDMXN gave back Friday’s gains and is near support at 18.5300, which contained losses for nearly three weeks. The decline is more impressive considering Banxico surprised markets with a 25 bp rate cut to 6.25% last week.
CHINA
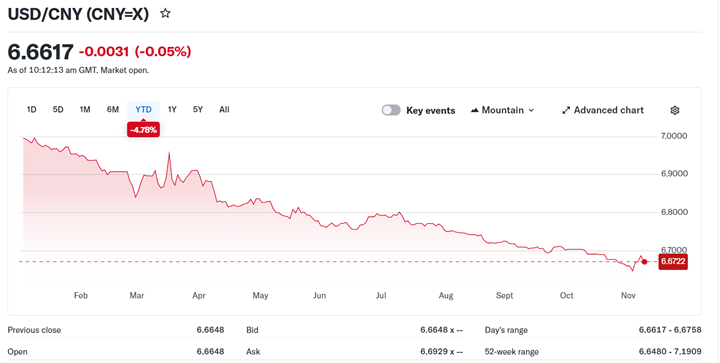
PBoC Fix 6.7188 vs exp. 6.6799 (prev. 6.7168)
Shanghai Shenzhen CSI 300 rose 0.05% to 4,056.11
China’s October inflation data was mixed. CPI rose 0.7% y/y, below the 0.8% consensus and its weakest reading in three months, while core CPI eased to 0.8%, reinforcing concerns about soft domestic demand.
PPI rose 5.7% y/y, comfortably above the 5.3% forecast and its fastest pace in nearly four and a half years.
The divergence highlighted the uneven nature of China’s economic recovery, with producer prices accelerating while consumer demand remained subdued.
On November 3, the PBOC announced that it would raise the foreign-exchange deposit reserve requirement from 4% to 6%, effective November 15, the first increase in nearly five years.
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Tradingpedia, Business Recorder, TradingView