By Michael O’Neill
If Tiff Macklem were coaching a football team facing third-and-seven, would he go for the first down or play it safe? He faces a similar dilemma as Governor of the Bank of Canada with the next monetary policy announcement due in seven days.
Judging by his weekend comments at a meeting in Bangkok, his mind may be already made up. He warned that the ongoing Middle East conflict and damage to refining capacity increased the risk of inflation broadening and becoming more persistent. He added, “We are prepared to adjust monetary policy as needed.” His comments were not much different from what he said in Halifax three weeks earlier when he said that they do not “want to be too slow to respond if inflationary pressures are becoming more persistent.”
Monday’s inflation numbers may have made his decision easier. Then the Q3 Business Outlook Survey and Consumer Expectations Survey greased the skids.
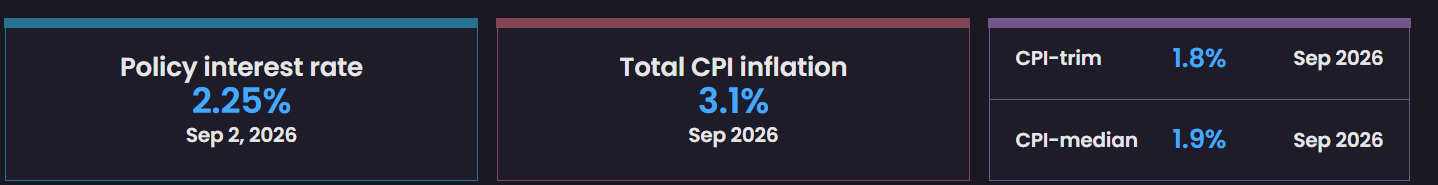
September CPI rose to 3.1% year over year from 3.0% in August but came in below expectations. The increase was largely driven by gasoline prices, which surged 27.8%. The headline figure is moving higher, but the underlying measures tell a different story: an energy shock is pushing inflation up without clear evidence of a broad-based acceleration in price pressures.
The Bank’s Business Outlook Survey and Consumer Expectations Survey point to rising inflation anxiety. Businesses expect inflation to reach 3.7% over the next year, while consumers expect about 4% and believe inflation is already running at 3.9%, against actual CPI of 3.1%. Both groups blame energy prices and tariffs.
Hut, Hut, Why Hike?
There is a growing chorus of economists at major financial institutions forecasting a rate hike next week, including Scotiabank and JPMorgan Chase. Other economists at BMO, RBC Dominion Securities and Desjardins Group are also leaning toward tighter policy. But it is not a done deal. Far from it. Bankofcanadaodds.com puts the odds of rates being left unchanged at 77%.
The rationale for a rate increase is rather sketchy. Mr. Macklem is eyeing surging energy costs and, last weekend, announced that the BoC would “significantly” upwardly revise its inflation forecasts because he fears prolonged high energy costs will spill over into the economy.
In essence, he is claiming that his “gut feelings” outmatch the data-dependent approach he has championed since last April. It is a striking pivot. Just 10 days ago at the IMF summit, he joined other global central bankers in signing a statement that pledged to “continue to adjust policies in a data-dependent manner.”
The evidence does not support his gut. Those survey expectations are perceptions, not prices. Consumers already think inflation is 3.9% when it’s actually 3.1%, which tells you how far gasoline is colouring their view. The BoC’s own inflation measures, CPI-trim and CPI-median, both ticked lower in September, to 1.8% and 1.9%, respectively. Canada’s underlying inflation measures are largely behaving themselves, the labour market is soft, and economic growth is hardly threatening to overheat.
Hiking rates to combat what may prove to be a transitory inflation shock driven by energy prices risks tightening monetary policy against an economy that can ill afford it. A rate hike would be a pre-emptive strike against a perceived risk, and before the evidence arrives, knowing that such a move makes life substantially more difficult for Canadians renewing mortgages, among other things.
It’s the Fed’s Ballgame
Macklem may be the quarterback, but the Federal Reserve is calling the plays, and it is widely expected to take a knee at its October 27–28 meeting. The Fed raised rates for the first time since 2023 last month, and with US midterm elections just days away, policymakers may prefer to let the data reveal the impact of that move before tightening again.
There is another consideration. Longer-dated US Treasury yields surged in early October, delivering a de facto rate hike. Higher yields push up commercial borrowing costs and mortgage rates, tightening financial conditions without the Fed having to touch its policy rate. The bond market is already doing some of the Fed’s work for it.
For Macklem, a Fed on hold means he does not need to anticipate a US rate hike that markets aren’t expecting. If both central banks hold, attention will shift to Wall Street because tech juggernauts Microsoft, and Alphabet report Q3 earnings on October 28.
The likeliest play is that the October Monetary Policy Report will do the heavy lifting, with sharply higher inflation forecasts setting the stage for a December rate bump.
For now, Macklem doesn’t need to call an audible when the ball hasn’t even been snapped.