USDCAD open: 1.4109, overnight range 1.4093-1.4124, close 1.4104
USDCAD is grinding higher for a fifth straight session as surging US Treasury yields drive US dollar demand. Yesterday’s robust US S&P PMI data and additional hawkish Fed-speak have raised the odds for a Fed rate hike at the end of October to 75%.
Widening CAD/US interest rate spreads also supported the greenback. The 2-year spread widened to -148.6 (it was -127.9 a month ago) while the 10-year spread moved to -116.1 from -115.3 yesterday.
Oil is having a rough ride, trading from an overnight low of $91.43 to $94.68 in NY trading. -$93.68 range. The lack of an Iran/US ceasefire agreement or even a pause has put a floor under prices. Furthermoe, an IRGC advisors to the Supreme Leader of Iran warned that the war could expand to the Indian ocean if the USD attacks again.
Canada retail sales fell 0.7% m/m in July(forecast -0.8%, June -0.6%) while retail sales ex-autos fell 0.7% m/m compared to the expected dip of -0.5%. The data is rather meaningless because since then, the US and Canada have exchanged hefty tariffs.
USDCAD Technicals
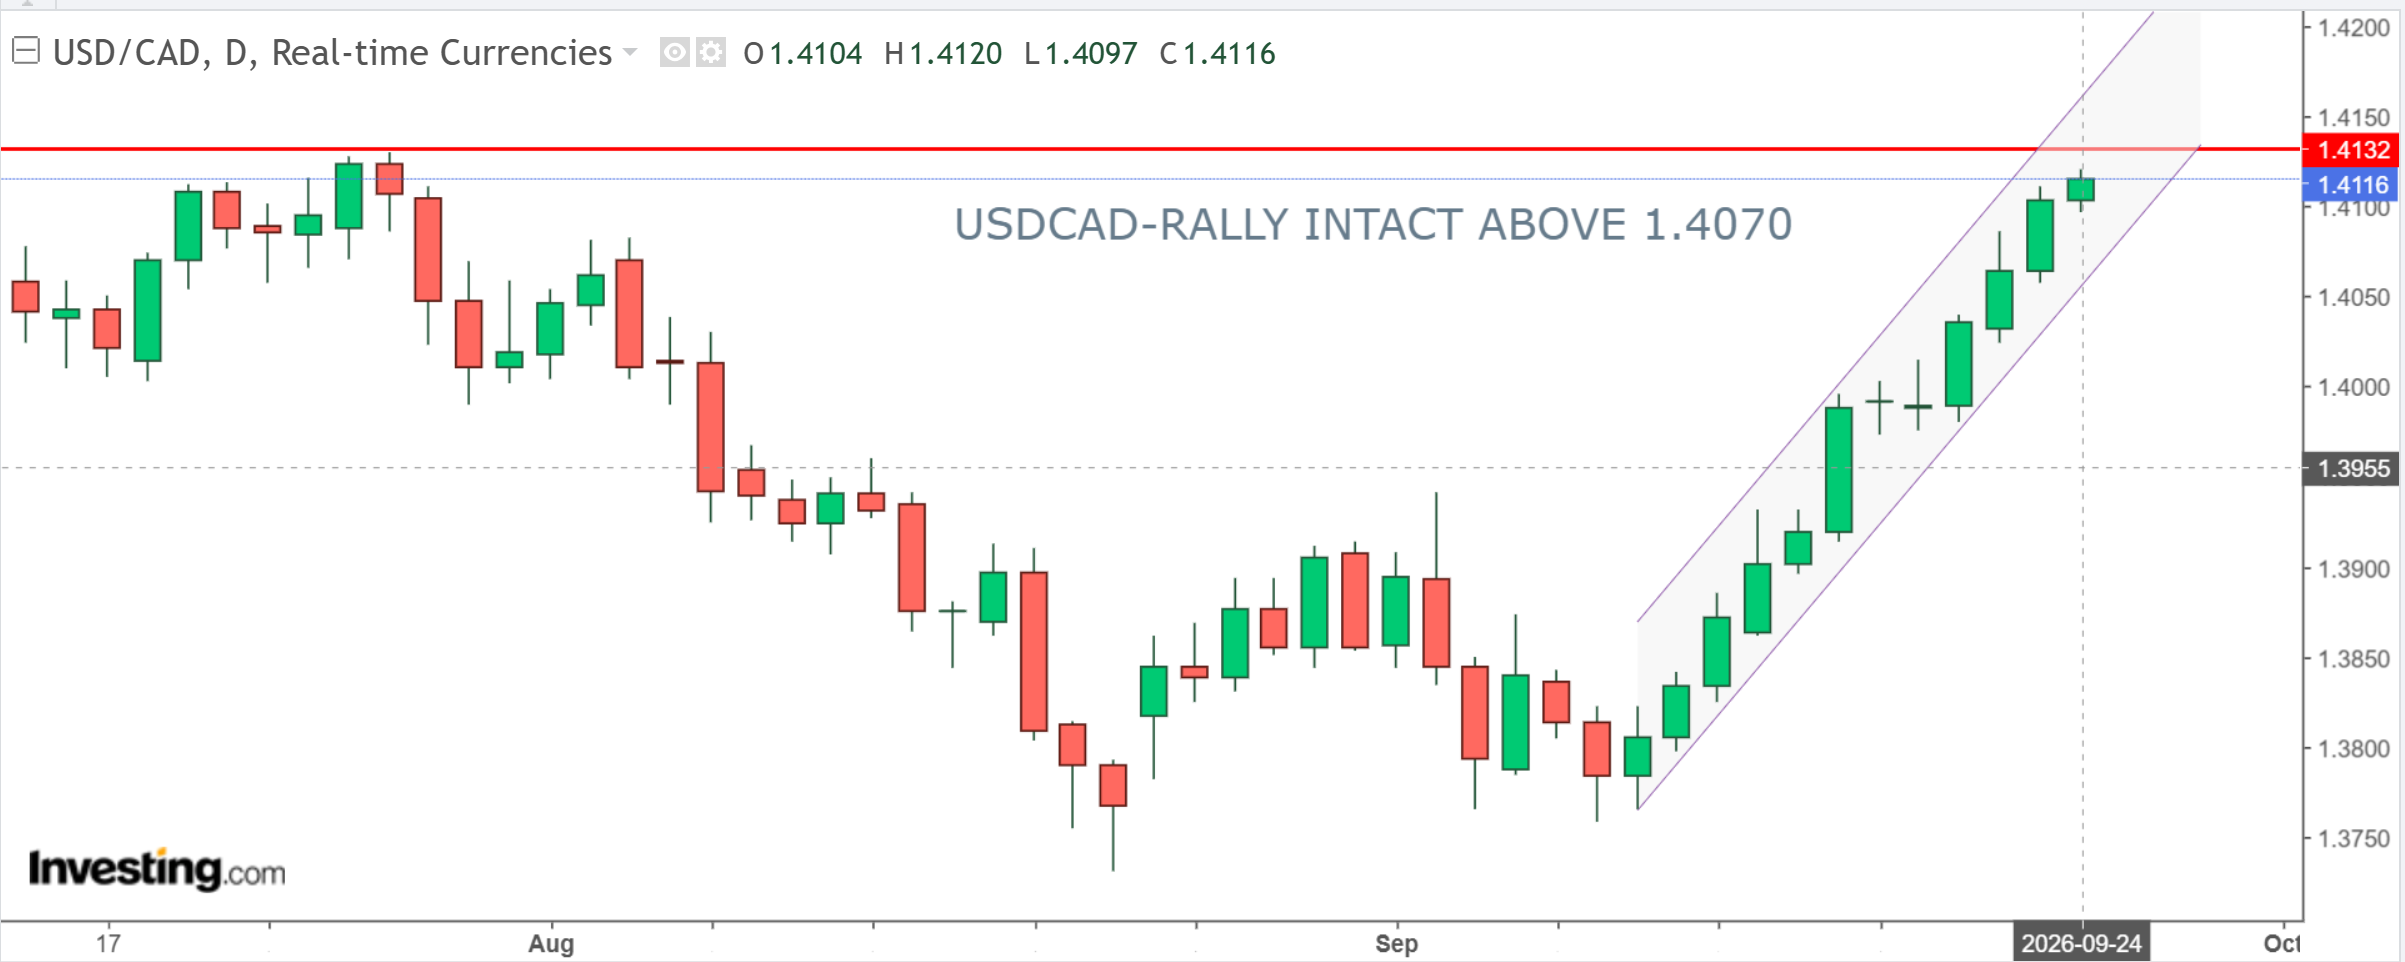
The intraday USDCAD technicals are bullish above 1.4070. The rally from the late-summer low near 1.3730 remains intact, and today’s session pushed to a fresh intraday peak of 1.4120, extending a rising channel that has been in place since mid-September. However momentum studies show USDCAD is at extreme overbought levels.
Longer term, price is close to testing the 78.6 Fibonacci retracement of the July-August downtrend in the 1.4135-1.4140, area. A decisive break above 1.4150 would open the way to the 1.4250 high, the 100% retracement of that same move, and potentially as far as 1.4400 further out.
For today, support is 1.4070 and 1.4040. Resistance is 1.4140 and 1.4180
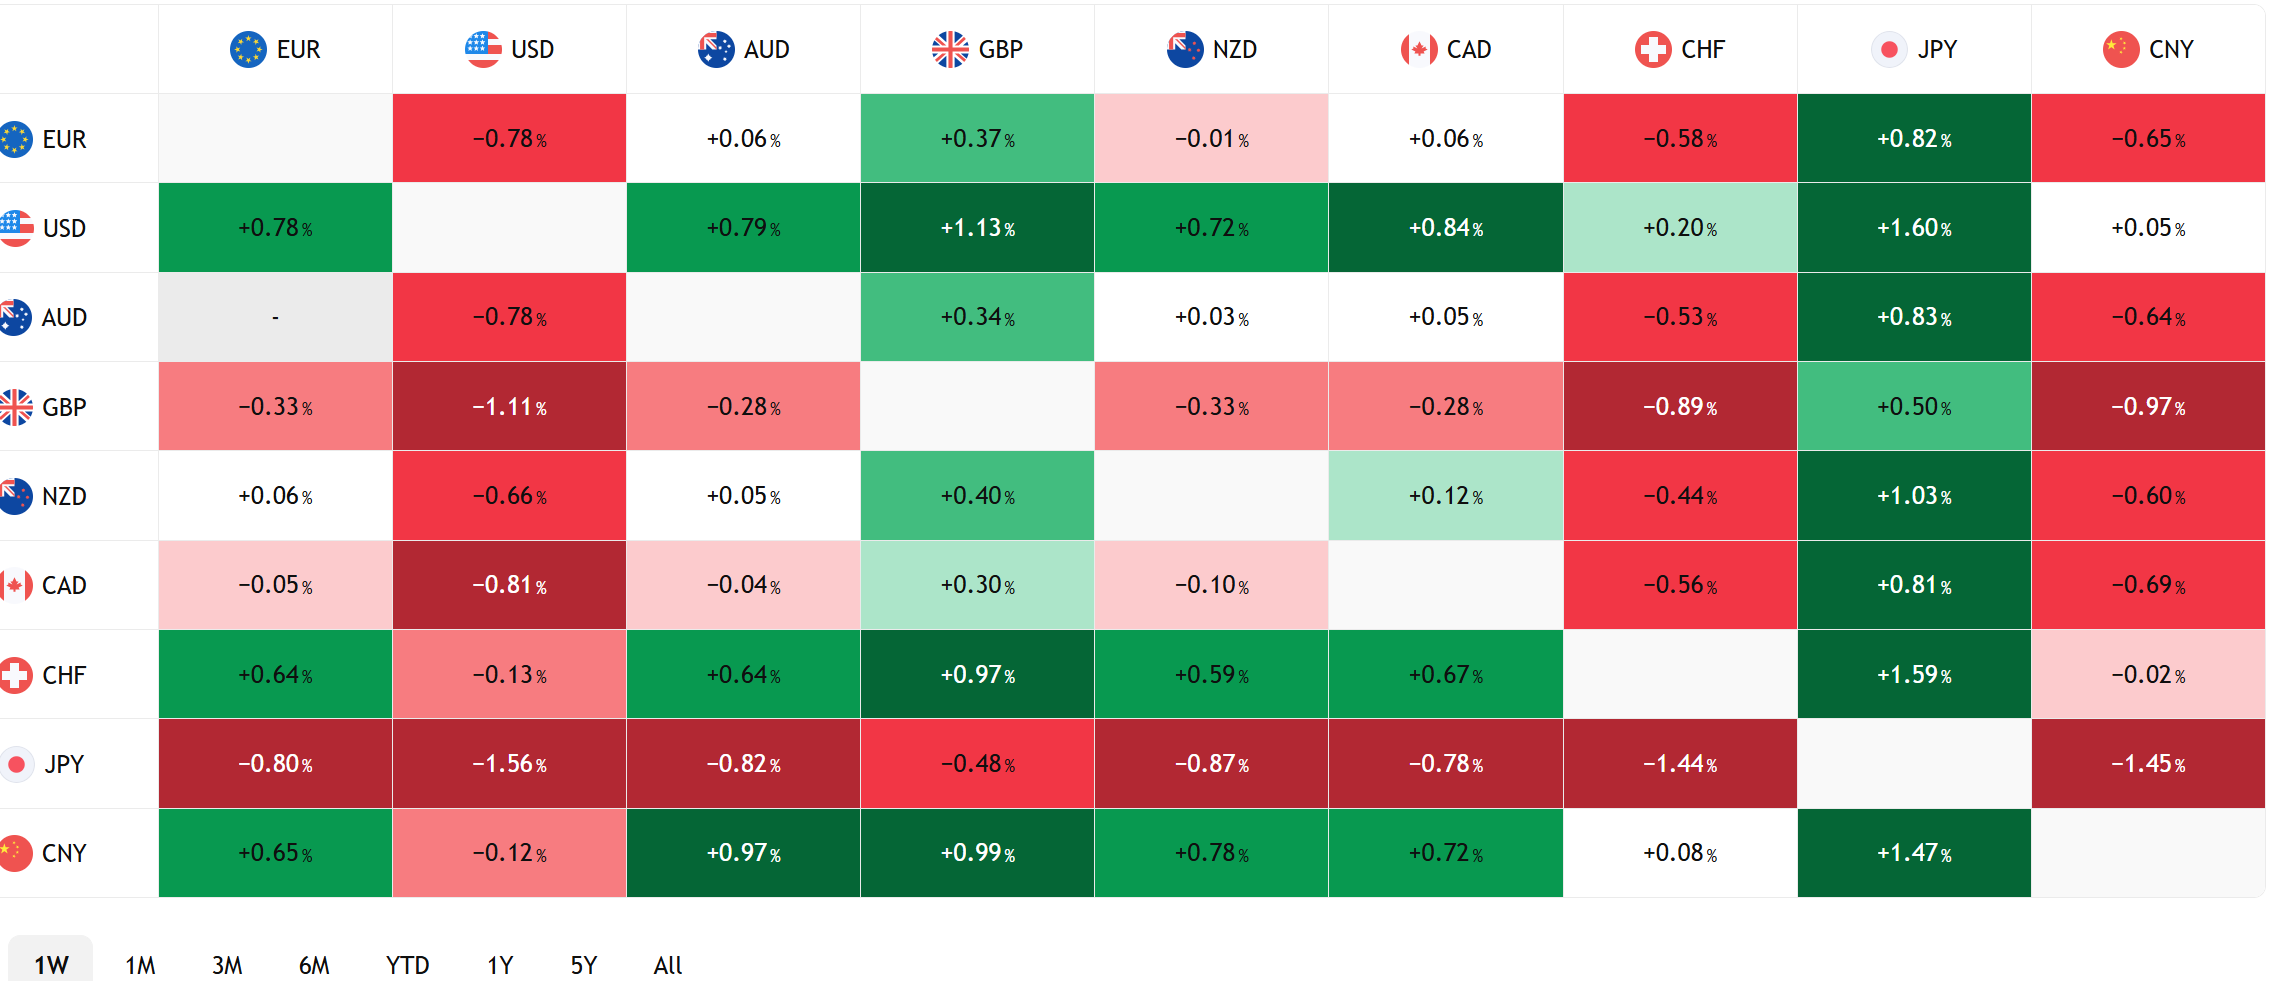
FX Heat Map
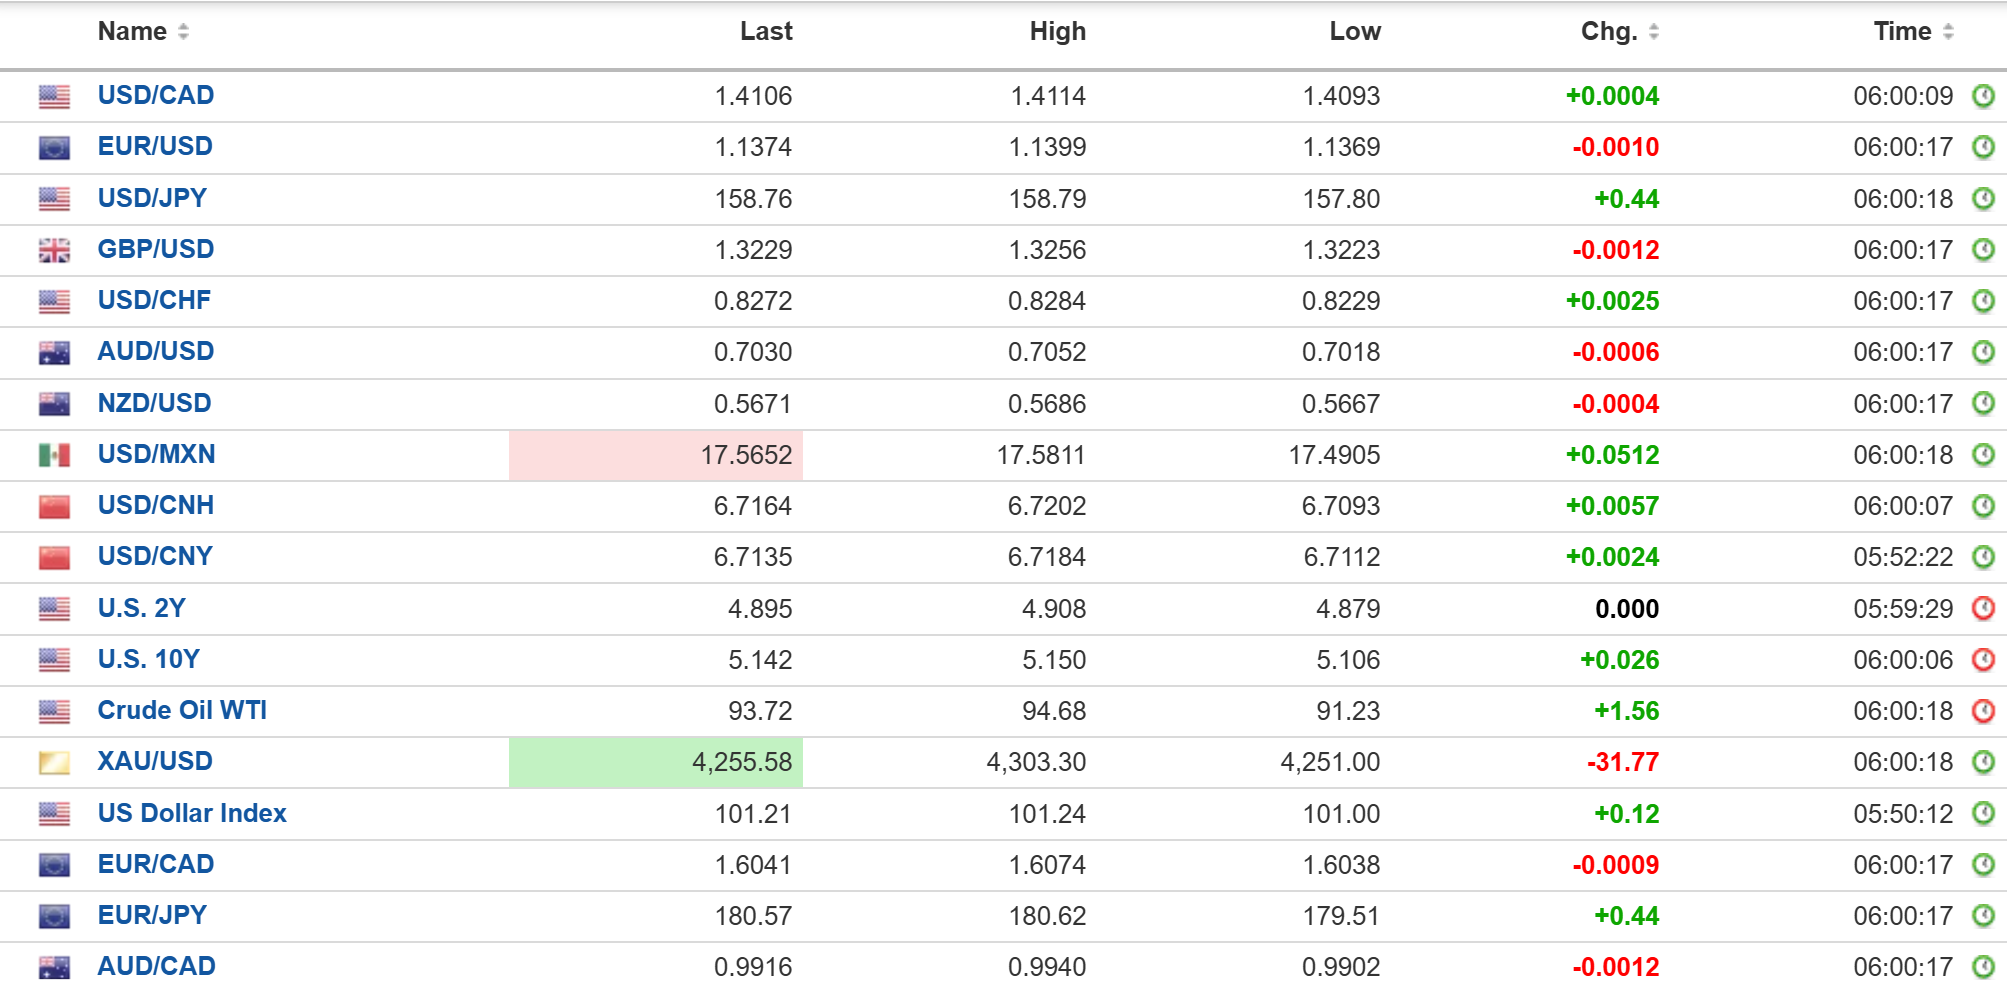
FX open high low 6:00 am
US Economic Resilience
Yesterday’s S&P Global reported US Composite PMI jumped 58.4 from 56.0, its strongest reading since July 2021. Rising demand is also pushing costs higher, which validates the Fed rate hike and lifts the odds for another hike at the end of October to over 75%.
Today, weekly jobless claims were 197,000, virtually unchanged from last week and served to reinforce the robust US economy narrative.
Hail the King
Trump went all out in greeting Chinese President Xi Jinping. He rolled out the red carpet (literally) and then stood on the tarmac to await Jinping’s arrival. Trump succeeded in getting a trade truce extension with Bessent announcing the existing deal will end in January. Traders will be looking for further developments form today’s meetings.
Taking Stock
Asia equity indexes closed with losses led by a 0.72% decline in Australia’s ASX 200. Japan’s Topix fell 0.39% while Hong Kong’s Hang Seng dropped 0.29%.
As of 5:40 am PT, European bourses are flat to lower. The UK FTSE 100 is unchanged while the French CAC 40 and the German Dax are down 0.32%. S&P 500 futures are down 0.55%, the 10-year Treasury yield is off its 5.15% peak and sits at 5.12%, the DXY is 101.30 and gold is $4,274.65.
EURUSD | Range 1.1362-1.1399
EURUSD blasted through support at 1.1400 and dropped steadily overnight. The selling pressure is due to the surge in Treasury yields to 5.15% overnight, yesterday’s robust US PMI report and a slew of hawkish comments from Fed officials. The result is that the odds for the Fed to raise rates to 4.25% in October are 75%. Better-than-expected German Ifo data had little impact.
GBPUSD | Range 1.3215-1.3256
Sterling got hammered on the back of broad US dollar demand with the surge in Treasury yields and increased Fed rate hike odds and the lingering bearish sentiment from yesterday’s UK PMI data. Hawkish comments by BoE policymaker Clare Lombardelli warning that “rates are likely to rise” were largely ignored.
USDJPY | Range 157.80-158.80
Traders returned from a three-day break and bought USDJPY due to the rise in US Treasury yields and the increased odds for a Fed rate hike. USDJPY continues to be underpinned by the BoJ’s dovish rate hike. Japanese Finance Minister Satsuki Katayama made noises about “the principles of intervention,” but the comments were ignored.
AUDUSD | Range 0.7018-0.7052
AUDUSD retreated due to broad US dollar strength. Australia’s unemployment rate ticked up to 4.6% in August (forecast 4.5%, July 4.5%) while the economy added 39,500 jobs, all of which were part-time. Expectations for the RBA to hike rates by 25 bp next week helped limit the losses.
USDMXN | Range 17.4905-17.6020
USDMXN rallied sharply yesterday, continued to climb overnight and has its sights set on the 17.700 resistance area which has capped gains since June. Mexico’s 1st half of the month core inflation rose 0.17%, a tad softer than the 0.2% expected. Banxico’s policy decision is due later today, and they are expected to leave rates unchanged at 6.50%. The rising odds for the Fed to raise rates are rapidly shrinking Mexico’s yield advantage.
CHINA
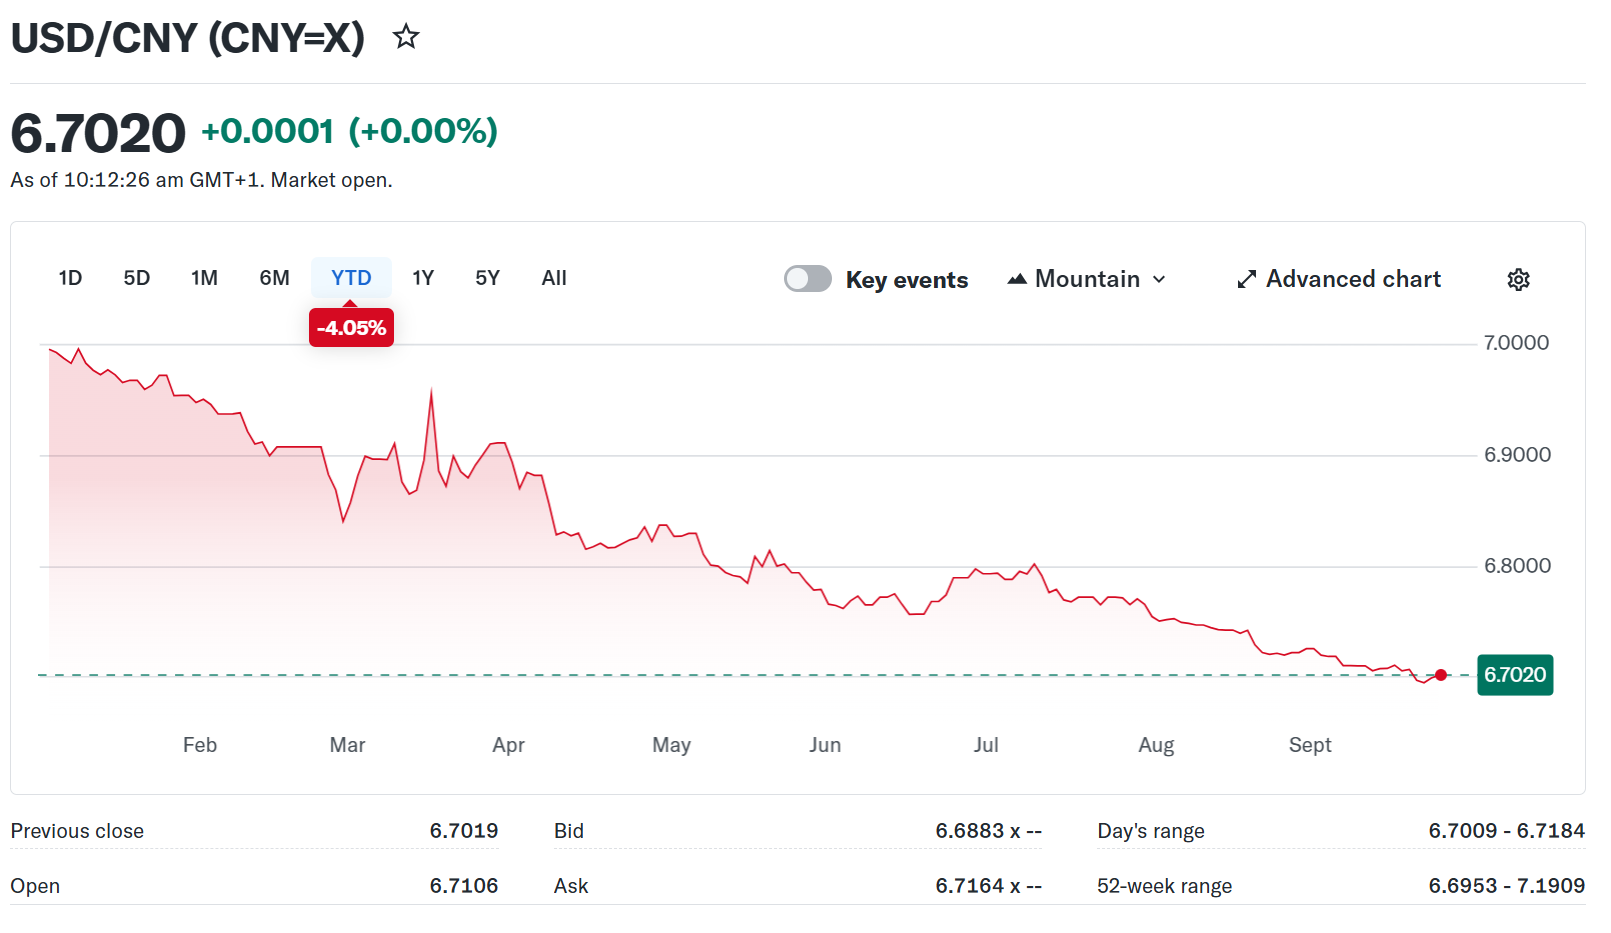
- PBoC Fix 6.7489 vs Exp. 6.7184 (prev. 6.7468)
- Shanghai Shenzhen CSI 300 fell 1.73%% to 4,439.15
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview