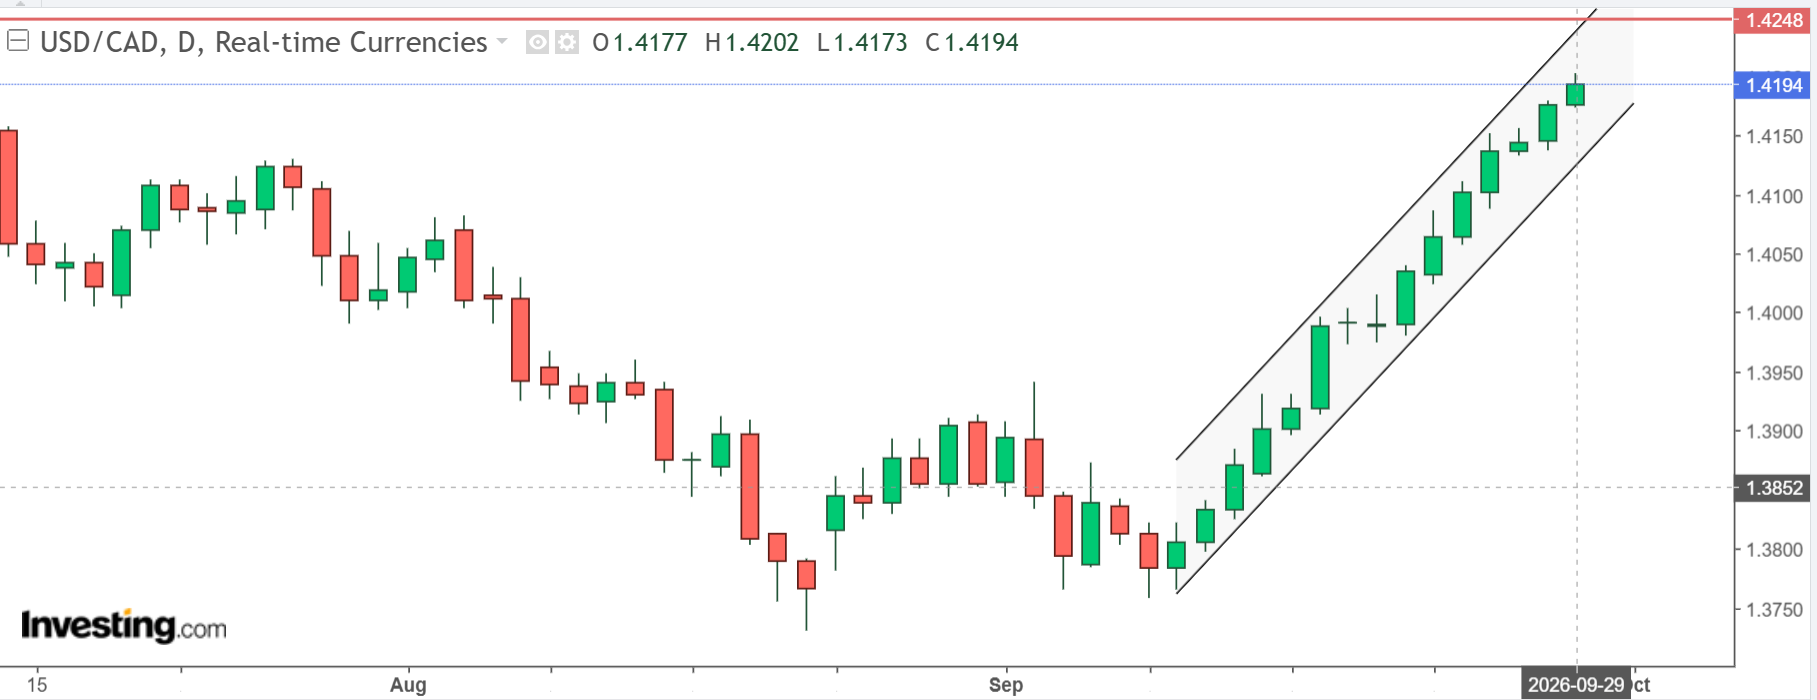
USDCAD open (6:00 am): 1.4200, overnight range 1.4170-1.4202, close 1.4176
USDCAD ground out a fresh gain due to broad US dollar strength and elevated Treasury yields while CAD/US 2-year and 10-year interest rate spreads remain wide.
At 12:01 am today, Trump’s ban on about $1.0 billion worth of Canadian goods which is aimed at dairy and alcohol among others. Economists suggest the action will only have a minimal impact on GDP, unless of course you are one of the many who’s job may be impacted. Then your GDP (Gross Disposable Pay) will evaporate.
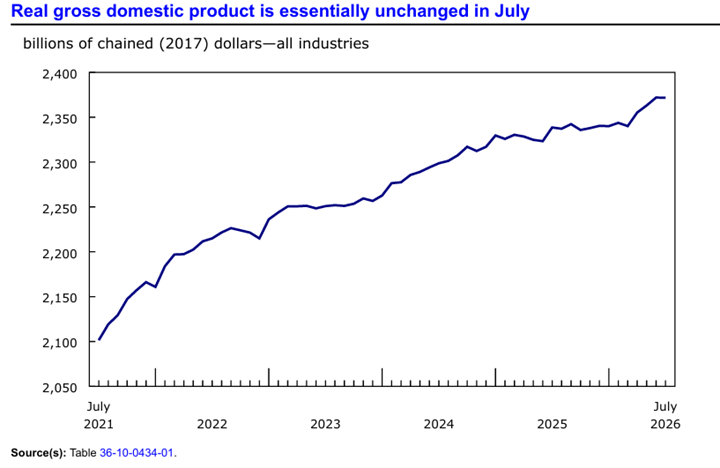
Stats Canada reported that economic growth was flat (0%) in July. The economy stalled even before new U.S. tariffs arrived suggesting things will only get worse.
WTI oil traded sideways in a $90.33-94.72 band range with losses fueled by renewed optimism for an end to the US and Iran war due to indirect talks happening in Qatar. Reports that Saudia Arabia has restarting shipments from its port on the Red Sea also helped drive prices lower. Trump’s war on Iran is a boost for Canadian energy. Shell plans to proceed with plans to double its LNG export capacity with Phase 2 of its Kitimat BC project.
BoC Deputy Governor Toni Gravelle will be speaking in NY at 1:30 pm.
USDCAD Technical Outlook
The intraday USDCAD are bullish while trading above 1.4150 and looking to test resistance at 1.4250. The momentum indicators are at extreme overbought levels, but rising yields and trade tensions suggest that the overdue correction may be shallow and short-lived.
Longer term, a decisive break above 1.4250 would put the Covid peak of 1.4660 (March 2020) in play. A break below 1.4120 suggests further losses to 1.4020.
For today, support is 1.4160 and 1.4130. Resistance is 1.4220 and 1.4250.
Todays range 1.4160-1.4250
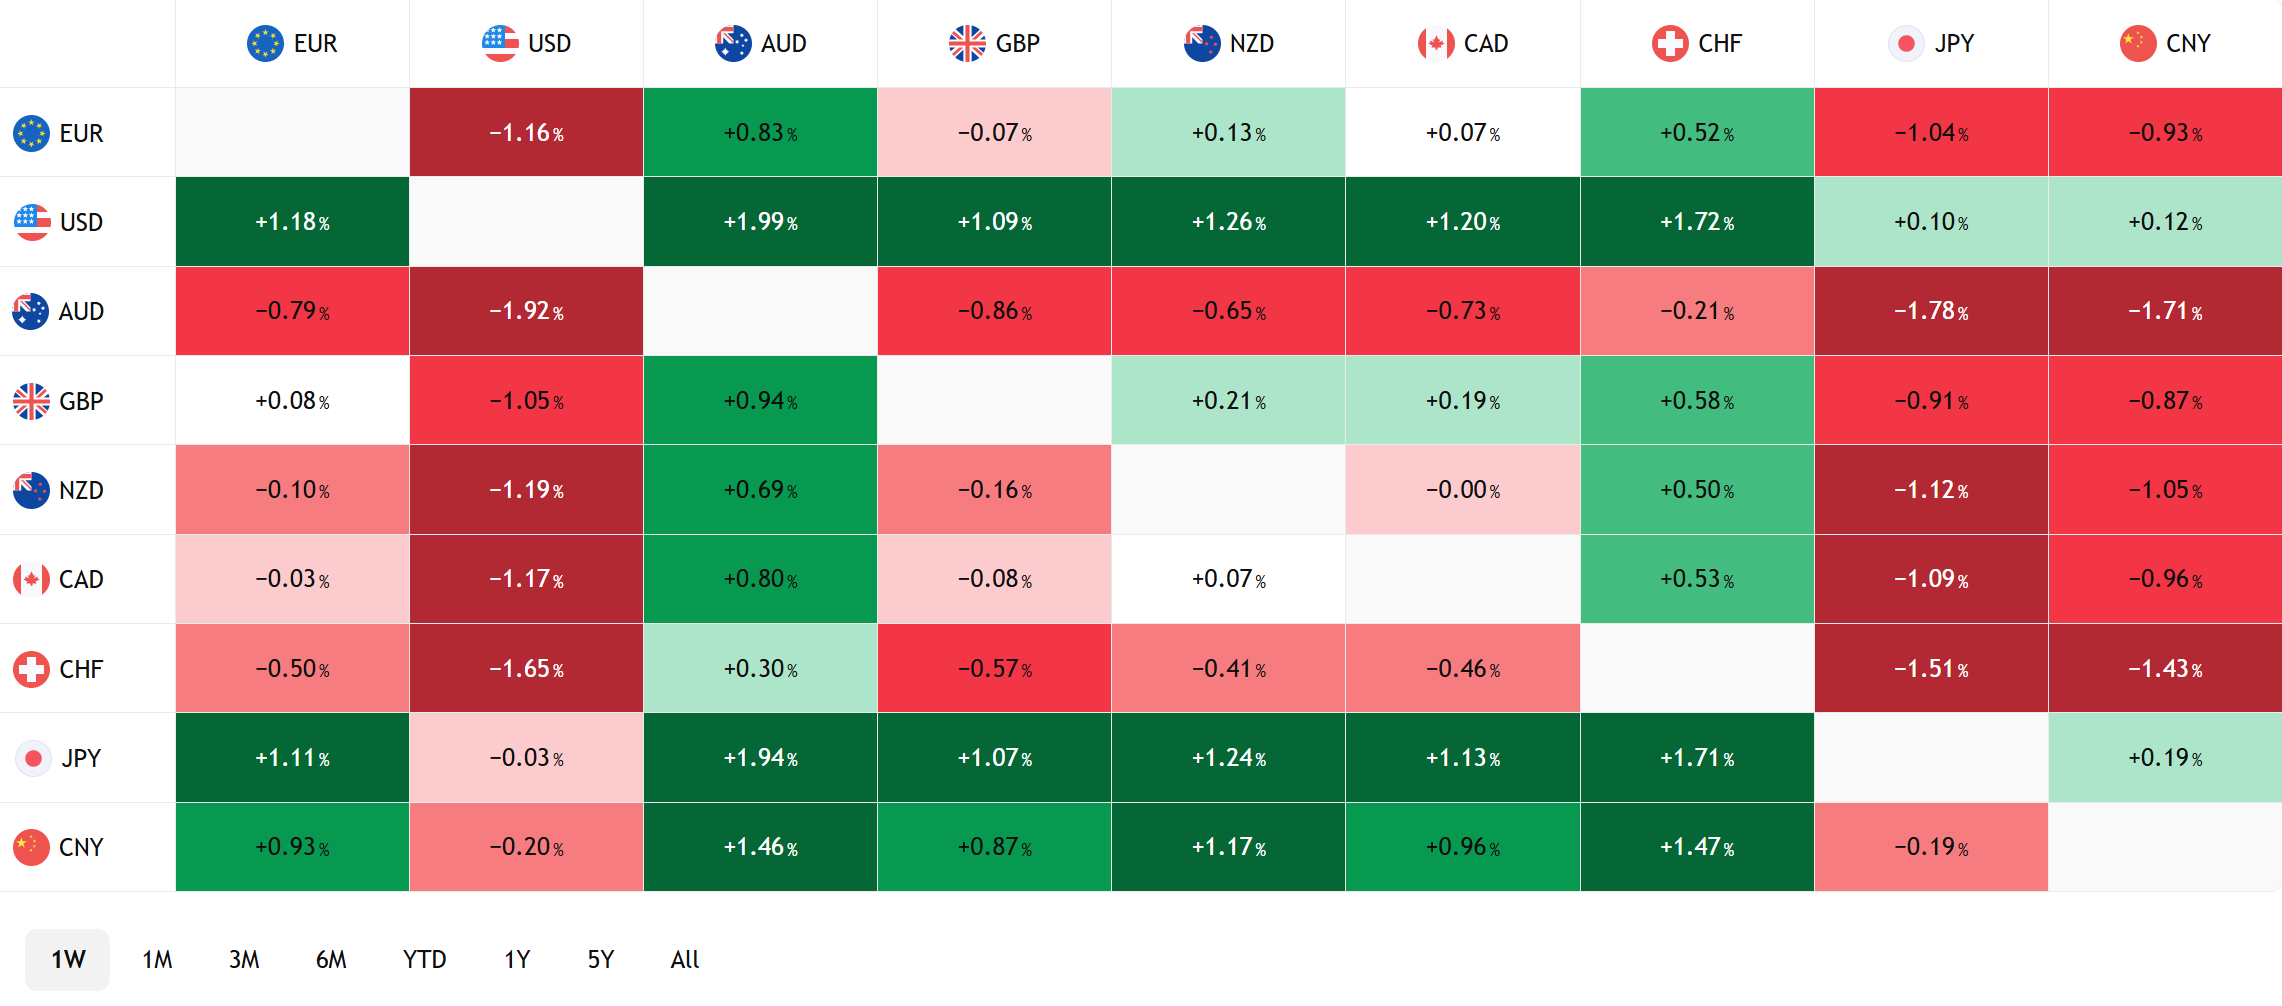
FX Heat Map
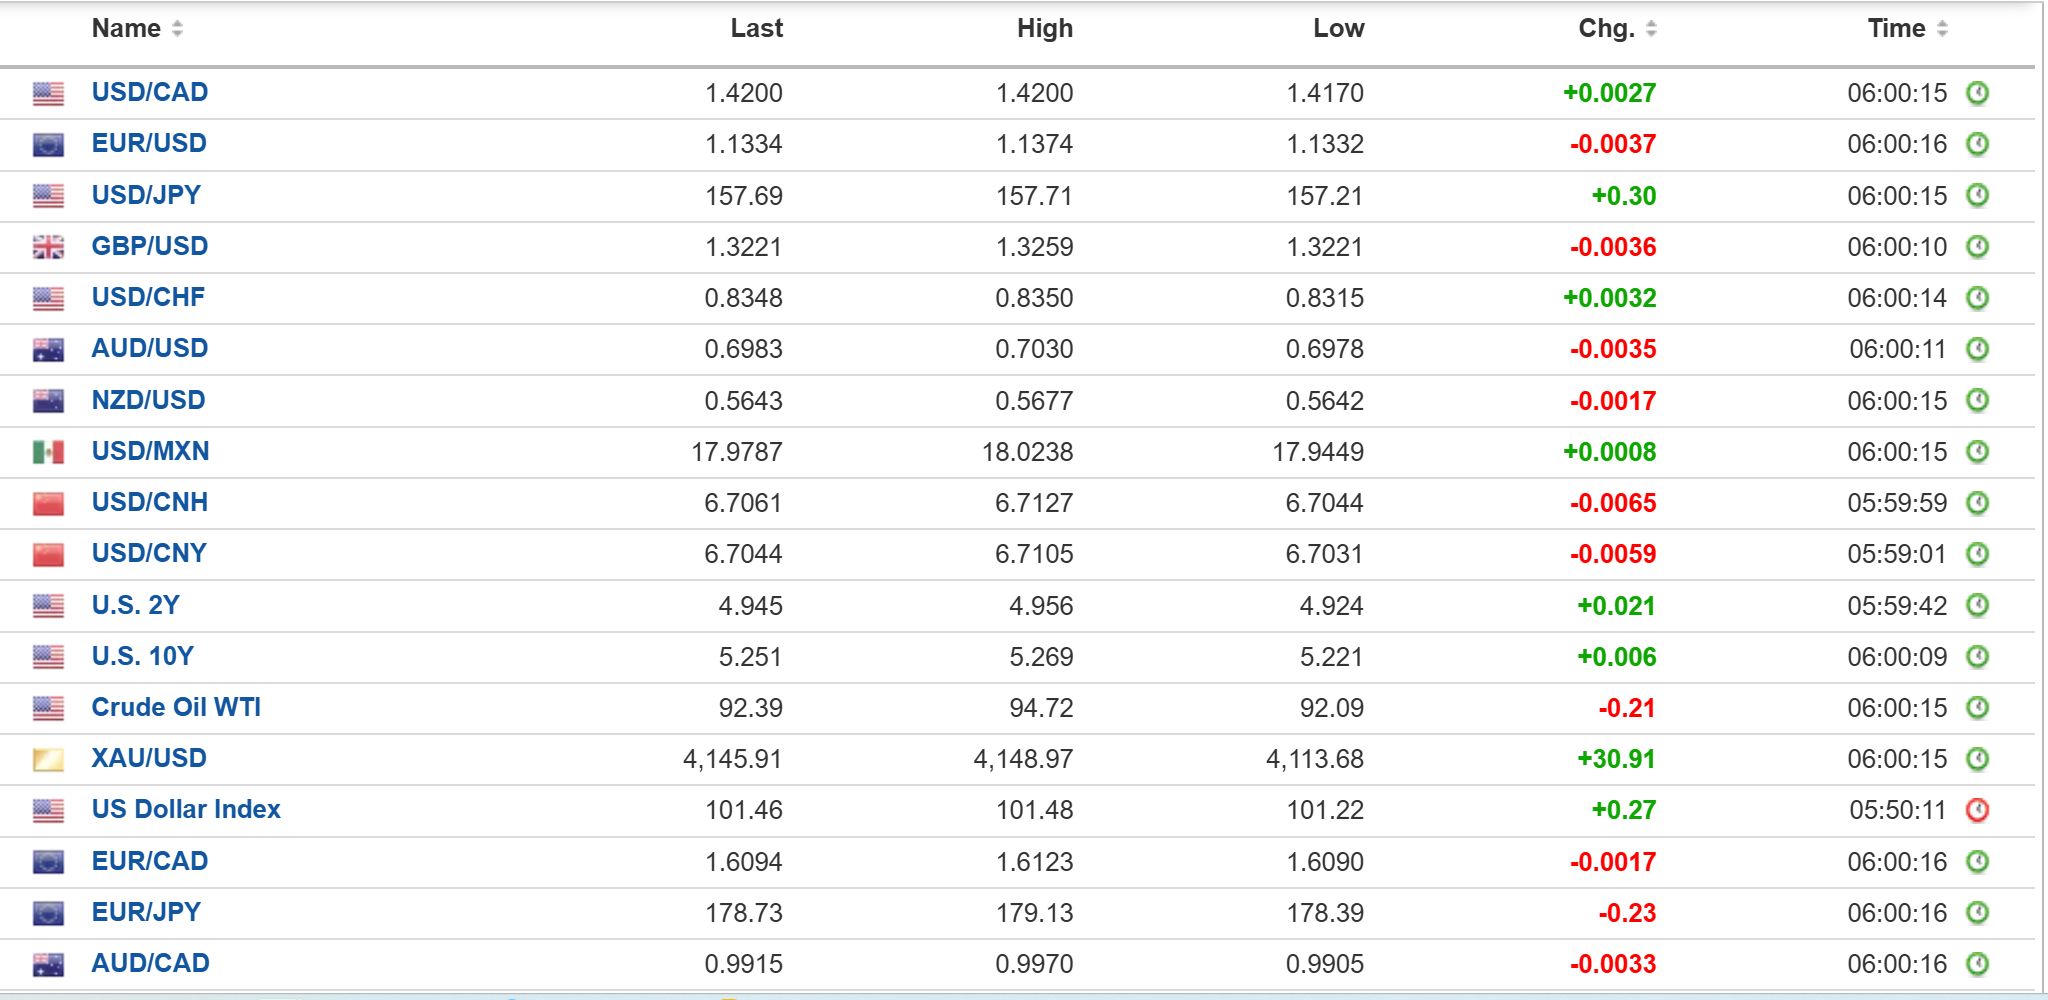
FX open high low 6:00 am
Rising Treasury Yields JOLTS
The near-perfect storm of energy shocks, resilient US economy, hawkish Fed outlook and massive tech/AI bond issuance continues to drive Treasury yields to decades high peaks. The US 10-year yield hit 5.28% yesterday and is sitting at 5.247% today.
US nonfarm payrolls data is due Friday and various employment indicators are on tap this week. Today Job Openings and Labour Turnover Survey (JOLTS) is expected to show Job opens fell to 7.23m from 7.271. Economists are hoping to see weaker labour demand which should help cool inflationary wage growth.
US Consumer Confidence is expected to rise to 90.1 from 89.4. Case-Shiller Home Price Indices are also on tap.
Taking Stock
Asian equities were mixed. Japan’s Topix dropped 1.72%, Hong Kong’s Hang Seng eased 0.48% while Australia’s ASX 200 traded rose 0.34%.
As of 5:40 am P, European bourses are higher led by a 0.75% gain in the German Dax. The UK FTSE 100 is up 0.19% while the French CAC-40 has gained 0.11%. S&P 500 futures are up 0.13%, the U.S. 10-year Treasury yield is 5.227%, the DXY is 101.33 and gold is $4,151.65..
EURUSD | Range 1.1332-1.1374
EURUSD is not having a good Tuesday. Prices have slid steadily due to broad dollar demand tied to surging Treasury yields. ECB President Lagarde adopted a slightly dovish tone when she reiterated that a measured policy response remains appropriate to keep inflation in check. EURUSD extended the slide after Eurozone Economic Sentiment Indicator was weaker than expected (actual 97, forecast 99, previous 98.5) while Consumer Confidence was unchanged at -16.5.
GBPUSD | Range 1.3221-1.3259
Sterling drifted lower on the back of rising Treasury yields and broad-based demand for greenbacks. The only UK data todays was BRC shop price inflation which slowed to 1.4%. UK traders are being distracted by reports that PM Andy Burnham will use his first Labour conference speech as prime minister to edge the UK closer to rejoining the EU.
USDJPY | Range 156.99-157.72
USDJPY traded sideways in a tight band in Asia than got a tad more volatile in late Europe, early NY trading. Comments by Japanese Finance Minister Satsuki Katayama about Treasury Secretary Bessent agreeing to step up cooperation helped to limit gains. Meanwhile rising oil prices and Treasury yields put a floor under prices.
AUDUSD | Range 0.6978-0.7030
AUDUSD gave back its initial pop after the RBA’s expected 25 basis point hike to 4.60%, and its hawkish guidance offset by broad US dollar gains from rising yields. RBA Governor Michele Bullock argued that labour market conditions were too tight and that demand exceeded the economy’s capacity. Analysts expect at least one more hike this year.
USDMXN | Range 17.8725-18.0238
USDMXN technicals are bullish above 17.6700 and peaked above 18.0000 resistance area overnight before the rally stalled. A sustained break targets the 2026 peak in the 18.0400. Surging US Treasury yields continue to erode Mexico’s yield advantage, and with broad dollar demand showing no signs of slowing, the peso remains under pressure.
CHINA
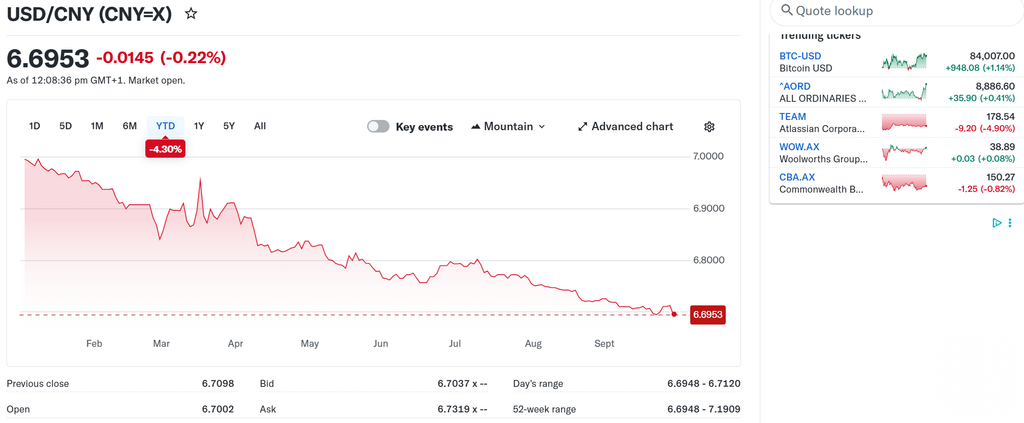
- PBoC Fix: 6.7411 vs Exp. 6.7177 (prev. 6.7399)
- Shanghai Shenzhen CSI 300 fell 2.22% to 4,340.76.
US and China agreed to cut reciprocal tariffs by US$30 billion and launch a bilateral AI dialogue. China will buy US coal in 2027 and 2028 and establish a joint agricultural working group. Beijing also signalled it could allow ByteDance and Alibaba to buy Nvidia’s high-end computer chips.
Sources: Investing.com, Bloomberg, Reuters, Yahoo Finance, US Census Bureau, Trading Economics, Tradingview