October 15, 2026
USDCAD open (6:00 am): 1.4204, overnight range 1.4195-1.4241, close 1.4238
USDCAD slid back to the floor of its October range as the US dollar spent the night walking back Wednesday’s CPI-fuelled swagger. A steep drop in the 10-year Treasury yield to 5.073% from 5.31% on Tuesday helped, as it dramatically shrank CAD/US yield spreads, with the 10-year spread narrowing from -136.1 yesterday to -120.4 this morning while the 2-year spread narrowed to -149.4 from -161.8.
WTI churned in a $93.59-$95.38 band and sits near $95.00, unable to decide whether to fear Tehran or Washington. Ships keep getting hit around the Strait of Hormuz even as Trump boasts about having complete control of the waterway. Meanwhile, the Trump administration is weighing looser sanctions on the shadow fleet hauling Russian, Iranian and Venezuelan crude, and there are reports that the US may receive some diesel from Russia before the midterm elections.
Canadian August manufacturing sales rose 1.5% (forecast 1.1%, previous -0.4%) while wholesale sales were -1.6 % forecast -1.5%, previous 0.3%) were not a factor.
Today, US September PPI surged 1.3% (forecast 0.5% m/m) and 6.3% y/y, (forecast 5.3% y/y), while core-PPI rise 0.7% m/m (forecast 0.3% m/m) which argues that yesterdays spike in CPI was not an anomaly-the US has an inflation problem.
Meanwhile, US retail sales rose 0.8% (forecast 0.3%) with higher oil prices responsible for the bulk of the gains. Weekly jobless claims were 199,000 (forecast 200K) and a non-event. The Philly Fed survey was 20.9 (forecast 28.4).
USDCAD Technical Outlook
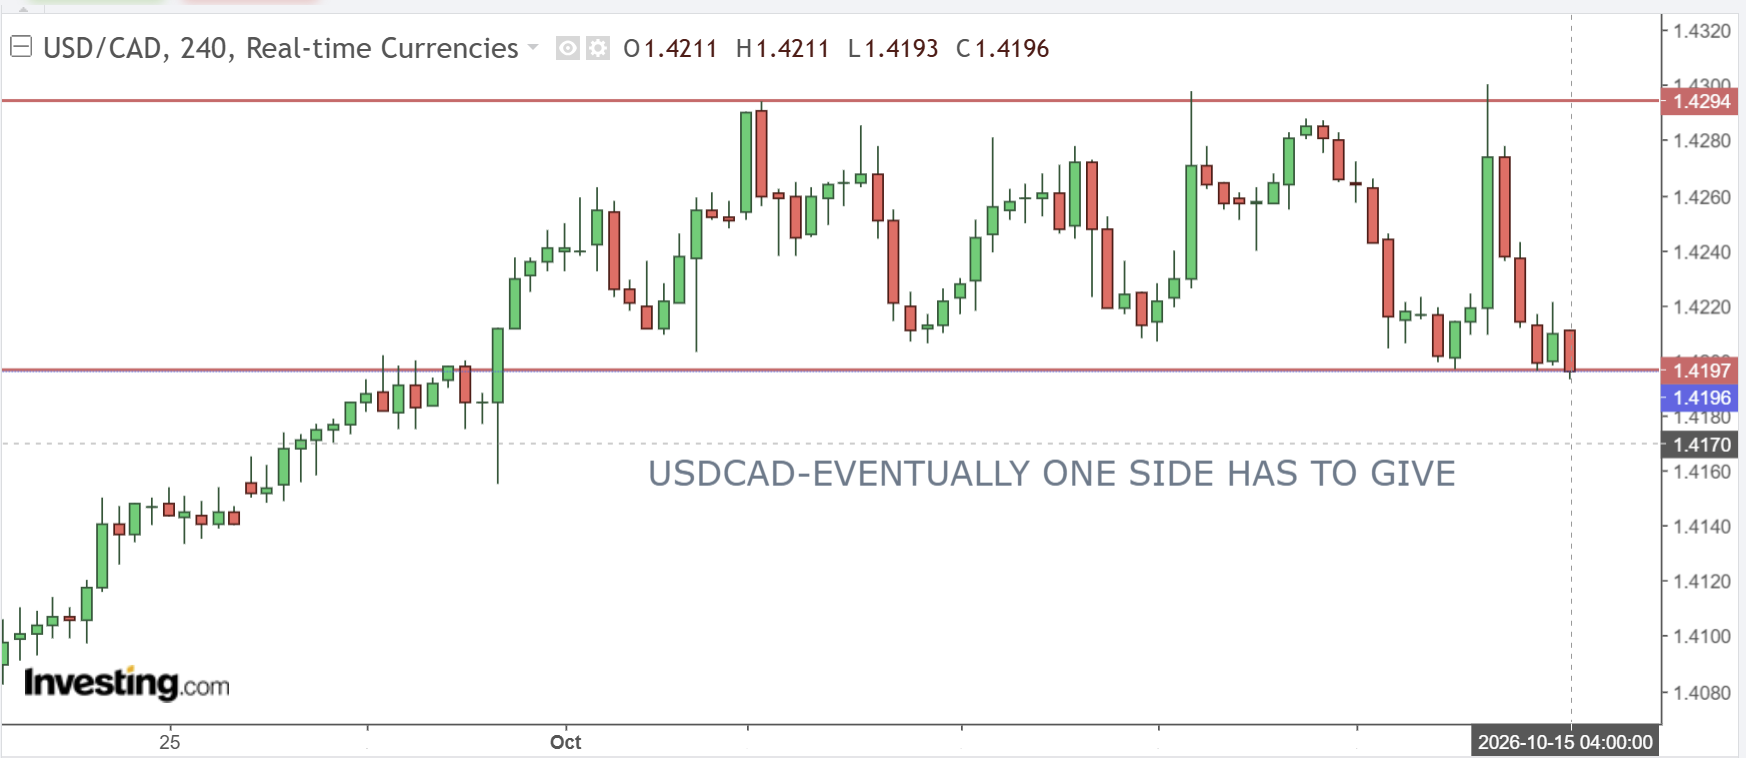
USDCAD continues to test both sides of its October range, and it is currently gnawing on support in the 1.4195 area. The intraday set-up is bearish while below 1.4240, and a decisive break below 1.4195 targets 1.4150, where the late September consolidation began. A move above 1.4240 shifts the focus to 1.4300.
Longer term, the September rally ran out of puff at the 1.4300 area and has been chewing sideways ever since. A decisive break either side of the 1.4195-1.4300 band suggests 1.4100 or 1.4400.
For today, support is 1.4190 and 1.4150. Resistance is 1.4240 and 1.4300. Today’s range 1.4150-1.4250.
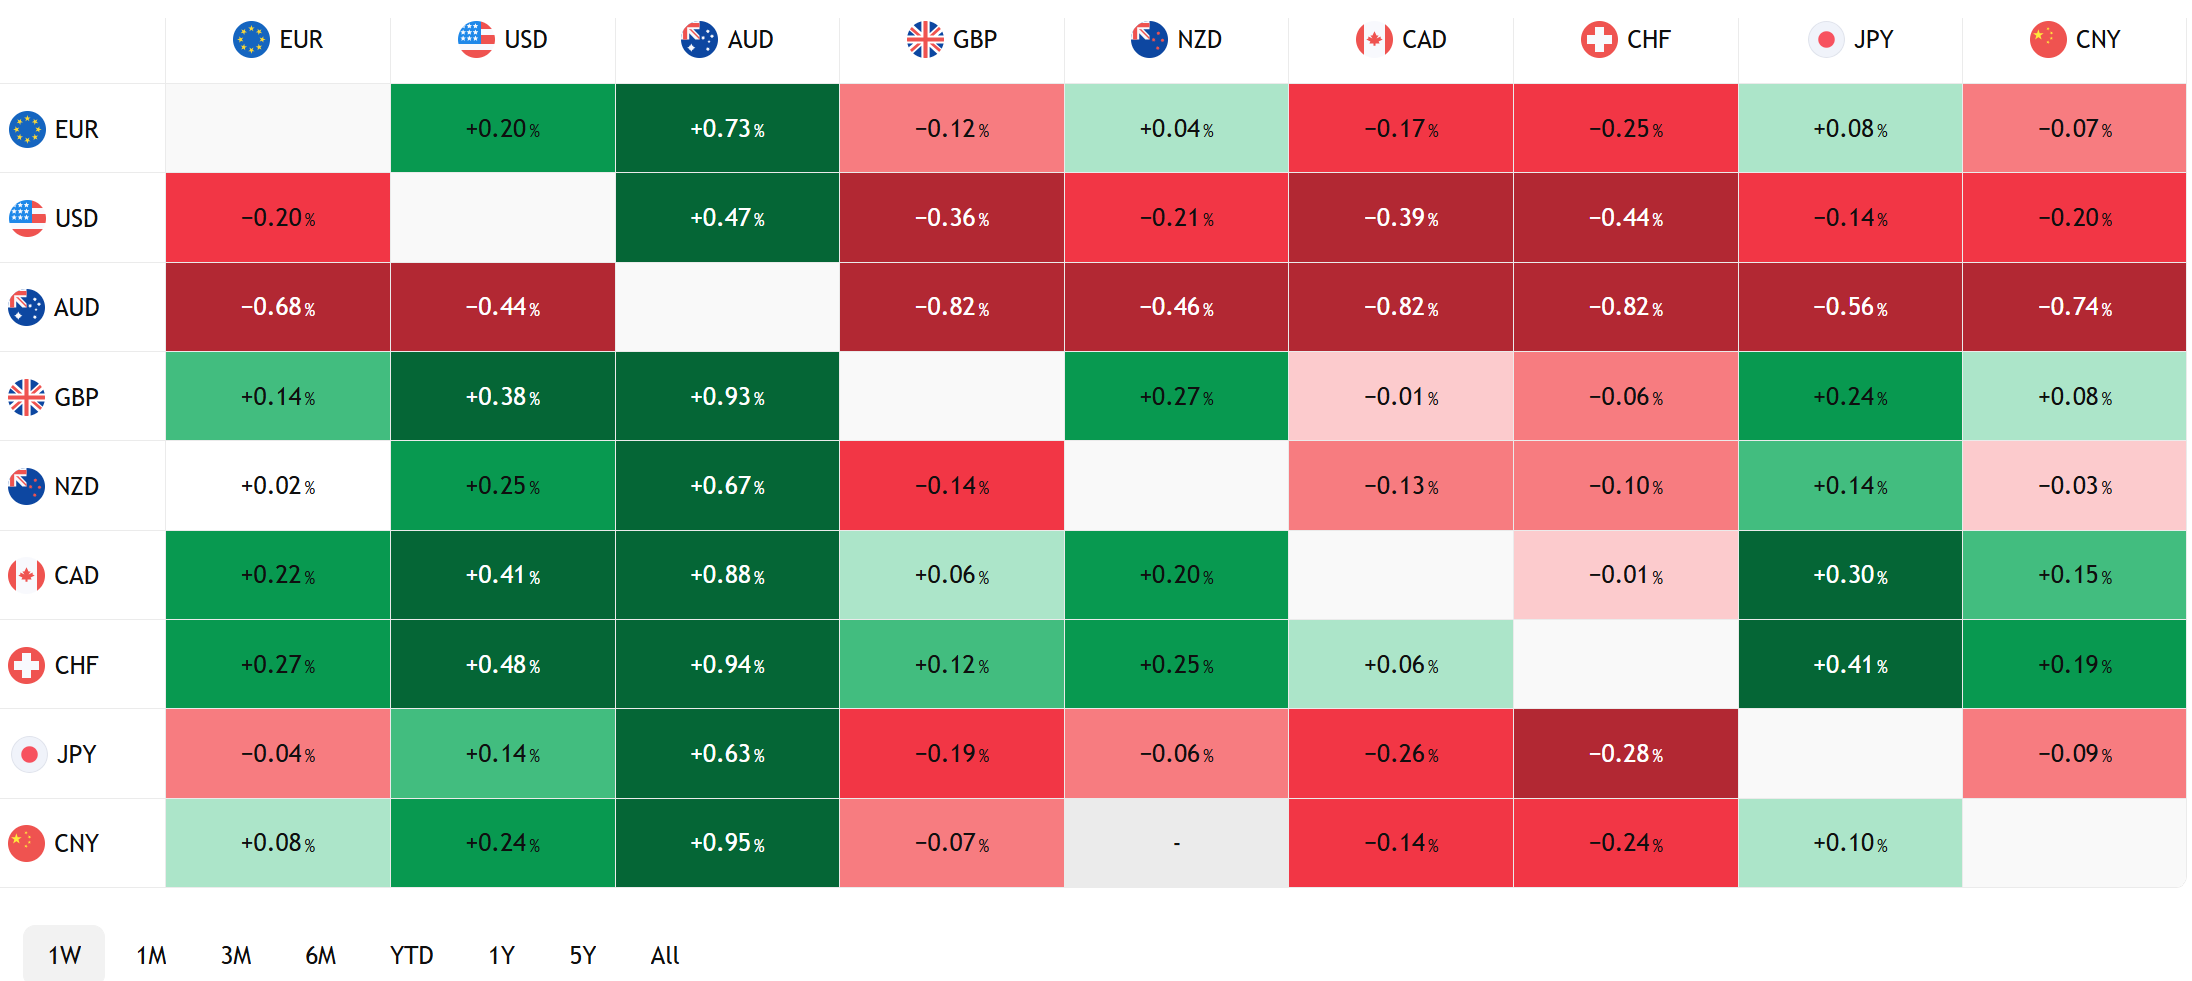
FX Heat Map
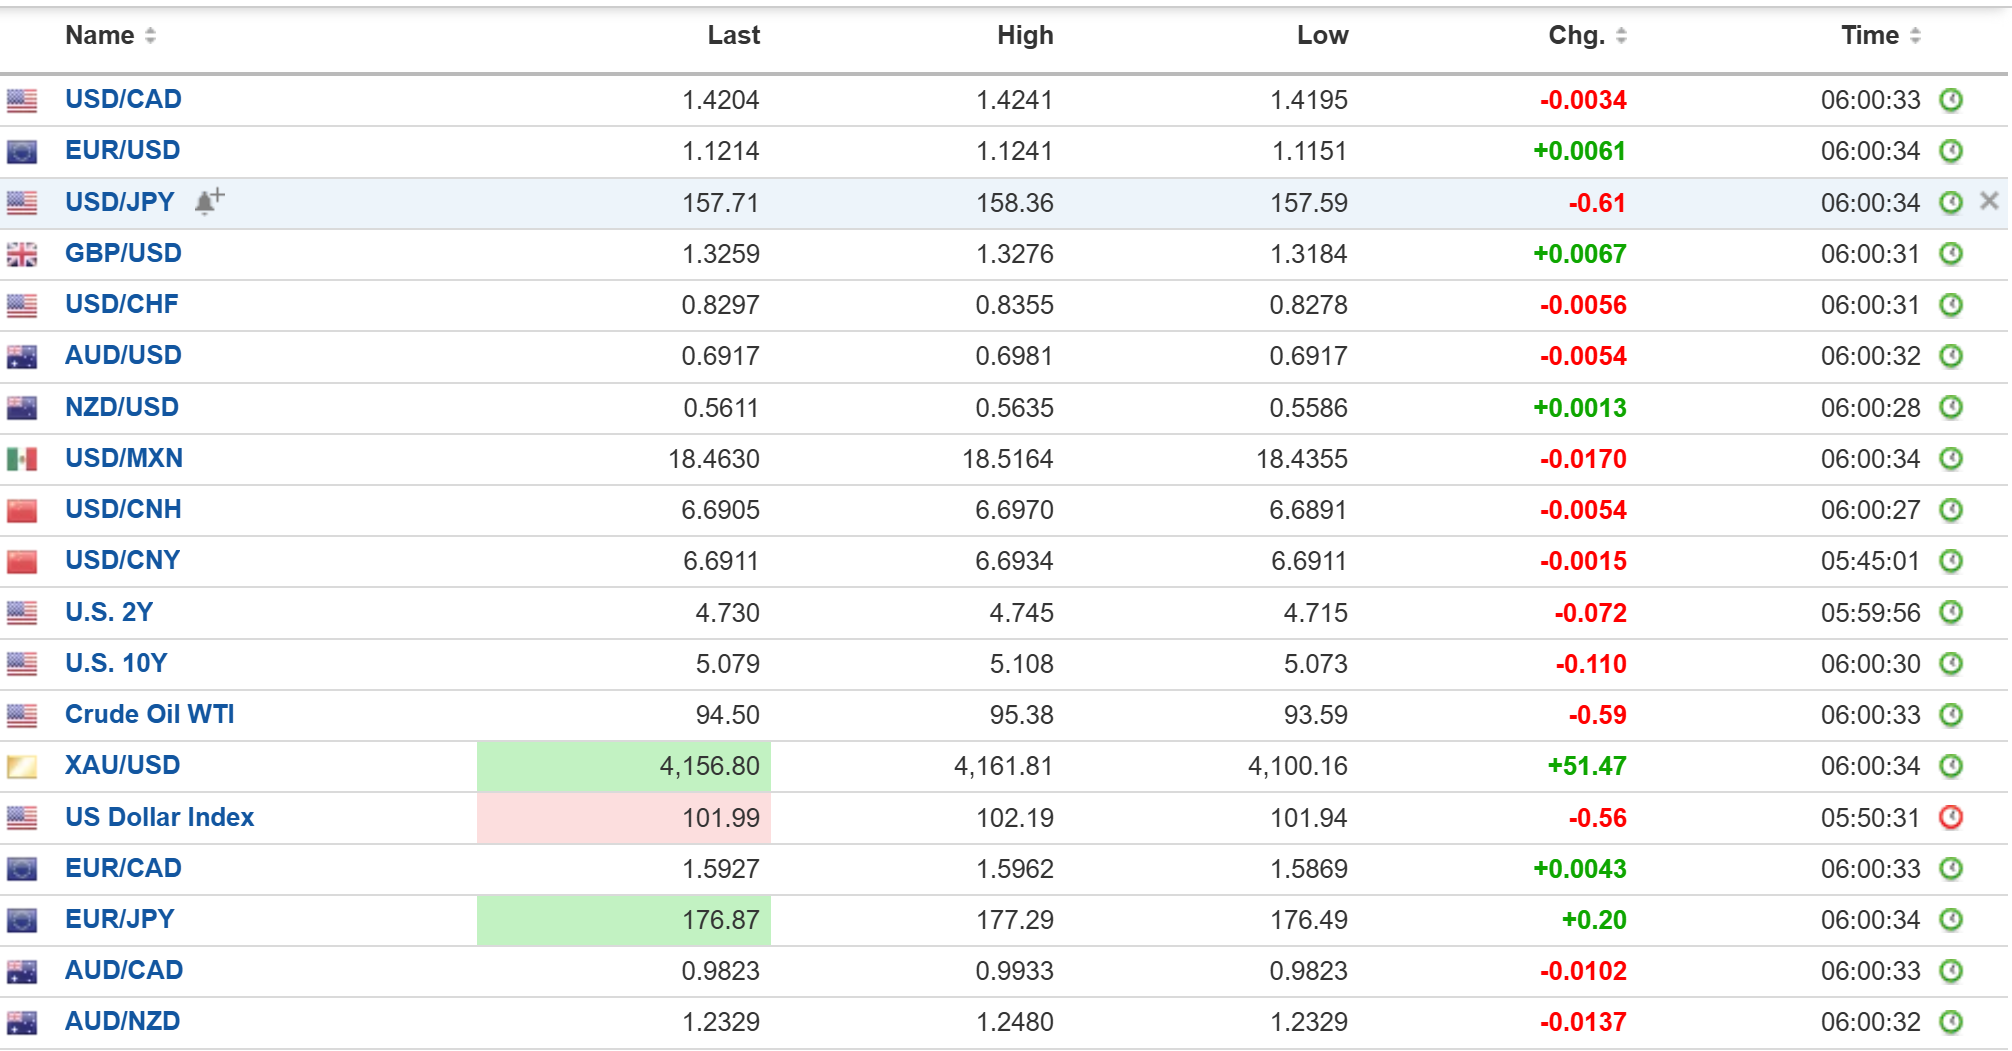
FX open high low 6:00 am
Hot and Bothered
Global markets are still suffering the fall-out from yesterday’s hotter-than-expected US inflation data and the tech stock rout that sparked a flood of safe-have demand for bonds. The USD 10-year Treasury yield poked above 5.32% in the wake of the CPI numbers then plunged to 5.073% by early NY trading today.
Fed officials did little to calm the nerves. Chicago Fed President Austan Goolsbee called the number unacceptable, and Richmond Fed President Tom Barkin said he is open to hiking this month. Futures traders are not as hawkish. The CME Fedwatch tool has the odds of an October 28 rate hike at 30%.
Taking Stock
Asian equities were mixed. The Hong Kong Hang Seng dropped 1.01%, Australia’s ASX 200 fell 0.40% while Japan’s Topix rose 1.31%.
As of 7:25 am, the UK FTSE 100 has gained 0.59%, the French CAC-40 has risen by 0.18% while the German Dax is down 0.47%. S&P 500 futures are down 0.31%, the US 10-year Treasury yield is 5.073%, the DXY is 102.02 and gold (XAUUSD) is $4,155.87.
EURUSD | Range 1.1151-1.1241
EURUSD climbed steadily through Asia and into Europe as US yields retreated and the dollar surrendered its post-CPI bounce. However ongoing French budget issues may limit gains. Eurozone Industrial production fell 1.1% y/y in August.
GBPUSD | Range 1.3184-1.3276
Cable clawed back all yesterday’s losses following better than expected economic growth in August. GDP rose 0.1% in August, beating forecasts for a 0.1% contraction and raising the odds for a November rate hike. Industrial production jumped 0.8% and manufacturing 1.2%, both beating expectations for small declines.
USDJPY | Range 157.59-158.36
USDJPY slid as falling Treasury yields and haven demand bolstered the yen, with lingering talk of Japanese intervention keeping dollar bulls honest. Traders ignored comments from BoJ board member Junko Koeda who argued that the bank should not be overly cautious about raising rates. Japan’s August industrial production fell 2.4% m/m, worse than the 1.7% drop expected. Japan’s machinery orders, capacity utilization and Industrial production data were non-factors.
AUDUSD | Range 0.6927-0.6981
AUDUSD was the night’s punching bag, sinking to the bottom of its range after Australia shed 39,300 jobs in September against forecasts for a 20,000 gain. Unemployment held at 4.7%, a five-year high, versus 4.6% expected, and a 73,700 plunge in part-time work swamped a 34,400 gain in full-time jobs. The report all but buries the case for another RBA hike, and the Asian equity rout kicked the Aussie while it was down.
USDMXN | Range 18.4355-18.5164
USDMXN is consolidating yesterday’s losses but has maintained its bullish bias after Wednesday’s CPI-driven spike to 18.6030 boosted prices to its highest level since December 2025. The softer US dollar offers some relief, but with US PPI and retail sales on deck, further downside may be limited.
CHINA
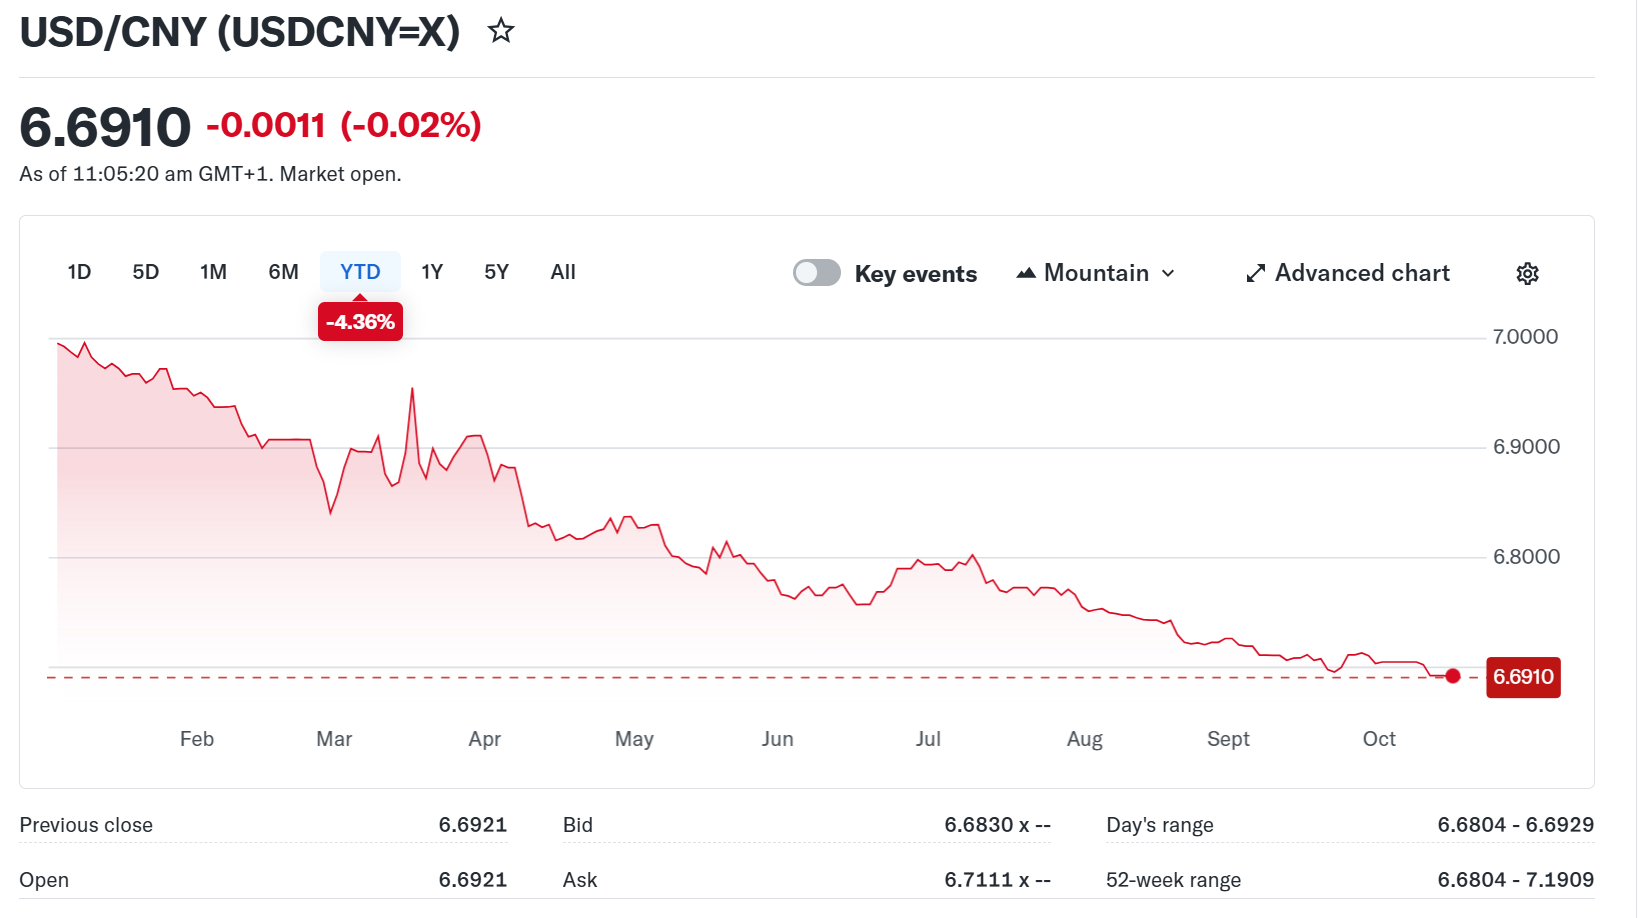
PBoC Fix: 6.7253 vs exp. 6.6973 (previous 6.7249)
Shanghai Shenzhen CSI 300 fell 1.73% to 4,439.14
The PBoC set the fix far weaker than models expected for a second straight day, a clear message that Beijing wants to slow the yuan’s steady climb.
The EU is contemplating further restrictions on Chinese trade to include scooters, furniture while Germany wants restrictions on imports of Chemicals and some mechanical engineering products.
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Business Recorder, TradingView