October 30, 2026
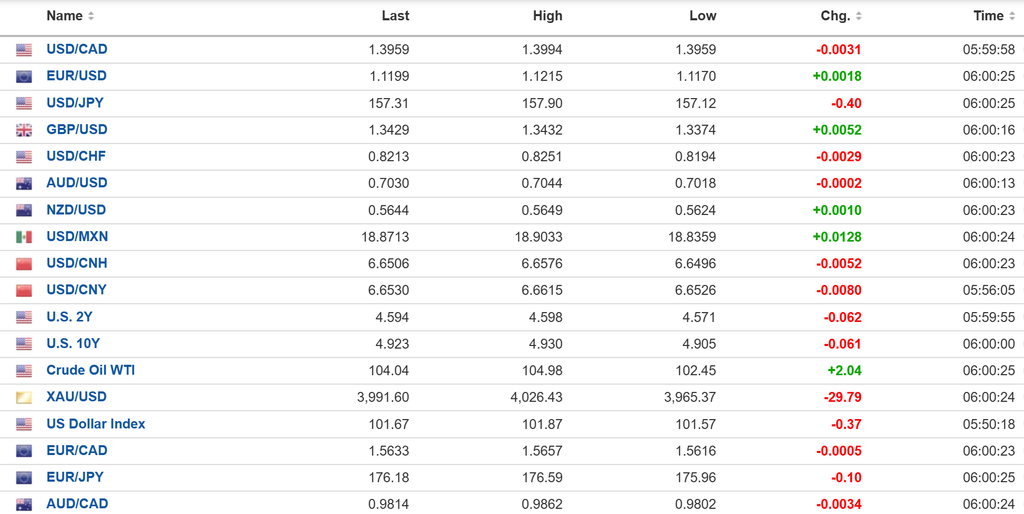
USDCAD open (6:00 am): 1.3959, overnight range 1.3950-1.3994, close 1.3991
USDCAD is caught in the throes of a downdraft that has slowly gained in intensity since the Bank of Canada and FOMC meetings Wednesday. The BoC turned hawkish without any supporting inflation data, and many major bank economists now expect two more rate hikes to follow Wednesday’s bump to 2.50%. Meanwhile, the Fed, which has ample evidence of rising inflation against a robust economic background, left its benchmark unchanged.
Consequently, CAD/US 2-year and 10-year yield differentials narrowed sharply. Three weeks ago, the CAD/US 2-year yield differential was -160.4. Today it is -125.7. The 10-year yield spread has reacted in a similar fashion, narrowing from -137.3 on October 9 to -111.8 today.
Canada’s August GDP was a disappointing 0%, unchanged from July, and below the 0.2% m/m forecast. And Stats Canada forecasts a drop of 0.1% in September. It sure makes the BoC decision to raise rates in a weakening economy look rather silly. However, the reality is that much of the weakness came from one-off factors the BoC can look through. There was a prolonged summer shutdown at a major auto plant, the winding down of 2026 Census work and maintenance outages at nuclear plants and the oil sands.
FX markets are likely to be subdued today because of the risks that the US could attack Iran on the weekend and due to caution ahead of Tuesday’s US mid-term elections.
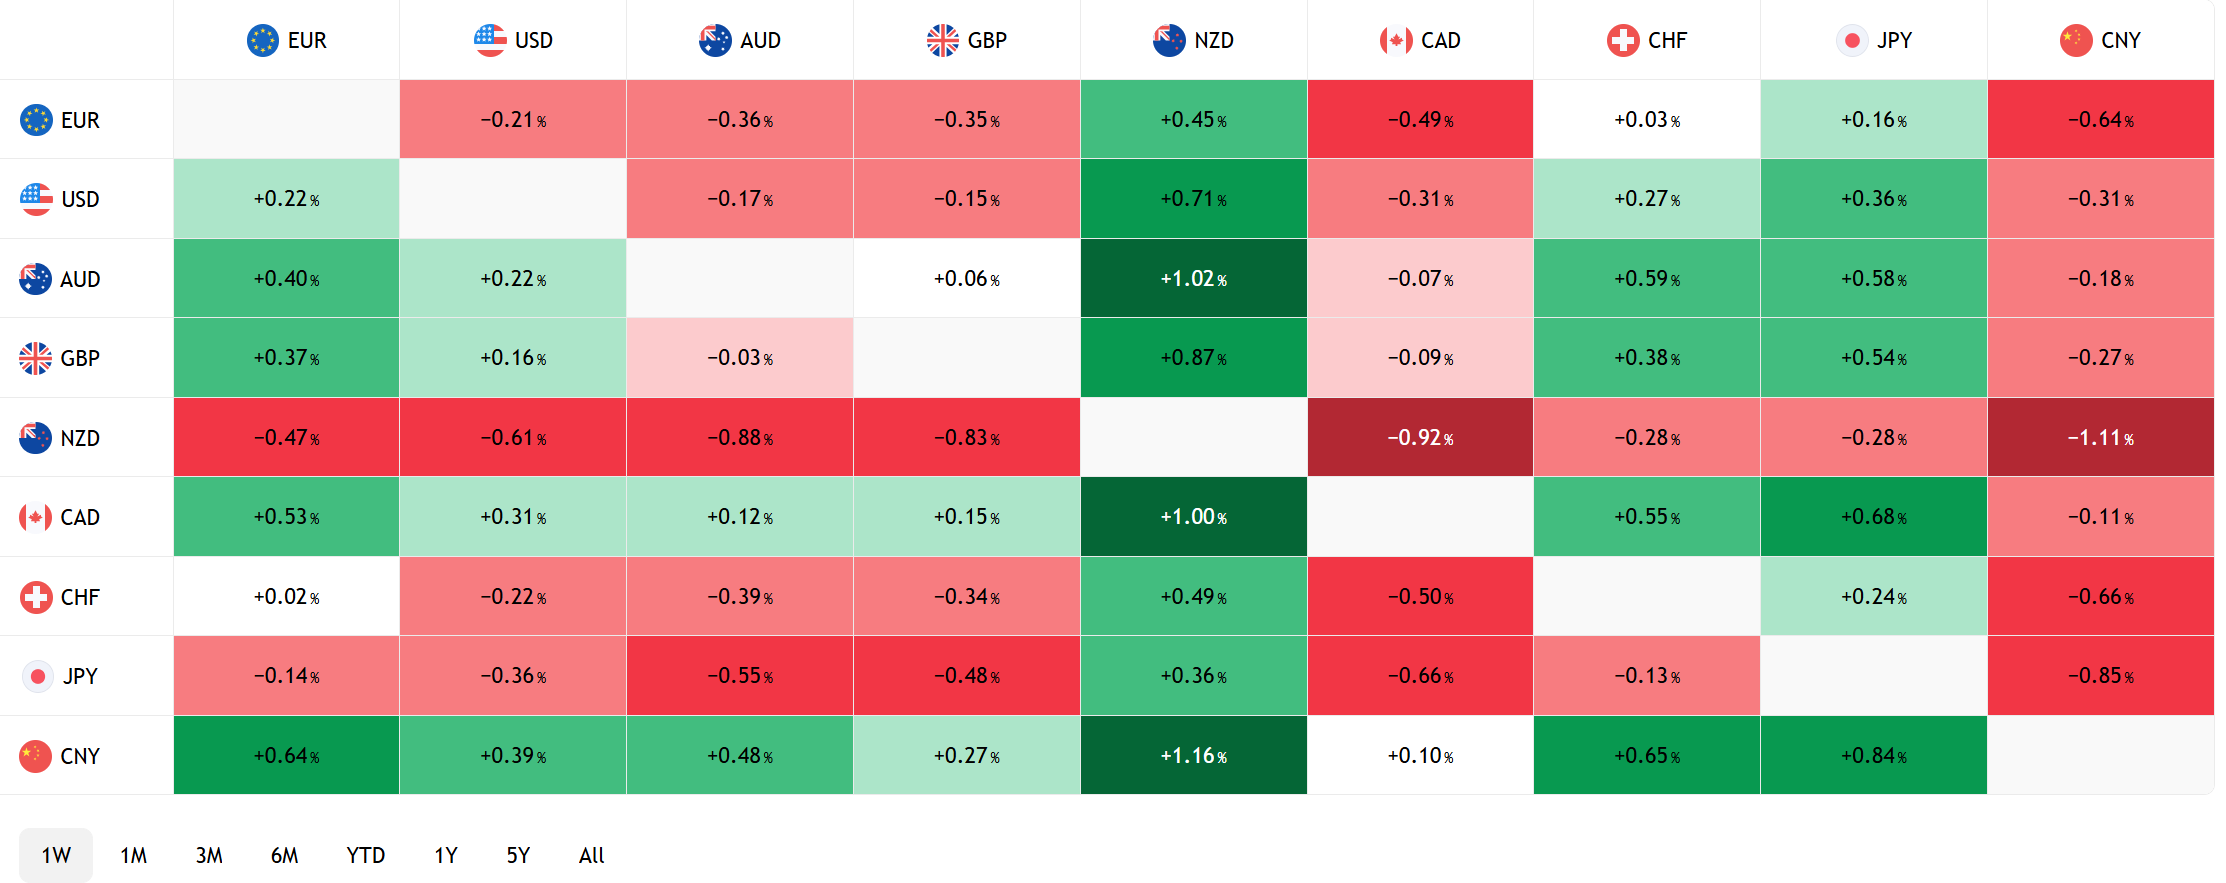
The Canadian dollar is the best-performing major G-10 currency this month (at the time of writing), rising 1.58%, while the euro is the worst, losing 1.35%.
WTI traded with a bid in a $102.45-$104.98 range overnight due to ongoing Middle East strife. The Houthis say they hit Saudi oil infrastructure, with reports naming the Ras Tanura and Rabigh refineries and an Aramco site at Abqaiq, while a tanker in the Strait of Hormuz was struck by explosives attached to a small boat. Add chatter about possible US strikes on Iran once the midterms are out of the way, and WTI is on course for a gain of roughly 14% in October, its fourth straight monthly advance.
The US data Q3 Employment Cost Index rose 0.8% q/q as expected. Later today, the Chicago PMI is due. (forecast 55.9, previous 58.8).
USDCAD Technical Outlook
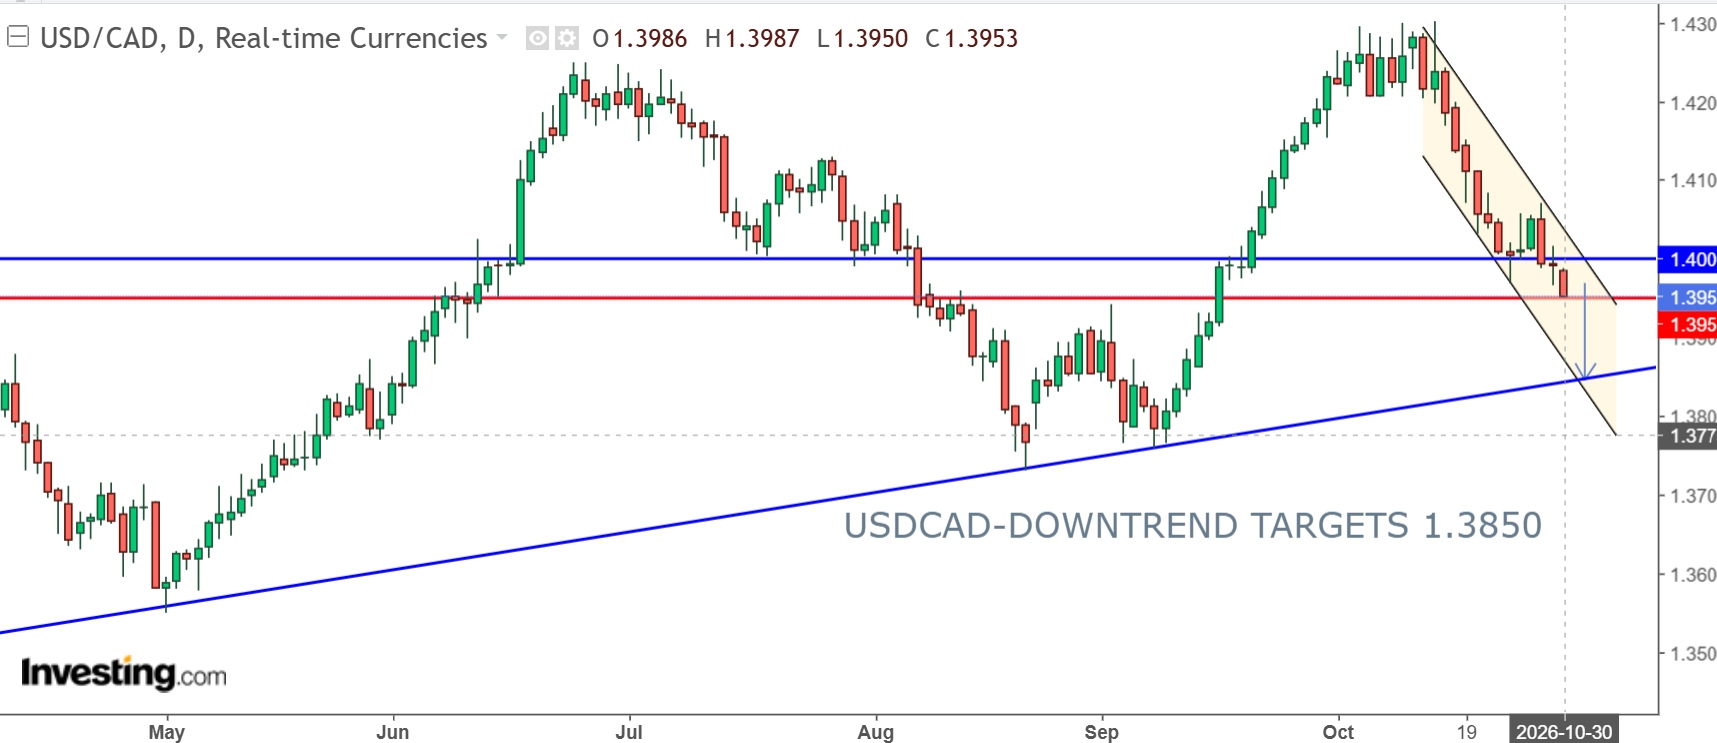
The intraday USDCAD technicals are bearish while trading below 1.3980, the 4-hour mid-Bollinger Band, after another bounce stalled near 1.4015 yesterday and prices slid to a fresh low of 1.3950 overnight. The 4-hour MACD continues to fall below its signal line, and the sequence of lower highs is intact. A break below 1.3940 targets 1.3900. A recovery above 1.3980 will shift the focus back to 1.4020.
Longer term, USDCAD is in a downtrend supported by the break below 1.4130 and then 1.4000. A decisive break below 1.3950 targets the May uptrend line which comes into play at 1.3850 and is guarded by the 200 day moving average at 1.3888.
For today, USDCAD support is 1.3940 and 1.3990. Resistance is 1.4020 and 1.4050
Today’s Range 1.3920-1.4020.
FX Heat Map
FX open high low 6:00 am
Brother, Can you Spare $6.3 Billion?
Way back when, bank robbers were once considered to be at the pinnacle of the criminal underworld. Movies have been made about the exploits of Bonnie and Clyde during the Depression era, but they were rather inept. Their heists netted them anywhere from $100 to $1,500 and once, $3,500. John Dillinger was the Connor McDavid of thieves. He managed to take around $500,000 before his career ended in a hail of bullets, in Chicago in 1934.
Reportedly, North Korean hackers just took bank robbing to stratospheric heights when they stole $6.3 billion from crypto exchange Binance. Binance said it would cover all the losses.
Taking Stock
Asian equity indexes closed mixed to higher but finished with losses for October, except for Australia’s ASX 200, which rose 1.82%. Overnight, Japan’s Topix fell 0.95%, while Hong Kong’s Hang Seng rose 1.46% and the ASX 200 gained 0.18%.
Aso of 5:35 am PT, European stocks are set to finish October higher, led by a 2.34% gain in the German DAX, a 1.33% increase in the UK FTSE 100 while the French CAC 40 is unchanged. This morning, the FTSE 100 is flat, the CAC-40 is down 0.17% and the DAX is down 0.90%. S&P 500 futures are down 1.09%, the DXY is 101.71, the US 10-year yield is at 4.926% and gold (XAUUSD) sits at $3,961.66..
EURUSD | Range 1.1170-1.1215
EURUSD had a choppy Thursday session after the ECB left rates unchanged at 2.50%, and it’s trading at its session high in NY today. ECB President Christine Lagarde, who announced her plan to resign in February, admitted during her press conference that a rate hike was discussed, which was viewed as hawkish. Analysts now expect a rate hike in December.
There was plenty of German and Eurozone economic data. Eurozone flash Q3 GDP rose 0.4% q/q (forecast 0.2% q/q, previous 0.6%).
GBPUSD | Range 1.3374-1.3433
It’s a good day to be long sterling. GBPUSD has recouped all of its October losses and is poised to revisit 1.3480. It is a bit of a relief rally thanks to the calm reception for Chancellor Healey’s Budget, which has pulled gilt yields lower. The gains are further supported by expectations of the Bank of England hiking rates to 4.00% next week.
USDJPY | Range 157.12-157.90
USDJPY dipped to 157.12 after the Bank of Japan left rates on hold and is consolidating the losses in early NY. The BoJ announced that inflation had reached its 2.0% target for the first time since 2013, which raised expectations for a rate increase in December. However, Governor Kazuo Ueda was rather non-committal. Tokyo CPI accelerated to 2.8% y/y in October from 2.7%. In addition, safe-haven demand for yen because of selling pressure in major tech stocks is weighing on USDJPY.
AUDUSD | Range 0.7018-0.7044
AUDUSD is going nowhere fast as it is caught between a softer greenback and the risk-off mood in tech, which is offset by RBA rate hike expectations next week. Q3 producer prices rose 1.1% q/q against 1.0% expected (previous 1.3%).
USDMXN | Range 18.8359-18.9033
The peso is a touch softer on the day, with USDMXN at 18.8679 after a quiet night that topped out at 18.9033. Mexico Q3 GDP is expected at 0.7% q/q (previous 1.4%) and 2.5% y/y (previous 2.1%)
CHINA
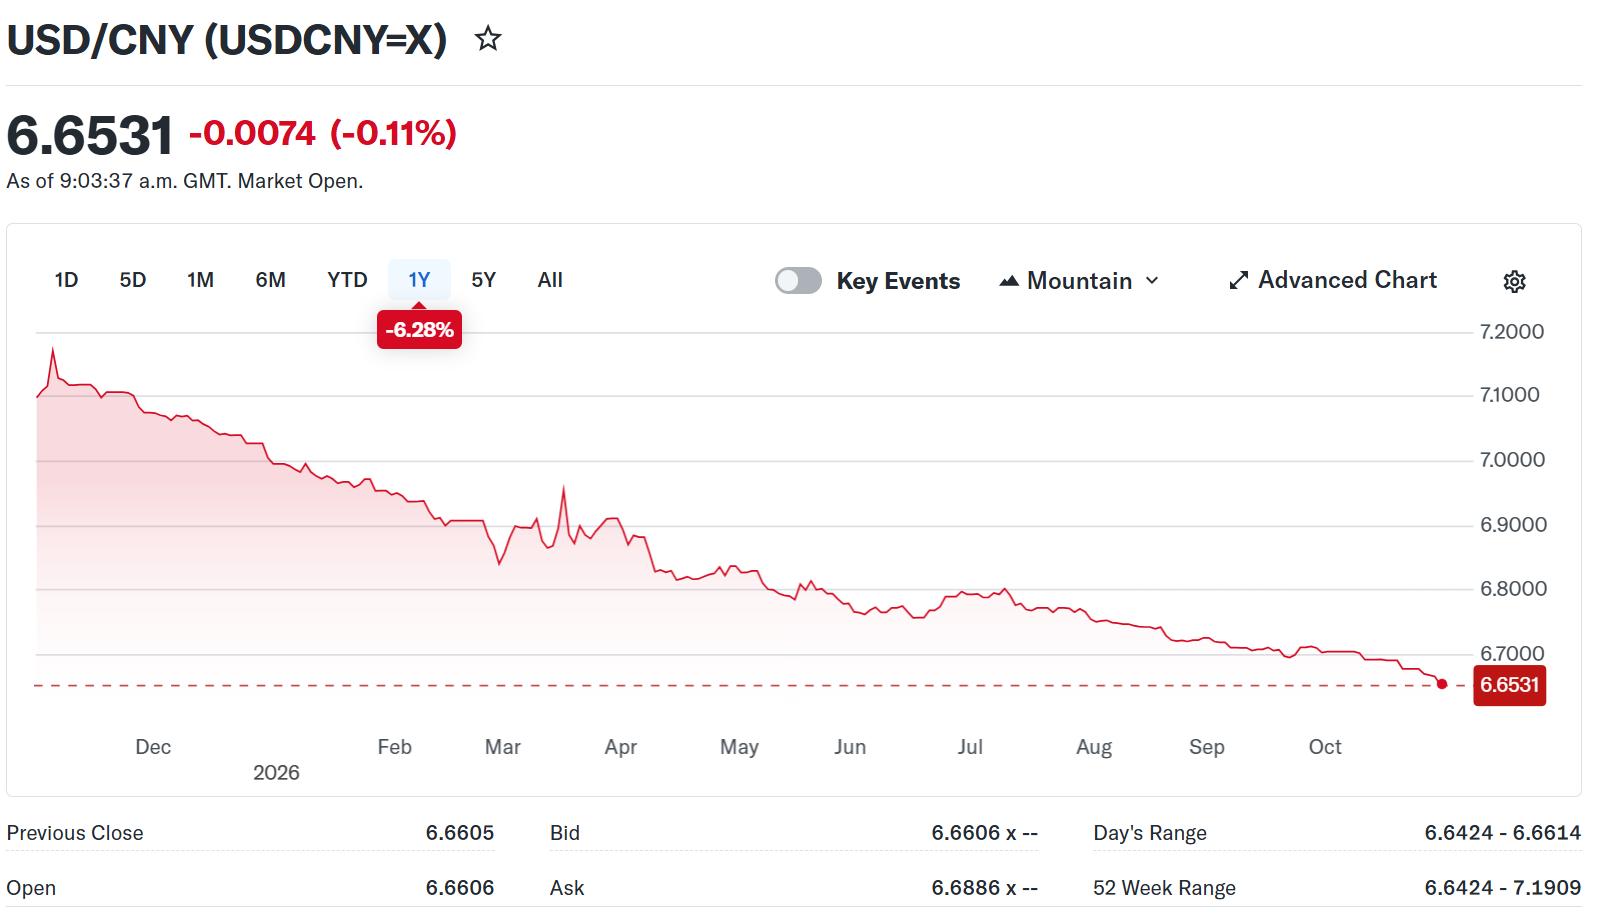
PBoC Fix 6.7138 vs exp. 6.6548 (prev. 6.7147)
Shanghai Shenzhen CSI 300 fell 1.39% to 3,985.50
The CSI 300 sank to a one-year low, on track for a 12th straight weekly decline after losing about 14% over three months, as the global retreat from AI names hit mainland tech. Traders were also spooked by Xi Jinping’s purge of 33 officials of the Chinese Communist Party’s Central Committee.
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Tradingpedia, Business Recorder, TradingView