November 2, 2026
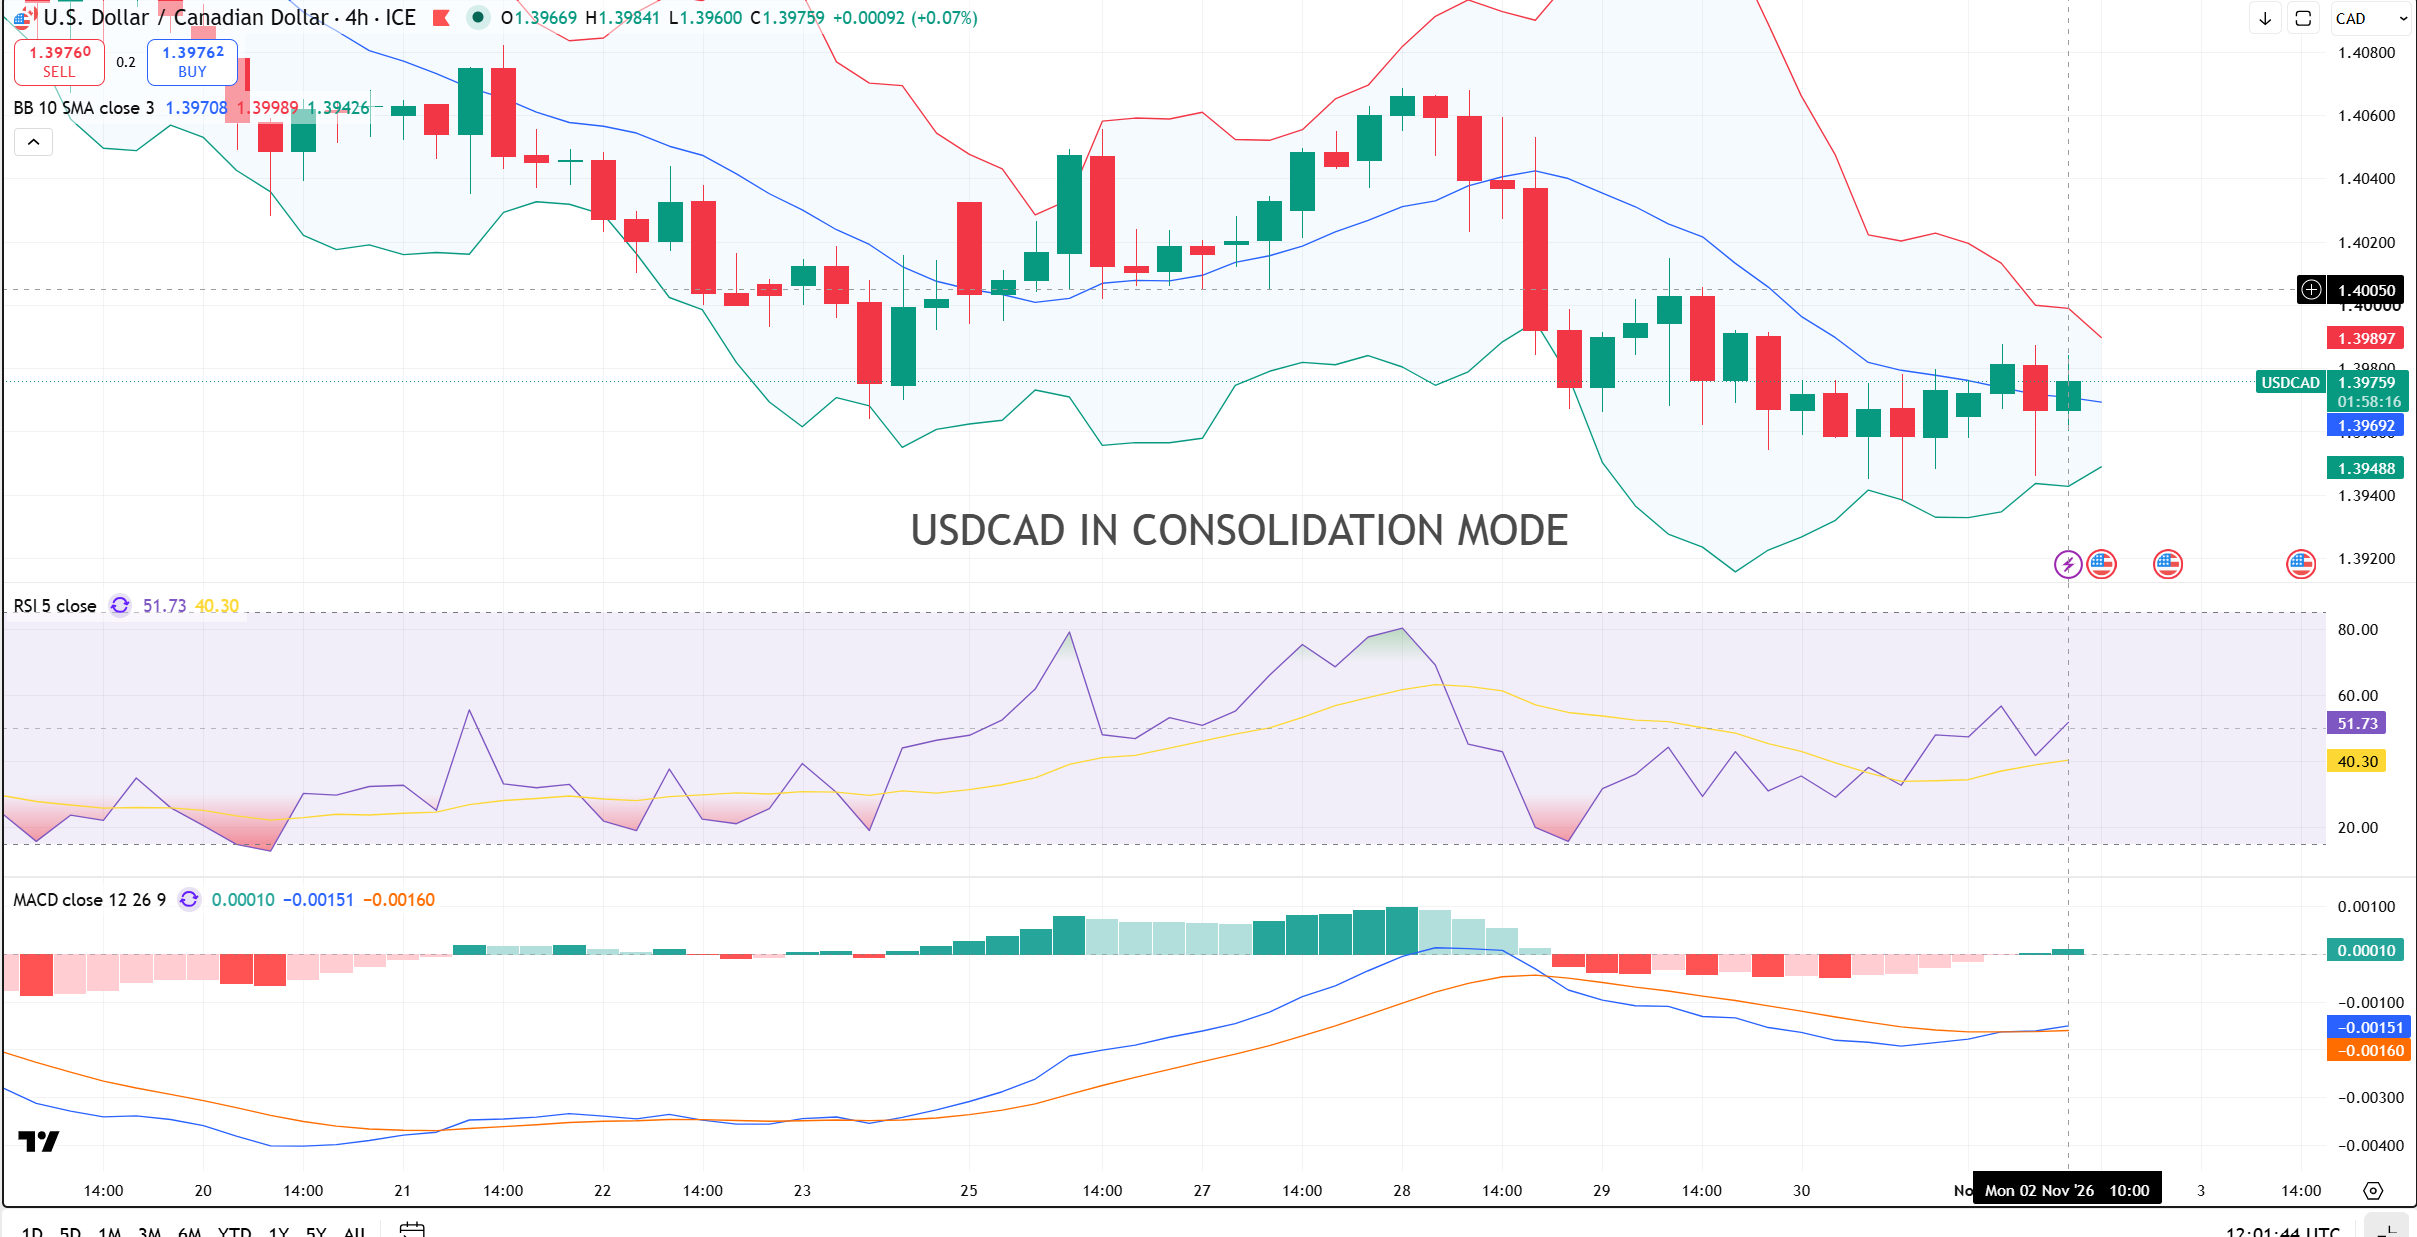
USDCAD open (6:00 am): 1.3975, overnight range 1.3950-1.3988, close 1.3975
USDCAD survived last week’s drama and equity market meltdown on Friday and managed to close-out October with a 1.85% gain, against the greenback handily winning the G-10 major currency performance sweepstakes.
It will be a drama filled week and likely a very volatile one for FX. FOMC officials, Dallas Fed President Lorie Logan and St Louis Fed President Alberto Musalem chirped on Friday about the need for higher rates with Logan advocating two 25 bp hikes.
Wall Street will be attempting to claw back Friday’s losses and to convince themselves that the rout was just an overdue correction to generously valued stocks and not something more ominous.
Canadian dollar traders will looking to hear how Governor Tiff Mackelm justifies the latest interest rate hike when he testifies before the House of Commons finance committee.
Other than Macklem, Tuesday will largely be a write off as America will be fixated on the outcome of the mid-term elections
Trump and Prime Minister Carney have reportedly been having great trade discussions Sunday Trump announced (about Canada) They’re going to build the Keystone Pipeline. They’re going to pay for it. … We’re going to give them the route, and it’s largely been determined.” Apparently, Trump believes Canada will gratefully except an offer to spend US$10 billion to build a pipeline to sell oil to American’s (who do not need anything from Canada), that is already discounted by about $17.00/barrel.
WTI dropped sharply, falling from $104.95 on Friday to $99.34 today on hopes for end to the US/Iran war. Iran’s foreign minister reportedly said that talks were making progress. Meanwhile Opec announce that production quotas would remain unchanged.
Today’s Canadian data includes, S&P Global Manufacturing PMI (forecast unchanged at 56).
USDCAD Technical Outlook
The intraday USDCAD technicals are neutral, with prices in a tight 1.3944-1.3990 range since Thursday. A break below 1.3945 targets 1.3900. A recovery above 1.3990 will shift the focus to 1.4020.
Longer term, USDCAD is in a downtrend, confirmed by the breaks below 1.4130 and then 1.4000, and it remains below the 100-day moving average at 1.4047. The daily RSI is becoming which may slow the descent. A decisive break below 1.3940 targets the May uptrend line, which comes into play at 1.3850 and is guarded by the 200-day moving average at 1.3888.
For today, USDCAD support is 1.3940 and 1.3910. Resistance is 1.3990 and 1.4020.
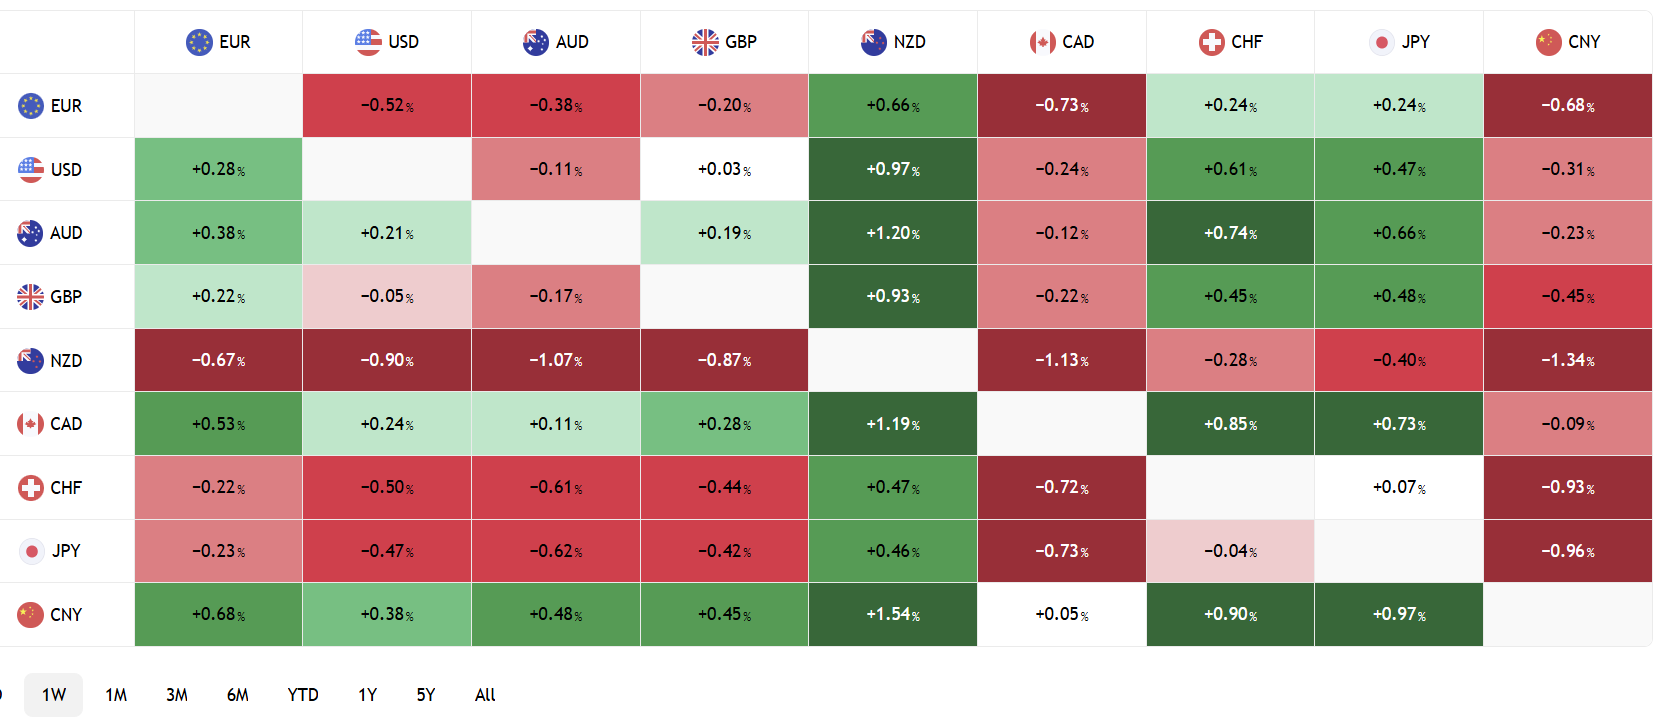
FX Heat Map
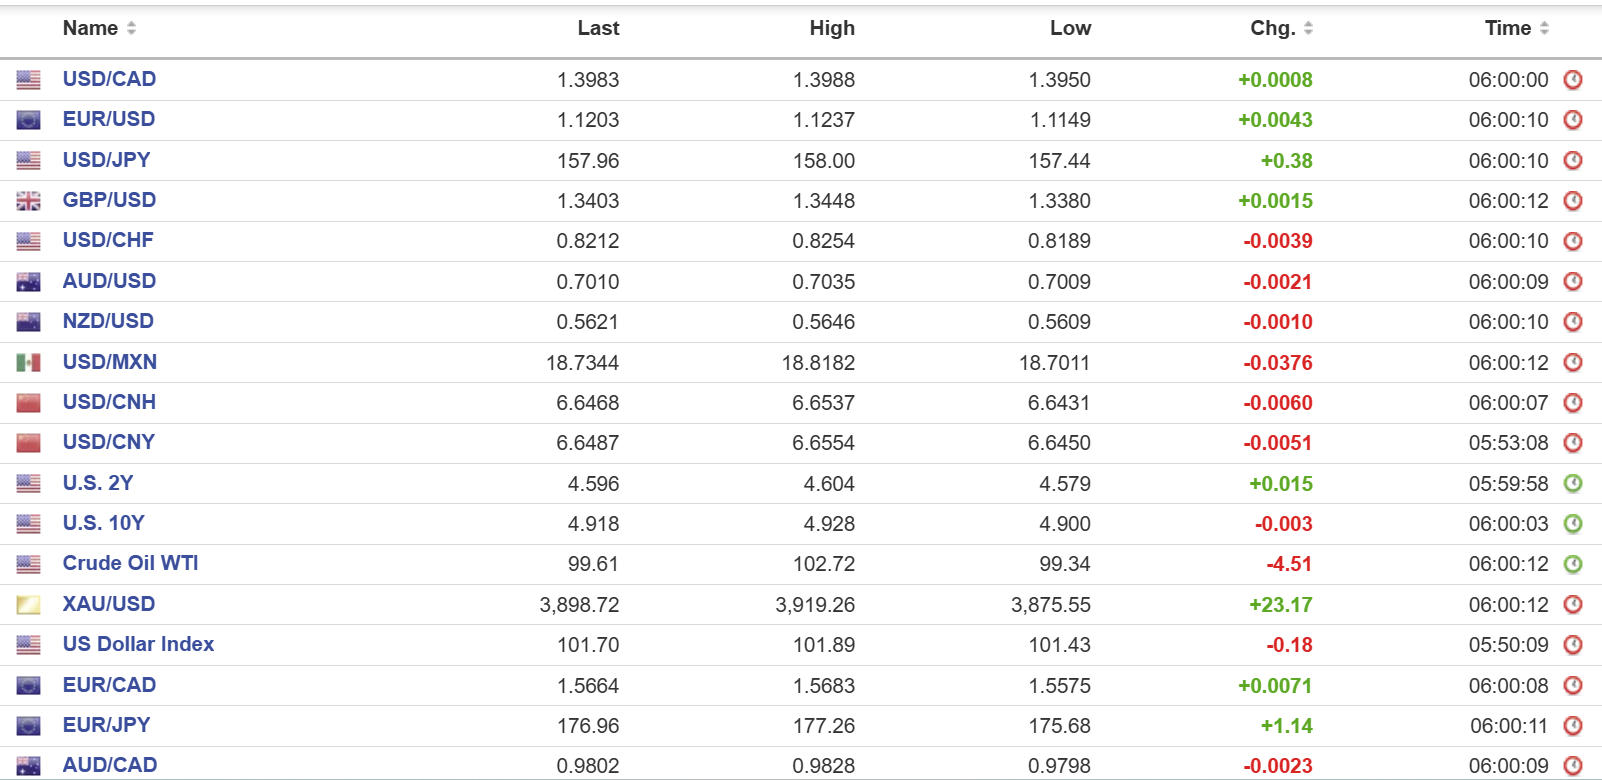
FX open high low 6:00 am
Monday Morning Malarky
Friday was ugly for anything with a chip in it but this morning, futures have clawed back some ground ahead of Apple’s numbers after the close today, War and Peace is not just a classic novel but the state of news around the Middle East. Iran insists Qatar-mediated talks are moving forward, yet Trump claims to be undecided about renewing attacks after the mid-terms.
Today’s US data includes ISM manufacturing PMI for October (forecast 54.7 vs September 54.5) Fed-speak from and Chicago Fed President Goolsbee.
Taking Stock
Asian equity markets closed lower except for those in China and Hong Kong. The Hang Seng gained 0.42% while Japan’s Topix lost 0.88% and Australia’s ASX 200 fell 0.58%.
As of 5:50 am PT, European markets are modestly higher except the UK FTSE 100, which is down 0.16%. The French CAC -40 is up 0.27% and the German DAX has gained 0.24%. S&P 500 futures are up 0.57%, the DXY is 101.55, the US 10-year Treasury yield is 4.903% and gold (XAUUSD) is at $3,943.03.
EURUSD | Range 1.1149-1.1237
EURUSD recouped all Friday’s losses, and then some due to a positive shift in risk sentiment. Increased chatter around a diplomatic solution to US and Iran hostilities knocked crude prices lower which helped European equity markets reverse some of Friday’s slump and underpinned the single currency.
Friday, Fitch ratings revised France’s outlook to negative from stable while affirming its Long-Term issuer default rating at A. Earlier, Moody’s left its France rating unchanged.
GBPUSD | Range 1.3380-1.3448
Cable peaked in Europe after UK manufacturing PMI was confirmed at 52.8. Rob Dobson, Director at S&P Global Market Intelligence, said, “Rates of growth in output and new orders both gathered pace in October, as companies responded to signs of improving demand in both domestic and overseas markets.” The Bank of England is expected to hike rates by 25 bps to 4.00% on Thursday.
USDJPY | Range 157.44-158.00
USDJPY is flirting near its overnight peak in early New York trading and ignored the drop in crude prices. The greenback is in demand because of the recent Fed rate hike, which has been followed with hawkish comments from some policymakers compared to BoJ Governor Kazuo Ueda’s wishy-washy outlook.
AUDUSD | Range 0.7008-0.7035
The Aussie is trading defensively despite the unanimous expectations for the RBA to raise rates by 25 bps tomorrow to 4.85% and fears that inflationary pressures may lead to additional increases. The monthly Inflation gauge rose 0.5% m/m in October.
USDMXN | Range 18.7011-18.8182
USDMXN trades choppily but with a negative bias due to modestly improved risk sentiment weighing on the greenback. Banxico is expected to leave its benchmark rate unchanged at 6.5% at Thursday’s monetary policy meeting.
CHINA
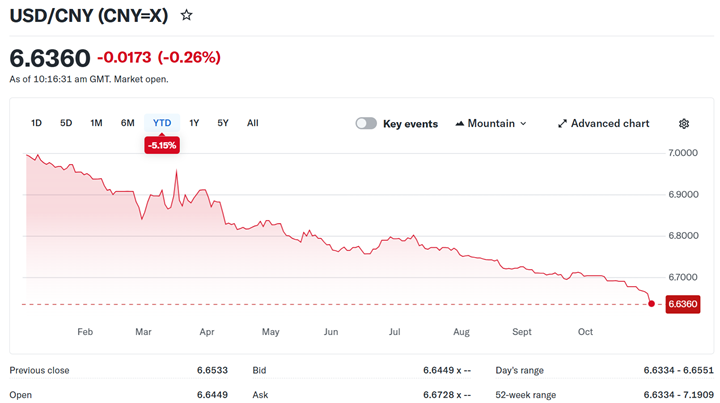
PBoC Fix 6.7146 vs exp. 6.6625 (prev. 6.7138)
Shanghai Shenzhen CSI 300 rose 0.79% to 4,016.92
China NBS October Manufacturing PMI is 49.3 (forecast 50.0 , previous 50.1) while Non-Manufacturing PMI is 49.7 vs forecast 50.5 (September 50.2)
Chinese RatingDog October Manufacturing PMI 52.0 (forecast 51.6, previous 52.1)
The PBoC’s latest measures aim to stabilize equity markets, limit capital outflows and improve monetary-policy transmission, supporting yuan stability and financial confidence. However, they represent structural reforms rather than meaningful economic stimulus.
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Tradingpedia, Business Recorder, TradingView