November 18, 2026
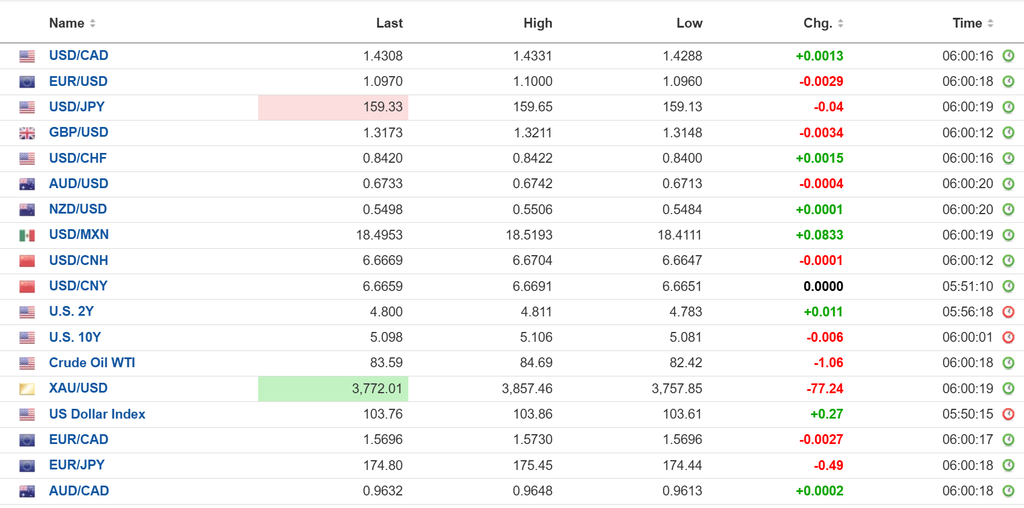
USDCAD open (6:00 am): 1.4308, overnight range 1.4288-1.4331, close 1.4300
USDCAD continued to scratch out gains overnight. Downgraded bets for a follow-up Bank of Canada rate hike because of tame inflation which contrasts against an almost guaranteed Fed rate hike in December, alongside mild risk aversion is boosting safe-haven demand for greenbacks.
Canada and US trade is on the agenda today with Prime Minister Mark Carney meeting Trump in Shenzhen, China. The meeting follows Canada and China announcements about expanding their bilateral trade relationship. China will suspend tariffs on some Canadian agricultural and seafood products while Canada will extend existing tariff exemptions on some steel and aluminum products.
WTI traded in a $82.42-$84.69 range which is a tad surprising in light of the latest US air strike on an Iranian missile site and Iran’s attack on a US military base in Kuwait. Traders ignored the war news and focused on the latest American Petroleum Institute numbers. API showed a 5.3-million-barrel jump in crude stocks last week plus a 5.1 million barrel jump in gasoline.
Canada New Housing Price Index was unchanged at -0.2% m/m in October. US Housing Starts rose 9.9% (September *7%) and October Building Permits are -7.4% compared to -0.4% in September.
USDCAD Technical Outlook
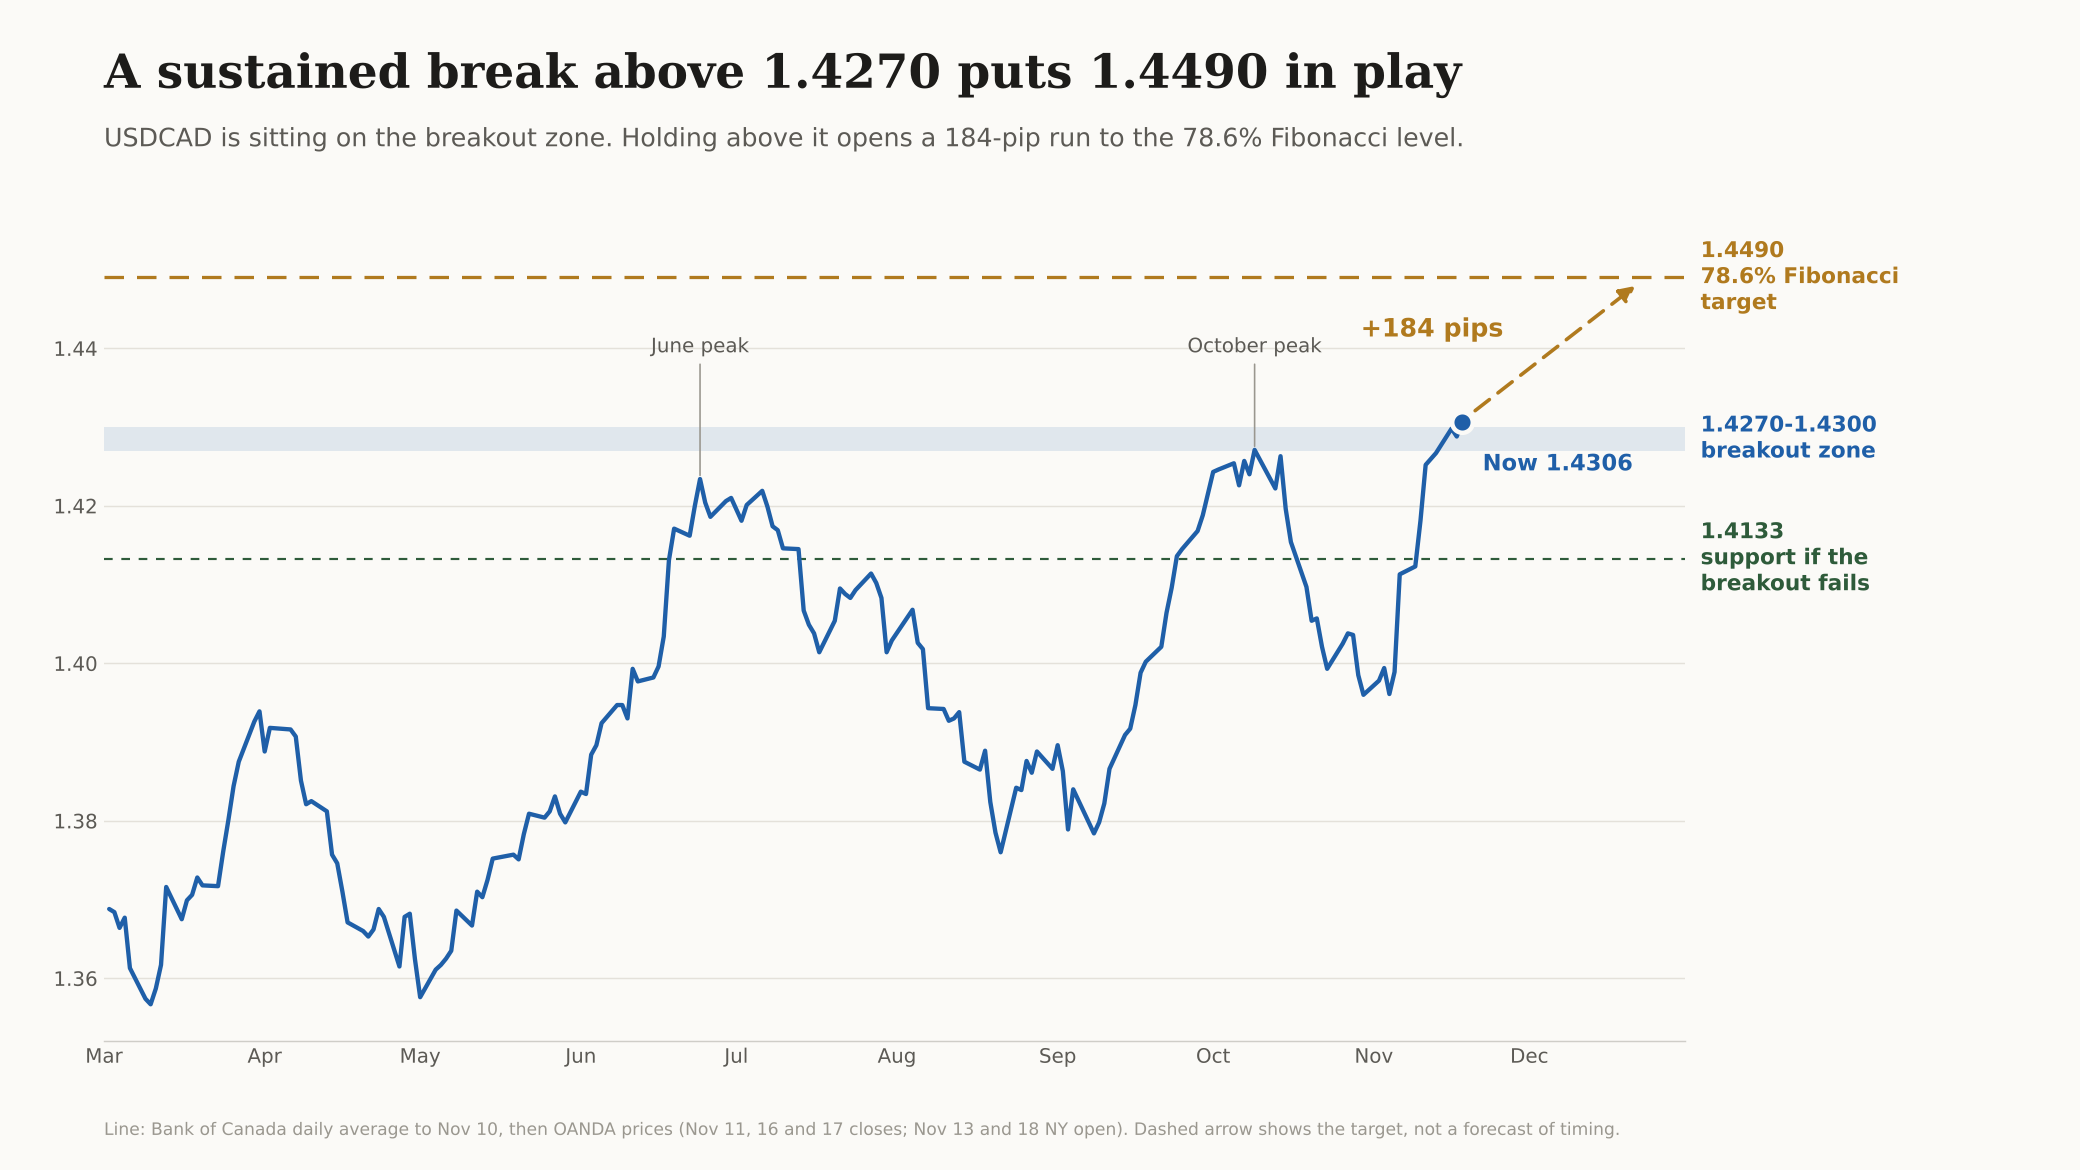
The intraday USDCAD technicals are bullish while trading above 1.4270. A break above. 1.4350 targets 1.4400. A drop below 1.4270 shifts the focus to 1.4130..
Longer term, USDCAD needs a daily close above 1.4300 for a few days in a row to confirm a breakout. The trend is still firmly bullish, with prices well above the 100-day moving average at 1.4048 and the 200-day at 1.3924. However, the daily RSI has reached and extreme oversold level which warns of a pullback is required to cool the RSI’s to neutral. A daily close above 1.4300 would open 1.4510 and then the February 2025 tariff peak at 1.4795. A failure would expose 1.4130.
For today, USDCAD support is 1.4280 and 1.4250. Resistance is 1.4330 and 1.4370.
Today’s Range 1.4280-1.4340
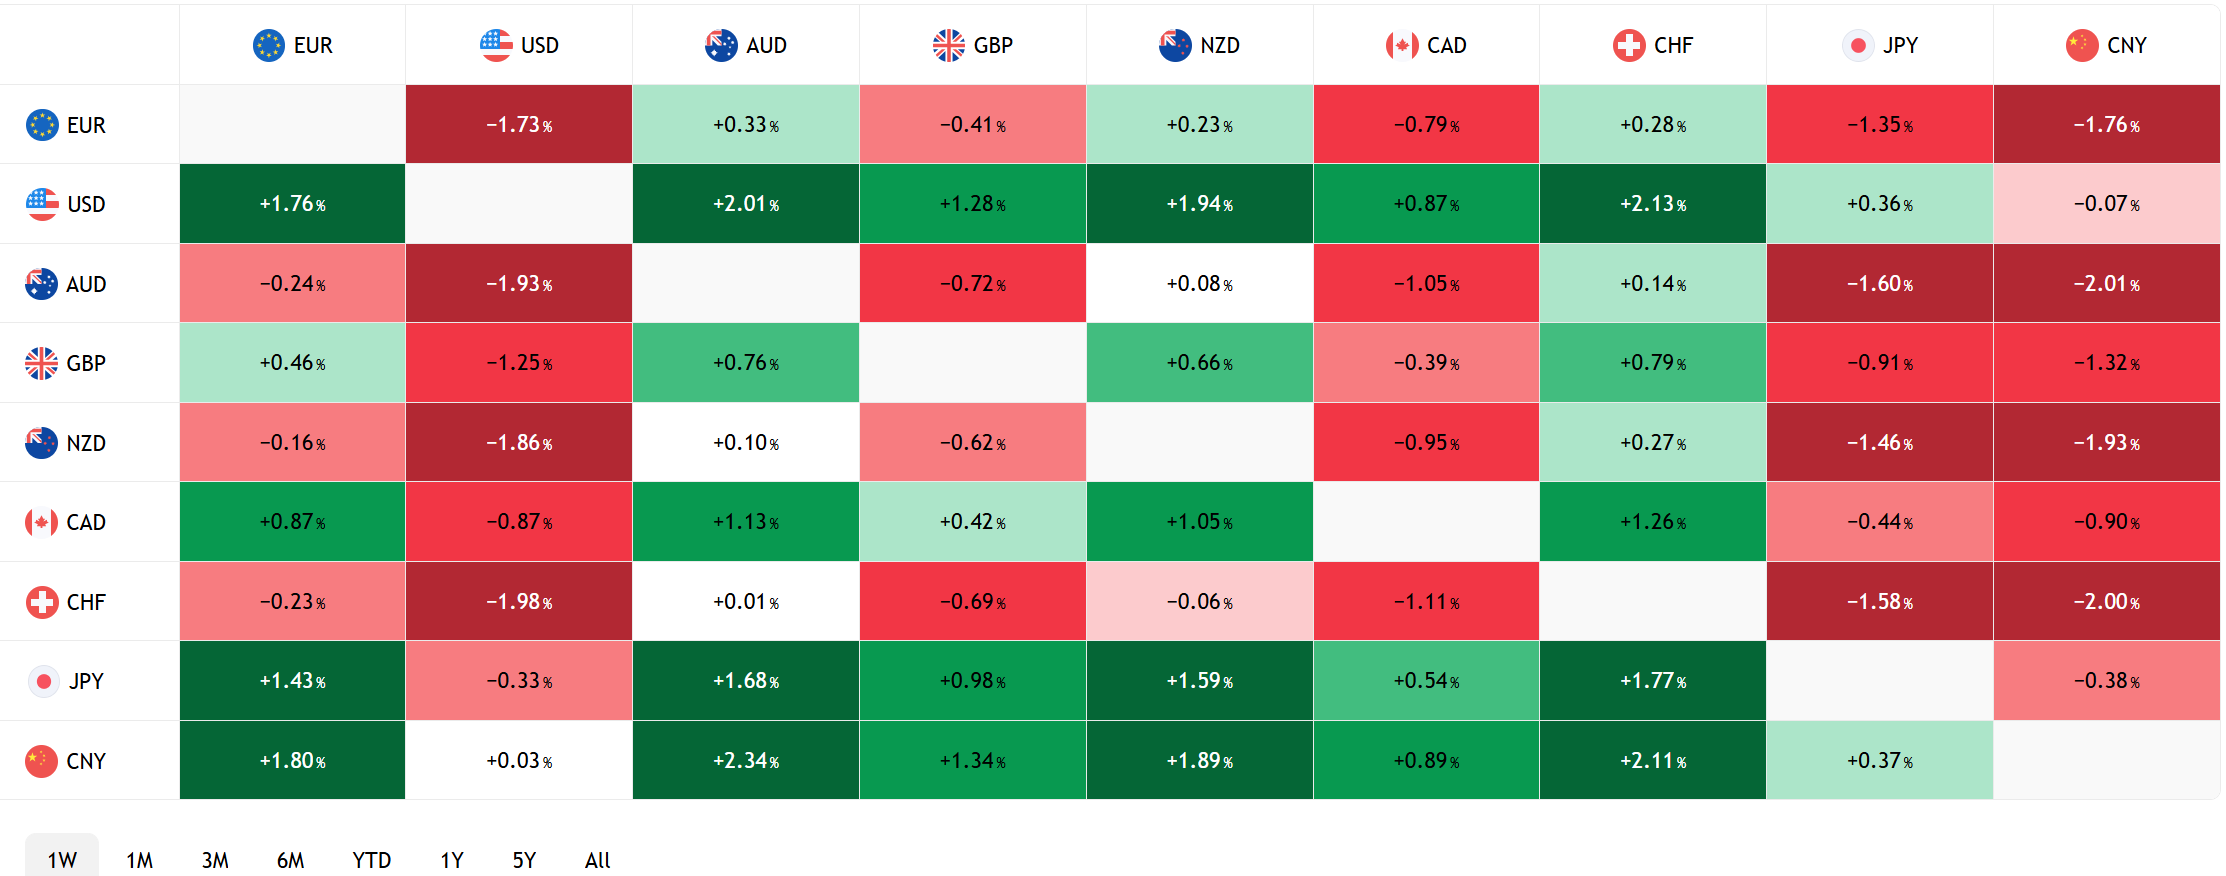
FX Heat Map
FX open high low 6:00 am
Minutes to Midnight
The FOMC minutes from the October 28 meeting are due and will likely be a non-event. A flood of Fedspeak and robust data since the meeting has convinced traders that a December rate hike is a foregone conclusion and another two 25 bp increases are in the pipeline.
San Francisco Fed President Mary Daly, Vice Chair for Supervision Michael Barr, NY Fed President John Williams and Minneapolis Fed boss Neel Kashkari are talking today.
Taking Stock
Asian markets closed lower. Japan’s Topix fell 0.42%, Hong Kong’s Hang Seng lost 0.91% and Australia’s ASX 200 fell 0.69%.
As of 5:35 am, the German DAX is down 0.41%, the French CAC-40 is down 0.32% and the UK FTSE 100 index has lost 0.54%. S&P 500 futures are up 0.24%, the US 10-year Treasury yield is 5.11%, the DXY is 103.80 and gold (XAUUSD) is $3,779.38..
EURUSD | Range 1.0953-1.1000
EURUSD is trading defensively due to broad US dollar strength. Traders believe that the Fed has begun a prolonged tightening cycle, while at the moment the ECB is in the “one-and-done” camp. The ongoing drama around French finances is another negative for the single currency, as is the mixed European Commission Autumn forecast. The Commission lifted its 2026 GDP growth forecast to 1.2% from 0.9% and raised its inflation forecast to 3.2%. The October HICP inflation number released today was a tad higher at 2.6% y/y, compared to 2.5% last month.
GBPUSD | Range 1.3148-1.3211
GBPUSD traded lower due to broad US dollar strength and domestic data. October CPI came in at 3.6%, below the forecast but above the 3.5% seen in September. Services inflation held at 3.7%, and core inflation stayed at 2.8%. As a result, while a back-to-back 25 bp hike to 4.25% in December remains the base case, today’s data takes the urgency out of aggressive, multi-hike tightening.
USDJPY | Range 159.13-159.65
USDJPY drifted higher on steady to firm US Treasury yields and a barrage of hawkish Fedspeak in recent days. However, gains were hampered by fresh chatter threatening intervention and BoJ Governor Ueda advocating rate hikes to anchor underlying inflation. October exports jumped 20.5% from a year earlier to a record on semiconductor demand, but the trade deficit still widened by 58%.
AUDUSD | Range 0.6713-0.6742
AUDUSD traded lower due to soft commodity prices, including iron ore, and a generally strong US dollar. Australia’s wage price index rose 1.1% in the third quarter, beating the 0.9% forecast, but the news was ignored as much of the jump came from the annual award increase.
USDMXN | Range 18.4111-18.5882
USDMXN traded higher because of softer crude prices and a strong US dollar. Deputy Governor Galia Borja said that the duration of the pause is not written in stone. Meanwhile, the most recent inflation data muddies the waters.
CHINA
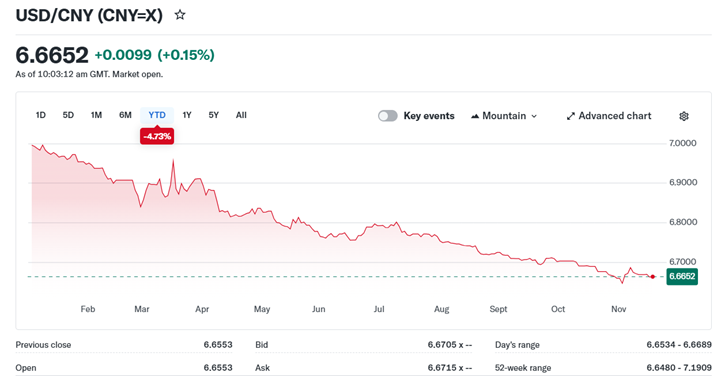
PBoC Fix 6.7118 vs exp. 6.6654 (prev. 6.7132)
Shanghai Shenzhen CSI 300 rose 0.18% to 3,983.77
President Xi opened the APEC summit in Shenzhen with a plea for the WTO and free trade, and a meeting with President Trump is on the schedule. There was no major Chinese data overnight.
.
Sources: Investing.com, Newsquawk, Associated Press, FXStreet, investingLive, Tradingpedia, Business Recorder, TradingView